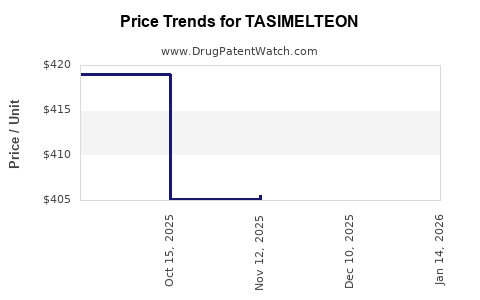
Last updated: September 21, 2026
Tasimelteon is a specialty circadian-rhythm drug marketed by Vanda Pharmaceuticals as Hetlioz and Hetlioz LQ. Its commercial value depends on two narrow indications: Non-24-hour sleep-wake disorder in totally blind adults and nighttime sleep disturbances associated with Smith-Magenis syndrome. Vanda has maintained a differentiated position through orphan indications, limited direct FDA-approved competition, and physician familiarity, but the product faces pressure from high treatment cost, reimbursement controls, generic Paragraph IV challenges, and a limited eligible population.
What is tasimelteon and which company markets it?
Tasimelteon is a melatonin-receptor agonist with activity at the MT1 and MT2 receptors. The drug regulates circadian timing rather than acting primarily as a sedative.
| Product |
Active ingredient |
Dosage form |
Sponsor |
Primary FDA use |
| Hetlioz |
Tasimelteon |
20 mg capsule |
Vanda Pharmaceuticals |
Non-24-hour sleep-wake disorder in totally blind adults |
| Hetlioz |
Tasimelteon |
20 mg capsule |
Vanda Pharmaceuticals |
Nighttime sleep disturbances in adults and certain pediatric patients with Smith-Magenis syndrome |
| Hetlioz LQ |
Tasimelteon |
Oral suspension |
Vanda Pharmaceuticals |
Smith-Magenis syndrome in patients requiring a liquid formulation |
The FDA approved Hetlioz in January 2014 for Non-24-hour sleep-wake disorder in totally blind adults. The FDA later approved tasimelteon for nighttime sleep disturbances associated with Smith-Magenis syndrome and approved the oral suspension formulation for patients who cannot use capsules. [1]
Vanda owns the U.S. commercial rights. Tasimelteon has also been commercialized outside the United States through licensing and distribution arrangements, including regional rights held by pharmaceutical partners. The product’s international contribution is smaller than its U.S. revenue base.
How large is the tasimelteon market?
Tasimelteon operates in a small orphan and specialty market rather than the broader insomnia market. The drug’s addressable population is constrained by diagnostic requirements, disease awareness, prescription access, and the requirement for long-term treatment.
The Non-24 indication is concentrated among totally blind individuals. The potential population is larger than the diagnosed and treated population because Non-24 is underdiagnosed and many patients use melatonin, hypnotics, behavioral interventions, or no treatment.
Smith-Magenis syndrome is substantially smaller. It is a rare genetic disorder with sleep disturbances caused in part by abnormal melatonin secretion. The indication supports premium orphan-drug pricing but provides limited volume expansion.
Key market drivers
- Chronic treatment duration for patients who respond to therapy.
- Limited FDA-approved alternatives for Non-24.
- Greater diagnosis of circadian-rhythm disorders.
- Expansion of pediatric and liquid-formulation use in Smith-Magenis syndrome.
- Specialty-pharmacy distribution and reimbursement support.
- Physician preference for an FDA-approved circadian regulator over off-label melatonin.
Principal market constraints
- High annual treatment cost relative to generic melatonin.
- Prior authorization and step-therapy requirements.
- Limited diagnosis of Non-24 and Smith-Magenis syndrome.
- Generic and compounded melatonin use.
- Low patient volume in the Smith-Magenis population.
- Dependence on a single commercial product for most of Vanda’s revenue.
What has been the financial trajectory for tasimelteon?
Vanda does not always disclose Hetlioz financial results in a format that separates every product, geography, and formulation. Public filings show that Hetlioz has historically been the company’s largest commercial product and a major source of recurring revenue.
Vanda’s consolidated results have reflected three major factors: Hetlioz sales, Fanapt sales, and research and development spending related to other pipeline programs. Hetlioz revenue generally increased after launch as Vanda expanded diagnosis and reimbursement coverage, then became more exposed to payer controls and generic-entry risk.
| Period |
Financial development |
Commercial interpretation |
| 2014-2016 |
U.S. launch and market development |
Revenue growth from a new orphan product; low initial penetration |
| 2017-2019 |
Broader payer access and physician adoption |
Expansion of the treated Non-24 population |
| 2020 |
Smith-Magenis approval and liquid formulation launch |
New indication and formulation increased market reach |
| 2021-2022 |
Mature specialty-product phase |
Higher installed patient base, but increased pricing and reimbursement scrutiny |
| 2023 onward |
Generic litigation and portfolio pressure |
Revenue durability increasingly depends on patent outcomes and settlement terms |
Vanda reported total revenue of approximately $133 million in 2023, with Hetlioz and Fanapt as the primary commercial products. Hetlioz remained a central contributor, although the company’s revenue mix was affected by Fanapt growth and changes in product demand. [2]
The most important financial characteristic is operating leverage. Tasimelteon has manufacturing and commercial costs that do not rise proportionally with each additional prescription. A stable patient base can therefore support strong gross margins. Conversely, a material generic price reduction or loss of market share would likely have a disproportionate effect on Vanda’s cash generation because the product supports corporate infrastructure and research spending.
When does tasimelteon lose regulatory exclusivity?
Tasimelteon’s first FDA approval received orphan-drug exclusivity for Non-24-hour sleep-wake disorder. That seven-year period expired in January 2021.
The Smith-Magenis syndrome indication received separate orphan-drug exclusivity. Because that approval occurred in 2020, the associated orphan exclusivity period generally extends into 2027, subject to the specific approval date and FDA exclusivity record. Orphan exclusivity blocks FDA approval of the same drug for the same disease or condition during the exclusivity period, but it does not prevent all patent challenges or all competing products.
| Exclusivity type |
Tasimelteon impact |
| New chemical entity exclusivity |
Expired after the standard five-year period |
| Non-24 orphan exclusivity |
Expired in 2021 |
| Smith-Magenis orphan exclusivity |
Runs into 2027 based on the 2020 approval |
| Pediatric exclusivity |
Any applicable six-month extension depends on FDA-recognized pediatric studies |
| Patent protection |
May continue after regulatory exclusivity, subject to validity and litigation outcomes |
Orphan exclusivity is indication-specific. It does not create a general seven-year monopoly over every use of tasimelteon.
What patents protect Hetlioz and tasimelteon?
Tasimelteon protection is based on a combination of composition, formulation, method-of-use, and indication-related patents. The practical commercial issue is whether a generic sponsor can enter with a label that omits protected uses or whether Vanda can establish infringement of listed patents.
The relevant patent categories include:
- Compound and composition patents. These cover tasimelteon or related chemical subject matter.
- Circadian-rhythm treatment patents. These cover administration of tasimelteon to reset or regulate circadian rhythms.
- Non-24 method-of-use patents. These relate to treatment of Non-24-hour sleep-wake disorder.
- Smith-Magenis syndrome patents. These cover treatment of nighttime sleep disturbance associated with the syndrome.
- Liquid formulation patents. These may protect the composition, concentration, stability, administration, or manufacturing of Hetlioz LQ.
- Manufacturing and process patents. These may increase the cost or complexity of producing pharmaceutical-grade tasimelteon.
The FDA Orange Book is the controlling public source for patents listed against approved drug products. The patent estate should be evaluated separately for Hetlioz capsules and Hetlioz LQ because formulation patents and indication patents may have different expiration dates and enforcement value. [3]
How strong is the tasimelteon patent estate?
The estate is commercially meaningful but not uniformly strong.
Its advantages are:
- A rare-disease commercial base with relatively few practical substitutes.
- Multiple approved indications.
- Method-of-use protection that can complicate a full-label generic launch.
- A liquid formulation that may face separate technical and patent barriers.
- The ability to assert patents against ANDA applicants after Paragraph IV notices.
Its weaknesses are:
- The original product and core regulatory exclusivities are mature.
- Generic sponsors can challenge validity, enforceability, and infringement.
- Some Non-24 patients may be reachable through off-label or non-prescription alternatives.
- Method-of-use patents are more vulnerable to skinny-label strategies than composition patents.
- The commercial value of a patent may be lower than its nominal expiration date if payers rapidly substitute a generic product.
Patent strength should therefore be measured by expected market protection, not by the number of patents alone.
Which companies are challenging tasimelteon?
Generic manufacturers have challenged Hetlioz through the abbreviated new drug application process and Paragraph IV certification. Publicly disclosed litigation has involved generic applicants including Teva, Apotex, Zydus, and Dr. Reddy’s Laboratories, although the precise status of each case and any later settlement must be confirmed against current federal docket records and FDA Orange Book updates.
| Challenger group |
Typical challenge |
Commercial significance |
| Teva |
ANDA and Paragraph IV patent challenge |
Large-scale generic manufacturing and distribution capability |
| Apotex |
ANDA-based patent challenge |
Adds pressure to capsule exclusivity |
| Zydus |
ANDA and patent challenge |
Potential additional generic entrant |
| Dr. Reddy’s Laboratories |
ANDA and patent challenge |
Increases probability of multi-source competition |
A Paragraph IV filing does not mean immediate launch. Vanda can file infringement litigation within the statutory period, triggering a regulatory stay of FDA approval for up to 30 months, subject to the details of the filing and litigation. [4]
What patent litigation affects Hetlioz?
The core litigation issue is whether the generic applicant’s proposed label and product infringe listed Vanda patents. Cases may address:
- Whether claims covering Non-24 treatment are valid.
- Whether the generic label induces infringement.
- Whether the claims are obvious in light of melatonin biology, ramelteon, and prior circadian-rhythm research.
- Whether the generic formulation falls within the scope of formulation claims.
- Whether a proposed skinny label sufficiently removes the patented use.
- Whether asserted patents are enforceable and properly listed.
A settlement can delay generic launch while allowing entry before the latest patent expiration. Its value depends on the launch date, the number of authorized generic rights, supply restrictions, royalty provisions, and whether the agreement creates a single generic entrant or multiple entrants.
Publicly announced settlements should not be interpreted as proof that Vanda’s patents are valid. Settlements usually reflect the parties’ assessment of litigation risk, expected launch economics, and the value of avoiding trial.
What is the FDA regulatory status of Hetlioz?
Hetlioz is an FDA-approved prescription drug marketed under NDA 205677. The capsule is approved for Non-24-hour sleep-wake disorder in totally blind adults and for the Smith-Magenis syndrome indication under the applicable labeling. Hetlioz LQ is approved as an oral suspension for patients with Smith-Magenis syndrome who require that dosage form. [1]
The regulatory profile is commercially favorable because:
- The drug has two approved rare-disease indications.
- There is no established FDA-approved direct substitute with the same approved Non-24 labeling.
- The Smith-Magenis indication supports continued orphan exclusivity into the 2020s.
- The liquid formulation extends product coverage beyond the capsule.
The regulatory profile also creates limitations. FDA approval does not guarantee insurance coverage, and neither orphan designation nor orphan exclusivity prevents off-label treatment with melatonin or other sleep products.
What generic entry scenarios exist for tasimelteon?
Scenario 1: No approved generic before the key patent date
Vanda retains a high-margin monopoly while litigating. Revenue depends on patient retention, reimbursement, and continued diagnosis. This is the most favorable outcome for Vanda.
Scenario 2: One generic launches under a settlement
A single generic entrant may produce a moderate price decline while preserving part of the market’s value. The impact depends on whether the generic is authorized by Vanda or independently distributed.
Scenario 3: Multiple generics launch
This is the highest-risk scenario. Pharmacy substitution and payer contracting can drive rapid loss of branded volume. Net price erosion may exceed the initial volume decline.
Scenario 4: Skinny-label generic entry
A generic may seek approval for unpatented indications while omitting a protected method of use. The commercial impact depends on the ability of pharmacies, payers, and physicians to distinguish the approved label from the branded product’s full use profile.
Scenario 5: Hetlioz LQ remains protected after capsule entry
Generic capsule entry would not necessarily eliminate the value of the liquid formulation. Hetlioz LQ could retain a protected niche among patients who cannot swallow capsules, particularly in the Smith-Magenis population.
How does tasimelteon compare with competing sleep drugs?
| Product or approach |
Primary mechanism |
Position versus tasimelteon |
| Generic melatonin |
Melatonin supplementation |
Low-cost, widely used, but variable quality and generally off-label for Non-24 |
| Ramelteon |
MT1/MT2 agonist |
FDA-approved for insomnia, not specifically for Non-24 |
| Suvorexant and lemborexant |
Orexin antagonists |
Address insomnia, not circadian entrainment |
| Zolpidem and other hypnotics |
Sedative-hypnotic mechanisms |
Symptom treatment rather than circadian correction |
| Tasimelteon |
MT1/MT2 agonist |
FDA-approved circadian treatment for Non-24 and Smith-Magenis sleep disturbance |
Tasimelteon’s differentiation is strongest in Non-24, where the commercial alternative is often off-label melatonin or behavioral management. Its differentiation is weaker in general insomnia, where several lower-cost products compete.
What licensing deals and geographic markets affect tasimelteon?
Vanda has used regional licensing and distribution arrangements for tasimelteon outside the United States. These agreements can provide geographic reach without requiring Vanda to build a full commercial organization in every market. They also reduce direct sales exposure but may limit upside through royalties, transfer pricing, or milestone structures.
The United States remains the primary value driver because:
- The product was developed and launched around the U.S. orphan market.
- U.S. pricing is higher than in most international markets.
- Vanda controls the central U.S. commercial infrastructure.
- U.S. generic litigation has the largest direct effect on revenue.
International markets provide diversification but are unlikely to offset a major U.S. generic decline on a dollar-for-dollar basis.
What manufacturing and intellectual-property barriers protect tasimelteon?
Tasimelteon is a small molecule, so it does not face the complex biological manufacturing barriers associated with monoclonal antibodies or other biologics. A capable generic manufacturer can generally reproduce the active ingredient and dosage form if it satisfies FDA quality, bioequivalence, and chemistry, manufacturing, and controls requirements.
The principal barriers are:
- Controlled synthesis of pharmaceutical-grade active ingredient.
- Stability and impurity specifications.
- Bioequivalence requirements.
- Formulation work for the oral suspension.
- Patent litigation costs.
- Limited commercial volume relative to mass-market drugs.
- Specialty-pharmacy and payer access requirements.
The manufacturing barrier is therefore meaningful but not likely to be the primary long-term defense against generic entry. Patent claims, regulatory exclusivity, and commercial contracting are more important.
What is the revenue exposure to tasimelteon?
Tasimelteon remains a material concentration risk for Vanda. A sustained decline in Hetlioz revenue could reduce:
- Cash available for clinical development.
- Ability to support specialty sales infrastructure.
- Investment in label expansion.
- Negotiating leverage with commercial partners.
- Corporate valuation based on recurring orphan-drug cash flow.
The risk is not limited to unit loss. A generic launch can affect gross-to-net deductions, payer rebates, specialty-pharmacy economics, and the price required to retain branded patients. A 20% decline in branded prescriptions can produce a larger percentage decline in product profit if discounts increase at the same time.
Key Takeaways
- Tasimelteon is a specialty circadian-rhythm drug marketed as Hetlioz and Hetlioz LQ.
- Its core value comes from Non-24-hour sleep-wake disorder and Smith-Magenis syndrome.
- Non-24 orphan exclusivity expired in 2021; Smith-Magenis orphan exclusivity extends into 2027 based on the 2020 approval.
- The product has no broad direct FDA-approved substitute for Non-24, but generic melatonin is a significant practical competitor.
- Vanda’s commercial exposure is concentrated in a small patient population and a limited number of products.
- Generic Paragraph IV challenges from major manufacturers create the principal medium-term risk.
- Capsule and liquid-formulation protection should be analyzed separately.
- A single generic entrant could cause moderate erosion; multiple entrants could cause rapid price and volume decline.
- Tasimelteon is a small molecule, so manufacturing barriers are less durable than patent and regulatory barriers.
- The most important valuation variables are generic launch timing, settlement terms, patent survival, patient retention, and U.S. reimbursement.
FAQs
Is tasimelteon the same as melatonin?
No. Tasimelteon is a prescription MT1 and MT2 melatonin-receptor agonist. Melatonin is an endogenous hormone sold in many markets as a supplement. Tasimelteon has FDA-approved indications and standardized pharmaceutical manufacturing.
Can tasimelteon be used for ordinary insomnia?
Tasimelteon is not broadly approved for ordinary insomnia. Its FDA-approved uses center on circadian-rhythm disorders and Smith-Magenis-related nighttime sleep disturbances. Use outside the approved label is determined by the treating physician.
Does tasimelteon have biosimilar risk?
No. Tasimelteon is a chemically synthesized small molecule, not a biologic. It faces conventional generic-drug risk through the ANDA pathway rather than biosimilar competition.
Why is Hetlioz expensive compared with melatonin?
Hetlioz is an FDA-approved prescription product supported by clinical development, specialty distribution, and orphan-disease commercialization. Generic melatonin is widely available at much lower prices but may have variable quality and does not carry the same FDA-approved indication.
What would happen to Vanda if a generic tasimelteon launches?
The likely effects would include lower branded prescription volume, payer-driven substitution, price concessions, and reduced cash flow. The severity would depend on the number of entrants, launch timing, settlement restrictions, authorized-generic arrangements, and continued demand for the liquid formulation.
References
- U.S. Food and Drug Administration. (2020). Hetlioz prescribing information.
- Vanda Pharmaceuticals Inc. (2024). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 for the fiscal year ended December 31, 2023.
- U.S. Food and Drug Administration. (n.d.). Orange Book: Approved drug products with therapeutic equivalence evaluations.
- U.S. Food and Drug Administration. (n.d.). Abbreviated new drug application submissions and Paragraph IV certifications.