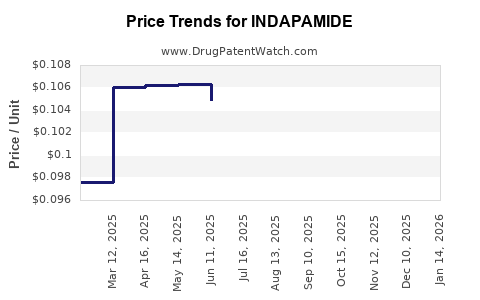
Last updated: September 3, 2026
Indapamide is a mature, off-patent thiazide-like diuretic with limited standalone revenue potential and low generic-entry risk because generic products have been marketed for decades. Commercial value is concentrated in manufacturing efficiency, regional distribution, sustained-release formulations, fixed-dose combinations, and supply reliability rather than exclusivity. No meaningful biosimilar risk exists because indapamide is a small-molecule drug.
What is indapamide and where is it used?
Indapamide is an oral antihypertensive and diuretic used primarily to treat hypertension. It is structurally related to thiazide diuretics but is generally classified as a thiazide-like diuretic.
| Attribute |
Indapamide |
| Active ingredient |
Indapamide |
| Drug class |
Thiazide-like diuretic |
| Primary use |
Hypertension |
| Common immediate-release strengths |
1.25 mg and 2.5 mg |
| Common sustained-release strength |
1.5 mg |
| Administration |
Oral tablet |
| Regulatory status |
Generic and legacy branded products |
| Biologic status |
Small molecule |
| Biosimilar pathway |
Not applicable |
| Main competitors |
Hydrochlorothiazide, chlorthalidone, bendroflumethiazide, amlodipine and combination antihypertensives |
| Commercial maturity |
Mature, low-growth generic market |
Indapamide reduces sodium reabsorption in the distal nephron and lowers blood pressure through diuretic and vascular effects. It is used as monotherapy or in combination with other antihypertensive drugs.
The principal branded product in the United States was Lozol. The active ingredient is now supplied predominantly through generic manufacturers and regional branded-generic companies. European markets have historically included sustained-release indapamide products such as Natrilix SR and generic equivalents.
When did indapamide lose exclusivity?
Indapamide lost meaningful commercial exclusivity many years ago. The product was introduced in the 1970s and received U.S. Food and Drug Administration approval for hypertension in the early 1980s. Generic competition followed after the expiration of the original product and formulation protections.
The original commercial opportunity is therefore no longer protected by a live composition-of-matter patent. Current competition is based on abbreviated new drug applications, manufacturing scale, quality records, procurement contracts, and local regulatory registrations.
Indapamide exclusivity timeline
| Period |
Commercial event |
| 1970s |
Initial European commercialization of indapamide |
| Early 1980s |
U.S. approval of legacy branded indapamide tablets |
| Late 1980s and 1990s |
Expansion of generic and regional branded supply |
| 2000s |
Broad global availability of immediate-release generic products |
| 2010s |
Expansion of sustained-release and fixed-dose combination products |
| 2020s |
Mature commodity market with localized shortages and supplier consolidation |
The exact patent and regulatory history varies by jurisdiction and dosage form. The practical conclusion is consistent across major markets: original indapamide exclusivity is expired, and a new entrant does not need to wait for a meaningful originator patent barrier.
What patents protect indapamide products?
No active composition-of-matter patent is generally considered to protect conventional indapamide tablets in the major generic markets. The original compound and legacy immediate-release products are long past ordinary patent terms.
Potentially relevant intellectual property can instead involve:
- Sustained-release tablet matrices
- Particle-size control
- Granulation and coating processes
- Combination products
- Manufacturing processes
- Packaging and stability systems
- Country-specific formulation claims
These rights have limited commercial impact unless they cover a differentiated product with regulatory approval and meaningful prescribing or procurement demand.
Formulation patents and sustained-release products
The most commercially relevant product differentiation is the 1.5 mg sustained-release formulation used in several European and international markets. Sustained-release products can reduce dosing frequency and may provide a marketing distinction against 1.25 mg or 2.5 mg immediate-release tablets.
A formulation patent would need to be assessed claim by claim. A release-profile claim alone may have limited value if competing manufacturers can use a different excipient system or manufacturing process. The practical strength of such rights depends on:
- Whether the patent remains unexpired in the target country.
- Whether the product is listed in the relevant regulatory database.
- Whether the claims cover the marketed dosage form.
- Whether a generic can design around the release mechanism.
- Whether the product has enough sales to justify litigation.
For indapamide, formulation protection is more likely to influence individual products than the overall market.
What is the Orange Book status of indapamide?
The U.S. Orange Book historically listed the branded Lozol product and may list approved generic indapamide products depending on current marketing status. Legacy Orange Book listings do not create continuing exclusivity after listed patents and regulatory exclusivities expire.
The key U.S. regulatory facts are:
- Indapamide is approved as an oral tablet for hypertension.
- Generic versions may rely on an abbreviated new drug application.
- Generic products must demonstrate pharmaceutical equivalence and bioequivalence.
- No current reference-product exclusivity is expected to block ordinary generic competition.
- Orange Book relevance is limited primarily to product identification, reference-product status, and any remaining listed patents.
A definitive current Orange Book assessment requires a live review of FDA listings because product marketing status, discontinued products, and patent records can change. The commercial conclusion remains that indapamide is a mature generic product with no meaningful market-wide Orange Book barrier.
Are there Paragraph IV challenges for indapamide?
Paragraph IV litigation is unlikely to be a significant current market issue for conventional indapamide. Paragraph IV certifications are most relevant when a generic applicant seeks approval before expiration of a listed patent. Indapamide’s primary patents and original formulation protections expired long ago.
Possible Paragraph IV activity could arise for:
- A newly developed sustained-release product
- A branded fixed-dose combination
- A reformulated dosage form
- A narrow manufacturing patent
- A new indication supported by separate regulatory exclusivity
Those scenarios would affect a specific product rather than the established indapamide market. The absence of meaningful current patent barriers reduces both litigation risk and the value of defensive patent portfolios.
What generic entry risks exist for indapamide?
Generic entry risk is already realized rather than prospective. The market has multiple suppliers in many jurisdictions, and new entrants can generally compete without challenging a commercially important composition patent.
Generic competition factors
| Factor |
Impact on indapamide |
| Patent barrier |
Low |
| Regulatory complexity |
Low to moderate |
| Manufacturing complexity |
Low for immediate-release tablets |
| Sustained-release complexity |
Moderate |
| Switching costs |
Low |
| Physician brand loyalty |
Limited |
| Tender dependence |
High in public markets |
| Price erosion |
Persistent |
| Shortage exposure |
Material where supplier concentration is high |
Immediate-release tablets are relatively straightforward to manufacture. Sustained-release tablets require tighter control of dissolution, content uniformity, and release specifications, but they remain conventional oral solid dosage forms.
The most significant competitive risk is price compression. Suppliers with low-cost active pharmaceutical ingredient sourcing, high-volume tableting capacity, and established regulatory dossiers can compete aggressively in tenders and pharmacy channels.
How strong is the indapamide patent estate?
The overall patent estate is weak from an exclusivity perspective and moderate only for selected product-level formulations.
| Patent category |
Strategic strength |
| Original compound patent |
Expired |
| Original immediate-release formulation |
Expired or commercially immaterial |
| Sustained-release formulation |
Potentially relevant by jurisdiction and claim scope |
| Fixed-dose combination |
Product-specific |
| Manufacturing process |
Usually narrow and design-around risk is high |
| New method of use |
Limited value without regulatory exclusivity |
| Data exclusivity |
Generally expired for legacy products |
| Biosimilar protection |
Not applicable |
A new patent filing on a conventional indapamide tablet would face patentability risks, including obviousness and lack of novelty. A stronger position would require a clinically meaningful release profile, a technically difficult manufacturing process, or a combination product with unexpected therapeutic performance.
What method-of-use patents cover indapamide?
Indapamide’s core use in hypertension is established and widely disclosed. Broad method-of-use claims for treating ordinary hypertension would have limited patentability and commercial value.
Potential method-of-use opportunities could involve:
- A defined patient subgroup
- A specific renal or cardiovascular risk population
- A dosing regimen supported by clinical evidence
- Combination treatment with a specified antihypertensive
- A formulation linked to an improved safety or adherence profile
These claims would be difficult to enforce across a mature generic market unless the indication had clear regulatory recognition and the product generated substantial incremental revenue.
How does indapamide compare with hydrochlorothiazide and chlorthalidone?
Indapamide competes primarily with other low-cost diuretics and with first-line antihypertensive agents.
| Product |
Class |
Typical commercial position |
Competitive issue |
| Indapamide |
Thiazide-like diuretic |
Generic, regional strength in Europe and selected markets |
Limited differentiation |
| Hydrochlorothiazide |
Thiazide diuretic |
Very broad generic use |
Lower-cost default option |
| Chlorthalidone |
Thiazide-like diuretic |
Strong clinical interest in some guidelines |
Longer duration and electrolyte monitoring |
| Amlodipine |
Calcium-channel blocker |
Large generic market |
Broad use and simple dosing |
| Perindopril/indapamide |
Fixed-dose combination |
Branded-generic opportunity |
Combination-product competition |
Indapamide can compete on duration of action, blood-pressure control, and combination use. It does not generally command a substantial premium over other generic diuretics. In many markets, treatment choice is influenced more by guidelines, physician familiarity, tender pricing, and availability than by patent-protected differentiation.
What are the main indapamide licensing and partnering opportunities?
Licensing opportunities are limited for the legacy active ingredient. Commercial transactions are more likely to involve:
- Regional marketing rights
- Generic product registrations
- Contract manufacturing
- Sustained-release formulations
- Fixed-dose combinations
- Supply agreements for public tenders
- Portfolio acquisitions involving several cardiovascular generics
A transaction focused only on standard immediate-release indapamide would typically have modest strategic value. A broader cardiovascular portfolio can improve economics by sharing sales infrastructure, regulatory staff, wholesalers, and tender participation.
The most valuable assets are likely to be:
- Approved dossiers in multiple jurisdictions.
- Reliable API supply.
- Sustained-release manufacturing capability.
- Combination-product approvals.
- Established hospital and pharmacy distribution.
- A history of uninterrupted supply.
What is the financial trajectory for indapamide?
Indapamide has a low-growth or declining standalone financial profile in mature markets. Revenue is pressured by generic price erosion, therapeutic substitution, and tender competition. Unit demand may remain stable because hypertension is chronic and prevalent, but stable volume does not translate into stable revenue.
Revenue drivers
The financial trajectory depends on:
- Prescription volume
- Country mix
- Immediate-release versus sustained-release product share
- Generic price levels
- Public-tender exposure
- Manufacturing costs
- API pricing
- Product shortages
- Fixed-dose combination penetration
- Regulatory maintenance costs
| Financial variable |
Expected direction in mature markets |
| Prescription volume |
Stable to modest growth |
| Net price |
Downward pressure |
| Gross margin |
Stable for efficient suppliers; compressed for small suppliers |
| Standalone revenue |
Flat to declining |
| Combination-product revenue |
More resilient |
| R&D spending |
Minimal |
| Litigation spending |
Low |
| Manufacturing value |
Increasingly important |
| Portfolio value |
Higher than standalone product value |
Public company filings often do not report indapamide revenue separately. It is commonly included within broader cardiovascular, generic, or prescription-product categories. As a result, a precise global indapamide market size or company-level revenue forecast should not be inferred from aggregate hypertension-drug figures.
Revenue exposure by business model
| Business model |
Indapamide exposure |
| Originator brand |
Minimal or discontinued in many markets |
| Large generic company |
Low individual-product contribution, useful portfolio volume |
| Regional branded generic company |
Potentially meaningful in selected countries |
| Contract manufacturer |
Volume-driven, low pricing power |
| API supplier |
Sensitive to scale and supply contracts |
| Combination-product owner |
Higher margin potential |
| Tender-focused distributor |
High volume, low margin |
The financial upside is more credible from portfolio integration than from standalone price expansion. A supplier can improve returns through manufacturing scale, reduced batch costs, multi-country registrations, and combination-product sales.
What regulatory risks affect indapamide?
The regulatory burden is established but not negligible. Key risks include:
- Dissolution failures for sustained-release tablets
- Stability problems in hot or humid climates
- Impurity and elemental impurity controls
- Manufacturing-site inspection findings
- Bioequivalence requirements for modified-release products
- Labeling differences across countries
- Supply interruptions caused by API or packaging shortages
- Pharmacovigilance obligations for electrolyte abnormalities
Indapamide can cause hyponatremia, hypokalemia, dehydration, hypotension, and renal-function changes. Labeling and post-market monitoring remain important even though the molecule is old.
What patent litigation affects indapamide?
No major market-wide patent litigation is expected to constrain conventional indapamide tablets. Litigation exposure is more likely to arise from:
- A sustained-release formulation
- A fixed-dose combination
- A newly branded product
- A manufacturing process
- A license or supply dispute
- Regulatory exclusivity surrounding an incremental reformulation
The low litigation profile reduces launch risk for generic manufacturers. It also limits the defensive value of acquiring legacy patent assets without accompanying regulatory approvals or commercial distribution.
What generic launch scenarios are most likely?
Immediate-release generic launch
This is the lowest-risk scenario. A manufacturer with an approved dossier can compete on price, supply reliability, and wholesaler access. The likely outcome is further price erosion unless the market has few active suppliers.
Sustained-release generic launch
This requires more formulation and bioequivalence capability. The product can obtain better pricing than a standard immediate-release tablet if physicians or procurement agencies value once-daily dosing and established clinical use.
Fixed-dose combination launch
Combination products can create stronger commercial differentiation, especially when paired with an ACE inhibitor or another antihypertensive. The opportunity is still exposed to generic substitution and country-specific registration requirements.
Supply-constrained launch
A new supplier can gain share quickly during a shortage. This advantage may be temporary because additional manufacturers can enter once the pricing opportunity becomes visible.
What geographic markets are most attractive for indapamide?
Indapamide has historically had stronger recognition in Europe and selected international markets than in the United States, where hydrochlorothiazide and chlorthalidone are deeply established.
Geographic considerations
| Region |
Market characteristics |
| United States |
Mature generic market; limited differentiation; strong competition from hydrochlorothiazide and chlorthalidone |
| Western Europe |
Established use of immediate-release and sustained-release products; tender and reimbursement pressure |
| Central and Eastern Europe |
Branded-generics opportunity; price sensitivity and local registration requirements |
| Asia-Pacific |
Large hypertension population; fragmented generic supply; local manufacturing advantage |
| Latin America |
Regional brand recognition and distributor access matter |
| Middle East and Africa |
Procurement, registration, and supply reliability are critical |
The best commercial opportunities are usually country-specific. A company with a strong local sales force, tender access, or an existing cardiovascular portfolio can extract more value than a company entering with an isolated product.
Key Takeaways
- Indapamide is a mature, off-patent small-molecule antihypertensive.
- Original composition and conventional tablet exclusivity have expired.
- Paragraph IV litigation and market-wide patent barriers are low-risk issues.
- Sustained-release and fixed-dose combination products offer the main remaining differentiation.
- Biosimilar risk does not apply.
- Revenue is likely stable to declining on a standalone basis because generic price erosion offsets durable hypertension demand.
- Manufacturing scale, API supply, tender access, and portfolio integration determine profitability.
- Geographic value is strongest where indapamide has established physician familiarity or branded-generic demand.
- Patent strength is weak for the molecule and moderate only for selected formulation or combination products.
- A new entrant’s main risk is commercial commoditization, not patent infringement.
FAQs
Is indapamide still under patent in the United States?
Conventional indapamide tablets are not generally protected by an active composition-of-matter patent in the United States. Any relevant rights would likely concern a specific formulation, combination, or manufacturing process.
Can a generic manufacturer launch indapamide without a Paragraph IV challenge?
Yes. Because the core product is long off patent, a generic applicant can generally rely on an abbreviated approval pathway without challenging a commercially important active patent.
Is indapamide more profitable than hydrochlorothiazide?
Usually not on a standalone basis. Hydrochlorothiazide has greater volume, while indapamide may offer better portfolio value in countries with established branded-generic or sustained-release demand.
Does indapamide have a biosimilar market?
No. Indapamide is a chemically synthesized small molecule. Competition occurs through generic-drug pathways, not biosimilar development.
What is the strongest commercial opportunity in indapamide?
The strongest opportunities are sustained-release formulations, fixed-dose combinations, regional branded-generics, and reliable supply in markets where incumbent manufacturers face shortages or limited competition.
References
-
DailyMed. (n.d.). Indapamide tablet prescribing information. U.S. National Library of Medicine.
-
U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (n.d.). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
National Institute for Health and Care Excellence. (2019). Hypertension in adults: Diagnosis and management. NICE guideline NG136.
-
Williams, B., Mancia, G., Spiering, W., et al. (2018). 2018 ESC/ESH guidelines for the management of arterial hypertension. European Heart Journal, 39(33), 3021-3104.
-
World Health Organization. (2021). WHO guideline for the pharmacological treatment of hypertension in adults. World Health Organization.