Last updated: September 8, 2026
Haloperidol lactate is a mature, low-cost generic injectable antipsychotic used mainly in hospitals, emergency departments, psychiatric facilities, and long-term-care settings. The product has no meaningful branded-drug exclusivity, no biosimilar exposure, and limited patent leverage. Commercial performance is driven by hospital-contract access, manufacturing reliability, shortages, injectable capacity, and reimbursement rather than innovation or pricing power.
The market is structurally fragmented. Several generic manufacturers can supply haloperidol lactate injection, but the number of dependable suppliers is narrower than the number of approved products because sterile injectable manufacturing is exposed to plant shutdowns, quality remediation, raw-material constraints, and procurement concentration.
What is haloperidol lactate and how is it used?
Haloperidol lactate is the injectable salt form of haloperidol, a first-generation antipsychotic in the butyrophenone class. In the United States, haloperidol lactate injection is supplied primarily at a concentration of 5 mg/mL.
The FDA labeling covers treatment of manifestations of psychotic disorders. In hospital practice, the injection is also used for acute agitation and behavioral emergencies, subject to institutional protocols and clinical judgment. It is administered intramuscularly and, in some settings, intravenously under monitored conditions. The label warns about extrapyramidal symptoms, tardive dyskinesia, neuroleptic malignant syndrome, QT prolongation, and other serious adverse events.[1]
Haloperidol lactate is distinct from haloperidol decanoate. Haloperidol decanoate is a long-acting intramuscular formulation for maintenance treatment, while haloperidol lactate is the short-acting injectable formulation used when rapid parenteral administration is required.
Key product attributes
| Attribute |
Haloperidol lactate injection |
| Active ingredient |
Haloperidol lactate |
| Drug class |
First-generation antipsychotic |
| Common strength |
5 mg/mL |
| Primary route |
Intramuscular; intravenous use is label- and protocol-dependent |
| Typical customers |
Hospitals, emergency departments, psychiatric facilities, long-term-care providers |
| FDA pathway |
Abbreviated New Drug Application products and legacy NDA product |
| Competitive category |
Generic sterile injectable |
| Biosimilar relevance |
None |
| Main commercial risks |
Supply interruption, low margins, procurement concentration, quality events |
What is the FDA regulatory status of haloperidol lactate?
Haloperidol lactate injection is an FDA-approved prescription product. Generic versions are approved through the ANDA pathway by demonstrating pharmaceutical equivalence and bioequivalence to the reference product, rather than repeating the full clinical development program required for a new drug.[2]
The reference product historically associated with injectable haloperidol was Haldol, marketed by Janssen. Current U.S. supply is primarily generic. FDA labeling databases and DailyMed identify multiple manufacturers and label holders for haloperidol lactate injection, including major generic injectable companies and contract-manufacturing participants.[3]
The product has no meaningful current FDA exclusivity period. Its clinical use, active ingredient, and basic dosage form have been established for decades. New entrants therefore compete through abbreviated approval, manufacturing capability, purchasing contracts, and supply performance.
Does haloperidol lactate have FDA market exclusivity?
No commercially material FDA exclusivity remains for haloperidol lactate injection. Any historic new-drug exclusivity associated with the original product expired many years ago. Generic manufacturers can seek approval through ANDAs, subject to FDA requirements for product quality, manufacturing, labeling, and bioequivalence.
No pediatric exclusivity or orphan-drug exclusivity is associated with the ordinary haloperidol lactate injection market.
What patents protect haloperidol lactate?
The core haloperidol molecule, the lactate salt, and the conventional injectable formulation are not protected by an active U.S. patent estate with meaningful commercial force. The relevant composition and basic formulation concepts date back several decades.
| Patent category |
Current commercial relevance |
| Haloperidol compound patents |
Expired |
| Haloperidol lactate salt claims |
Expired or no longer commercially blocking |
| Conventional 5 mg/mL injection claims |
No material active exclusivity identified |
| Method-of-use patents |
No material blocking estate for ordinary labeled use |
| Manufacturing patents |
Potentially relevant to individual suppliers, but not a market-wide barrier |
| Device or delivery patents |
Limited relevance to standard ampules and vials |
The FDA Orange Book is the principal source for patents and exclusivity associated with approved drug products. Haloperidol lactate injection does not present the type of listed-patent structure associated with newer branded medicines such as small-molecule oncology drugs, long-acting injectables, or complex drug-delivery systems.[4]
Are there Paragraph IV challenges for haloperidol lactate?
Paragraph IV litigation is not a meaningful current market feature. Paragraph IV certifications are generally used when an ANDA applicant challenges an unexpired patent listed for a reference drug. Because the conventional haloperidol lactate injection market lacks a commercially blocking patent estate, generic entry does not depend on defeating a live branded patent portfolio.
Potential disputes are more likely to concern manufacturing, product quality, labeling, supply contracts, or antitrust issues than patent validity.
How many manufacturers supply haloperidol lactate?
The U.S. market has multiple approved generic suppliers, but the practical supplier base is smaller than the approval count. Manufacturers that have marketed or listed haloperidol lactate injection products have included Hikma Pharmaceuticals, Fresenius Kabi, Teva Pharmaceuticals, and other generic injectable companies, depending on product presentation and commercial availability.[3]
The market should be assessed by active commercial supply rather than by historical ANDA approvals. A company may retain an approved product while reducing production, discontinuing a presentation, or supplying only selected contract customers.
What drives competition among manufacturers?
Price is important but not decisive. Hospital buyers usually evaluate:
- Contract price and wholesaler availability.
- Ability to supply standard vial or ampule presentations.
- FDA inspection history and quality performance.
- Back-order frequency and allocation practices.
- Product consistency and packaging compatibility.
- Participation in group purchasing organization contracts.
- Capacity to maintain supply during competitor outages.
Sterile injectable products have higher operational barriers than oral tablets. The active pharmaceutical ingredient is inexpensive, but the finished product requires validated aseptic processing, container-closure integrity, sterility testing, visual inspection, and controlled packaging operations. These requirements limit rapid market entry and make manufacturing quality central to commercial value.
What is the Orange Book status of haloperidol lactate?
The Orange Book identifies approved drug products, reference-listed drugs, therapeutic equivalents, patents, and exclusivity where applicable. Haloperidol lactate injection is a mature generic category with therapeutic-equivalence listings rather than a branded patent platform.[4]
The Orange Book does not establish market share, actual supply, or financial performance. A product can remain listed while being intermittently unavailable or commercially inactive. Supply analysis should therefore combine Orange Book data with FDA drug-shortage records, manufacturer labeling, wholesaler data, and hospital procurement information.
What patent litigation affects haloperidol lactate?
No major active patent litigation is associated with the conventional U.S. haloperidol lactate injection market in the public record through the mature generic-market period. The absence of litigation is consistent with the expired core patent position and the lack of a high-value branded franchise.
Litigation risk is more likely to arise from:
- Product liability claims involving cardiac or neurological adverse events.
- Manufacturing-quality disputes.
- Contract and supply-allocation disputes.
- False Claims Act or reimbursement issues.
- Labeling and pharmacovigilance matters.
These risks affect operating cost and liability exposure but do not create exclusivity for a supplier.
When did haloperidol lactate lose exclusivity?
Haloperidol lactate lost meaningful small-molecule exclusivity decades ago. The drug was introduced in the 1960s, and generic competition has existed for many years. The market therefore has no conventional branded-to-generic transition remaining.
The commercial issue is supply resilience, not the timing of generic entry. Any future entrant would compete against established manufacturers with existing regulatory approvals and hospital purchasing relationships.
What is the financial trajectory for haloperidol lactate?
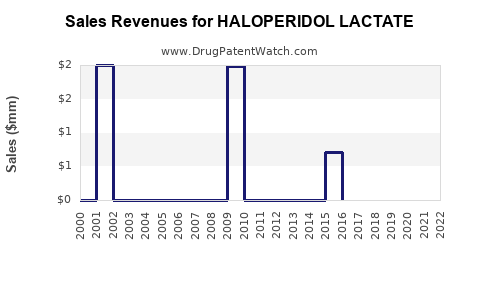
Haloperidol lactate does not generate a separately disclosed revenue line for most manufacturers. Public companies generally report broad segments such as injectables, generic pharmaceuticals, or hospital products rather than revenue for an individual mature generic.
Its financial trajectory is best characterized as follows:
| Period |
Market condition |
Financial implication |
| Historical launch period |
Branded antipsychotic development and expansion |
High relative product value |
| Genericization period |
Multiple suppliers and price competition |
Sharp erosion in unit economics |
| Mature generic period |
Low acquisition cost and stable institutional demand |
Low revenue per unit, recurring volume |
| Shortage periods |
Reduced effective supply and emergency procurement |
Temporary price and margin improvement |
| Long-term outlook |
Persistent demand but limited innovation |
Stable or declining nominal revenue, with episodic volatility |
Haloperidol lactate is a low-revenue product at the individual molecule level but can have strategic value within a hospital injectable portfolio. It helps manufacturers fill contracts, maintain account relationships, and use existing sterile-manufacturing capacity. The product may be economically attractive when it is produced on a flexible line with low incremental cost and reliable demand.
The principal financial risk is margin compression. Large buyers and group purchasing organizations can negotiate aggressively because the product is generic, clinically familiar, and often substitutable across approved suppliers. Manufacturers also face rising costs for labor, quality systems, environmental controls, container components, and regulatory compliance.
Does haloperidol lactate have shortage-driven pricing power?
Only temporarily. Injectable haloperidol products can experience supply pressure when one or more manufacturers report production problems, facility interruptions, or discontinuations. FDA shortage records are relevant because a shortage can shift orders to remaining suppliers and increase the value of available inventory.[5]
Shortage-driven pricing is constrained by:
- Hospital budget controls.
- Contract pricing.
- Availability of alternative antipsychotics.
- Government and institutional purchasing rules.
- The low absolute cost of the product.
- FDA and wholesaler scrutiny during constrained supply.
A supplier may improve utilization or contract position during a shortage, but shortages do not create durable product exclusivity.
What generic entry risks exist for haloperidol lactate?
Generic entry risk is already realized. The product is fully genericized, and additional entrants could intensify price competition if they obtain approval and secure commercial distribution.
The more material risk is reverse supply concentration. If low prices cause manufacturers to exit, the market may become dependent on a small number of sterile-injectable suppliers. A new entrant may then find an attractive opening, but FDA approval, aseptic capacity, validation, and hospital contracting can delay commercialization.
What could cause a new entrant to fail commercially?
Approval alone is insufficient. A new supplier would need:
- A dependable FDA-compliant sterile facility.
- Commercial-scale manufacturing economics.
- Wholesaler and group purchasing access.
- Competitive packaging and presentations.
- A record of consistent fill rates.
- Working capital to support inventory and receivables.
The product’s low price limits the value of a standalone launch. A manufacturer is more likely to launch haloperidol lactate as part of a broader hospital-injectable portfolio.
How does haloperidol lactate compare with haloperidol decanoate?
| Factor |
Haloperidol lactate |
Haloperidol decanoate |
| Formulation |
Short-acting lactate injection |
Long-acting decanoate injection |
| Primary use |
Acute treatment or rapid control |
Maintenance treatment |
| Administration |
More frequent or episodic |
Scheduled depot administration |
| Commercial demand |
Hospital and emergency-care driven |
Psychiatric maintenance-care driven |
| Patent value |
Mature generic |
Mature generic, with formulation and administration distinctions |
| Supply economics |
Low-cost sterile injectable |
Higher value per treatment course in some settings |
| Substitution |
Competes with other acute antipsychotics |
Competes with other long-acting injectables |
Haloperidol decanoate may have greater commercial value per administration because it is a long-acting product used in ongoing treatment. Haloperidol lactate has broader acute-care relevance but lower pricing power.
What is the competitive landscape for acute injectable antipsychotics?
Haloperidol lactate competes with injectable or rapidly administered products including olanzapine, ziprasidone, droperidol, and certain formulations of other antipsychotics. The products differ in safety profile, route, onset, monitoring requirements, formulary status, and acquisition cost.
Haloperidol retains a role where clinicians value familiarity, rapid parenteral availability, low acquisition cost, and broad institutional experience. Its disadvantages include extrapyramidal symptoms, akathisia, dystonia, QT-related concerns, and the need for clinical monitoring in higher-risk patients.
Competitive substitution is therefore clinical and operational rather than patent-driven. A hospital may retain haloperidol because it is inexpensive and familiar, while limiting its use in patients with elevated cardiac or neurological risk.
What licensing deals affect haloperidol lactate?
No major current licensing transaction is central to the haloperidol lactate market. The product is a mature generic, and commercial rights are generally handled through manufacturer supply agreements, distributor relationships, contract manufacturing, and group purchasing contracts rather than high-value innovation licenses.
A licensing or asset-transfer transaction involving haloperidol lactate would likely be part of a broader generic portfolio deal. Its valuation would depend on manufacturing capacity, existing contracts, supply history, and facility economics rather than patent duration.
What geographic markets are most relevant?
The United States remains commercially important because hospital procurement is concentrated and sterile injectable shortages can affect pricing and supply access. European markets are also mature and genericized, but pricing, reimbursement, tender structures, and national procurement policies differ.
In lower-income markets, haloperidol may retain stronger unit demand because of its low price and established clinical role. Revenue potential remains limited because pricing is constrained. Regulatory registration, local manufacturing rules, tender access, and supply reliability determine market participation.
How strong is the haloperidol lactate patent estate?
The patent estate is weak for exclusivity purposes and moderate only as an operational barrier when combined with sterile manufacturing requirements. There is no significant composition-of-matter moat, no material Orange Book patent barrier, and no meaningful branded pricing platform.
The strongest barriers are:
- FDA-compliant sterile production.
- Quality-control infrastructure.
- Hospital contracting.
- Reliable distribution.
- Ability to withstand low margins.
- Supply continuity during shortages.
These barriers can support a profitable generic portfolio position but cannot sustain monopoly pricing.
Key Takeaways
- Haloperidol lactate is a mature, fully genericized injectable antipsychotic.
- The standard U.S. product is commonly supplied as a 5 mg/mL injection.
- Core compound, salt, and conventional formulation exclusivity expired decades ago.
- No material Paragraph IV patent challenge or active branded patent dispute drives the market.
- Revenue is not generally disclosed by molecule because manufacturers report broader injectable or generic segments.
- Financial performance depends on hospital contracts, manufacturing utilization, supply reliability, and shortage conditions.
- Sterile injectable production creates more commercial friction than the expired patent estate.
- Haloperidol decanoate has a different commercial profile because it is a long-acting maintenance formulation.
- Biosimilar risk is irrelevant because haloperidol lactate is a small-molecule generic.
- The long-term outlook is stable demand with low pricing power and episodic supply-driven volatility.
FAQs
Is haloperidol lactate still commercially available in the United States?
Yes. FDA-approved generic haloperidol lactate injection products remain part of the U.S. hospital injectable market, although individual presentations can experience discontinuation, back orders, or temporary shortages.
Is haloperidol lactate listed in the FDA Orange Book?
Approved generic and reference-product information is reflected through FDA Orange Book listings, but the Orange Book should be read together with current labeling and shortage information because listing does not confirm active commercial supply.
Can a company obtain exclusivity for a new haloperidol lactate injection?
A new formulation, delivery system, or qualifying clinical use could create intellectual-property or regulatory opportunities, but the conventional 5 mg/mL injectable product has no practical basis for new market exclusivity.
Is haloperidol lactate more profitable than oral haloperidol?
Not usually on a unit-margin basis. Injectable products can carry greater manufacturing and quality costs. Profitability depends on contract position, plant utilization, shortage conditions, and portfolio economics rather than the active ingredient alone.
What is the main investment risk in haloperidol lactate?
The main risk is declining margin from generic price competition combined with sterile-manufacturing disruption. The principal upside is temporary supply tightness or improved capacity utilization within a broader hospital-injectable portfolio.
References
-
U.S. Food and Drug Administration. (2023). Haloperidol lactate injection prescribing information. DailyMed. https://dailymed.nlm.nih.gov/
-
U.S. Food and Drug Administration. (2024). Generic drug facts. https://www.fda.gov/drugs/generic-drugs
-
National Library of Medicine. (2024). DailyMed: Haloperidol lactate injection product labeling. https://dailymed.nlm.nih.gov/
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book-data-files
-
U.S. Food and Drug Administration. (2024). Drug shortages database. https://www.accessdata.fda.gov/scripts/drugshortages/