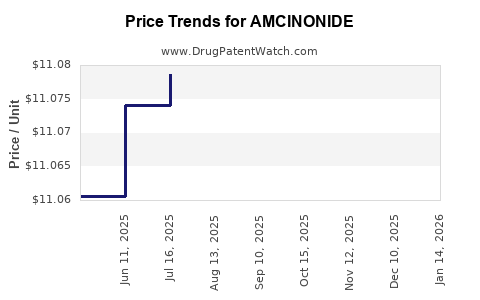
Last updated: September 4, 2026
Amcinide, marketed historically as Cyclocort, is an off-patent topical corticosteroid with limited commercial differentiation. Its market is driven by generic substitution, dermatology prescribing patterns, pharmacy reimbursement, and availability across cream, ointment, and lotion formulations. The product has no meaningful remaining brand exclusivity, no material biosimilar issue, and limited public financial disclosure. Revenue exposure is concentrated in low-priced generic topical prescriptions rather than a protected branded franchise.
What is amcinonide and how is it used?
Amcinonide is a high-potency topical corticosteroid used to treat corticosteroid-responsive inflammatory and pruritic dermatoses. Commercial products generally contain amcinonide 0.1% and have been supplied as cream, ointment, and lotion formulations. The drug is applied topically and is not a biologic, systemic small-molecule product, or injectable therapy.
The FDA labeling identifies use for inflammatory manifestations of corticosteroid-responsive dermatoses. Treatment duration and surface area are generally limited because topical corticosteroids can cause local adverse effects, including skin atrophy, striae, telangiectasia, and hypothalamic-pituitary-adrenal axis suppression when used extensively or under occlusion (U.S. Food and Drug Administration [FDA], 2019).
Amcinonide product profile
| Attribute |
Amcinonide |
| Active ingredient |
Amcinonide |
| Typical strength |
0.1% |
| Drug class |
Topical corticosteroid |
| Relative potency |
High potency |
| Dosage forms |
Cream, ointment, lotion |
| Historical brand |
Cyclocort |
| Primary use |
Inflammatory and pruritic dermatoses |
| Prescription status |
Prescription topical drug |
| Biologic status |
Not applicable |
| Current commercial structure |
Generic and legacy-brand market |
| Main competitive factors |
Price, availability, formulation, pharmacy substitution |
What is the FDA regulatory status of amcinonide?
Amcinonide is an FDA-approved prescription topical corticosteroid. The historical Cyclocort product was approved under a new drug application, while later generic products entered through abbreviated new drug applications or other approved pathways applicable to topical products.
FDA product databases distinguish between marketing status and safety status. A product may be listed as discontinued without an FDA determination that it was withdrawn for safety or effectiveness reasons. That distinction matters for amcinonide because the original brand has had limited commercial visibility while generic versions continue to determine market access (FDA, 2024a).
Amcinonide does not have FDA biologic-license status. Biosimilar substitution rules therefore do not apply. Competitive entry occurs through generic topical products rather than biosimilar applications.
FDA regulatory factors affecting sales
The principal regulatory issues are:
- Approval of generic formulations that demonstrate pharmaceutical equivalence and acceptable quality.
- Manufacturing compliance for semisolid topical products.
- Labeling consistency across cream, ointment, and lotion products.
- Control of microbial quality, viscosity, particle distribution, and content uniformity.
- Restrictions on prolonged use, large-area application, occlusion, and pediatric exposure.
Topical products can face manufacturing and bioequivalence issues that are more complex than those for simple oral tablets. Product performance depends on vehicle composition, emulsion structure, particle size, rheology, and release characteristics. These factors create some technical barriers but do not restore market exclusivity.
When did amcinonide lose exclusivity?
Amcinonide lost meaningful market exclusivity decades ago. The original Cyclocort product was approved in the late 1970s, placing any original regulatory exclusivity and core composition-of-matter protection well outside the current commercial period. The current market is therefore genericized.
No current commercial thesis depends on Hatch-Waxman exclusivity for amcinonide. The relevant commercial question is whether a manufacturer can maintain supply, secure reimbursement, and differentiate a formulation sufficiently to support pricing.
Amcinonide exclusivity timeline
| Period |
Commercial event |
Market effect |
| Late 1970s |
Original amcinonide approval and Cyclocort commercialization |
Protected branded product enters market |
| 1980s-1990s |
Core patent and regulatory exclusivity periods expire |
Generic competition becomes possible |
| 2000s |
Generic topical products expand |
Brand pricing power declines |
| 2010s |
Product becomes a mature generic dermatology therapy |
Supply and reimbursement become primary drivers |
| 2020s |
No material branded exclusivity remains |
Market operates as a low-growth generic segment |
Public FDA materials do not identify an active exclusivity period for amcinonide. The product should be treated as fully mature from a patent and regulatory exclusivity perspective (FDA, 2024b).
What patents protect amcinonide?
The original active ingredient and historical brand franchise are no longer protected by commercially relevant basic patents. Any current patent value would have to come from a specific formulation, delivery system, manufacturing process, or method of use.
No material current patent estate is publicly associated with amcinonide that would support branded market exclusivity. Patent risk is therefore low at the active-ingredient level and more relevant to formulation-specific entry disputes.
Patent categories relevant to amcinonide
| Patent category |
Current commercial significance |
| Composition-of-matter patent |
Expired or commercially irrelevant |
| Basic topical formulation patent |
Generally expired or unavailable as a market barrier |
| Cream, ointment, or lotion formulation |
Could protect a narrow product design if valid and unexpired |
| Manufacturing process |
May create operational know-how but rarely blocks all generic entry |
| Method-of-use patent |
Limited value unless tied to a new indication or dosing regimen |
| Device or delivery patent |
Low relevance for conventional amcinonide products |
| Orange Book-listed patent |
No material current patent barrier identified in public FDA product materials |
What is the Orange Book status of amcinonide?
Amcinonide has no meaningful Orange Book patent barrier for current generic competition. The Orange Book is relevant because it lists approved products, therapeutic equivalence information, patents, and exclusivity where applicable. For an old topical corticosteroid, the absence of active listed patents means an ANDA applicant generally does not face a patent certification issue comparable to a recently approved branded drug (FDA, 2024b).
A Paragraph IV challenge is therefore unlikely to be the central market event for amcinonide. Generic competition has already occurred. Any new entrant would more likely proceed through routine generic approval and commercial launch than through litigation designed to invalidate an active branded patent.
Are there Paragraph IV challenges involving amcinonide?
No major publicly visible Paragraph IV litigation defines the current amcinonide market. The drug's competitive structure predates the period in which a current Paragraph IV filing would materially alter market access.
A Paragraph IV certification could theoretically arise if an applicant were addressing a newly listed formulation patent. That scenario would require a specific active patent listing and a commercially significant reference product. Neither condition currently defines the standard amcinonide market.
How many companies manufacture or market amcinonide?
The market has historically included the original brand owner and multiple generic manufacturers. Manufacturer participation can change over time because generic companies add or discontinue low-volume topical products based on supply economics, contract manufacturing capacity, and reimbursement.
Known market participants have included manufacturers and labelers associated with generic dermatology portfolios. Public databases may show different entities for the applicant, manufacturer, repackager, and distributor. Those roles should not be treated as equivalent.
Competitive landscape
| Competitive group |
Position in the market |
| Legacy Cyclocort brand |
Historical reference product; limited current strategic importance |
| Generic amcinonide suppliers |
Compete primarily on price, availability, and formulation |
| Other high-potency topical steroids |
Main therapeutic substitutes |
| Mid-potency corticosteroids |
Substitute for less severe disease or sensitive sites |
| Nonsteroidal topical agents |
Compete in steroid-sparing treatment settings |
| Specialty dermatology brands |
Compete where reimbursement supports premium pricing |
The most important competitors are not necessarily other amcinonide products. Physicians can substitute among topical corticosteroids based on potency, site of application, vehicle, patient age, disease severity, insurance coverage, and formulary status.
Relevant alternatives include fluocinonide, betamethasone dipropionate, clobetasol propionate, triamcinolone acetonide, hydrocortisone formulations, tacrolimus ointment, pimecrolimus cream, and newer nonsteroidal agents such as roflumilast and ruxolitinib products. These therapies do not have identical potency or indications, but they compete for dermatology prescribing and payer budgets.
What formulations are protected by amcinonide patents?
No current formulation protection appears to create broad market exclusivity for conventional amcinonide cream, ointment, or lotion products. Formulation economics nevertheless remain important.
Cream
Creams are commonly preferred for areas where cosmetic acceptability and spreadability matter. Their commercial success depends on emulsion stability, absorption, feel, packaging, and shelf life. A cream may be pharmaceutically equivalent to another cream while differing in patient preference and manufacturing cost.
Ointment
Ointments provide occlusive delivery and are often used for dry or thickened lesions. Their main commercial limitations are greasiness, patient adherence, and packaging. Manufacturing requires control of uniformity and physical stability.
Lotion
Lotions may have advantages for hairy or larger body areas. The formulation can be more sensitive to viscosity, phase separation, microbial control, and container compatibility.
These characteristics can support modest product differentiation, but they do not usually produce durable pricing power in the absence of a patented delivery technology or strong physician brand preference.
What is the financial trajectory for amcinonide?
Amcinonide has a mature, low-growth financial profile. Public companies generally do not report amcinonide revenue as a separate line item. Sales are usually aggregated within broader generic pharmaceutical or dermatology portfolios.
Revenue profile
The product's revenue trajectory has likely followed this pattern:
- Initial branded revenue during the Cyclocort period.
- Declining brand share after generic entry.
- Lower average selling prices as multiple suppliers entered.
- Stabilization as a low-cost prescription product.
- Periodic revenue volatility from shortages, supplier exits, reimbursement changes, and wholesaler inventory.
The absence of standalone public revenue reporting prevents a reliable company-level sales forecast based solely on publicly disclosed financial statements. The commercial value of amcinonide is better assessed through prescription volume, product availability, market share by dosage form, and gross margin than through brand revenue.
Financial drivers
| Driver |
Effect on amcinonide economics |
| Generic substitution |
Reduces net price |
| Number of active suppliers |
More suppliers usually increase price pressure |
| Product shortages |
Can temporarily improve pricing and volume for remaining suppliers |
| Formulation mix |
Ointment, cream, and lotion may have different margins |
| Pharmacy benefit design |
Determines substitution and reimbursement |
| Manufacturing scale |
Low-volume production can raise unit cost |
| API supply |
Interruptions can reduce market availability |
| Contract manufacturing |
Can lower fixed-cost exposure |
| Repackaging |
Expands distribution but adds channel margin pressure |
| Dermatology demand |
Supports stable but generally mature utilization |
How strong is the amcinonide commercial franchise?
The franchise is weak as a branded asset but potentially useful as a portfolio product for a generic manufacturer with existing dermatology infrastructure.
Strengths
- Established clinical history.
- Familiarity among dermatology prescribers.
- Multiple dosage forms.
- Low regulatory novelty risk.
- Potential inclusion in generic dermatology portfolios.
- Demand supported by chronic inflammatory skin conditions.
Weaknesses
- No material exclusivity.
- Limited brand differentiation.
- Low pricing power.
- Substitution by other topical corticosteroids.
- Limited standalone revenue visibility.
- Potentially modest market size.
- Manufacturing complexity for semisolid products.
- Dependence on payer and pharmacy reimbursement.
The strongest strategic rationale for amcinonide is portfolio completeness rather than high growth. A manufacturer already producing topical corticosteroids may gain incremental value from offering amcinonide, particularly if it can reliably supply less crowded dosage forms.
What generic launch scenarios exist for amcinonide?
A new generic entrant would face a mature market rather than a first-entry opportunity. The likely launch scenarios are:
Low-price volume entry
The manufacturer launches a standard cream or ointment at a competitive price and seeks formulary and wholesaler access. This strategy requires efficient manufacturing and reliable supply because product differentiation is limited.
Formulation-led entry
The manufacturer emphasizes a specific dosage form, packaging format, vehicle characteristic, or patient-use advantage. This may improve commercial positioning but is unlikely to support premium pricing without clinical or payer recognition.
Shortage-driven entry
A supplier enters or expands during a period of market shortage. The opportunity can produce temporary volume and pricing benefits, but those gains may reverse when additional suppliers restore availability.
Portfolio bundling
A generic company markets amcinonide alongside other topical corticosteroids and dermatology products. This approach can improve sales-force efficiency and pharmacy contracting.
Repackaged or channel-specific entry
A distributor or repackager targets institutional, specialty pharmacy, or government channels. Margin depends on purchasing terms and supply contracts rather than patent protection.
What manufacturing and intellectual-property barriers affect amcinonide?
The main barriers are technical and operational, not patent-based.
Topical semisolid manufacturing requires control of:
- Active ingredient dispersion.
- Emulsion or ointment structure.
- Viscosity and rheology.
- Content uniformity.
- Microbial limits.
- Preservative performance.
- Stability under storage conditions.
- Tube, pump, or bottle compatibility.
- In vitro release and permeation characteristics.
FDA guidance for topical products recognizes that formulation and process differences can affect product performance and may require comparative testing beyond simple chemical sameness (FDA, 2022).
API supply is another consideration. Amcinonide is an older, lower-volume active ingredient. A limited number of qualified API suppliers can create procurement concentration. That risk may affect inventory requirements and working capital more than it affects long-term market exclusivity.
What patent litigation affects amcinonide?
No major active patent litigation appears to define the current amcinonide market. The litigation profile is materially lower than for new dermatology drugs with active composition, formulation, or method-of-use patents.
Potential disputes would more likely involve:
- ANDA approval or labeling.
- Formulation equivalence.
- Trademark or trade dress associated with a legacy brand.
- Manufacturing quality.
- Supply agreements.
- Product liability.
- False or comparative marketing claims.
A patent litigation strategy would have limited commercial value unless a party held a valid, unexpired patent covering a specific high-value formulation. Conventional amcinonide products do not present that profile.
How does amcinonide compare with competing topical corticosteroids?
| Drug |
Relative market position |
Commercial differentiation |
| Amcinonide 0.1% |
Mature high-potency generic |
Limited |
| Clobetasol propionate |
Very high-potency benchmark with broad generic presence |
Stronger prescribing familiarity |
| Betamethasone dipropionate |
High-potency alternative with multiple vehicles |
Formulation variety |
| Fluocinonide |
High-potency generic competitor |
Broad dermatology use |
| Triamcinolone acetonide |
Mid-potency, high-volume generic |
Lower potency and broader routine use |
| Hydrocortisone |
Low-potency, broad consumer and prescription use |
Established accessibility |
| Tacrolimus |
Nonsteroidal prescription alternative |
Steroid-sparing positioning |
| Roflumilast |
Newer nonsteroidal option |
Branded innovation and indication expansion |
| Ruxolitinib cream |
Branded nonsteroidal therapy |
Premium pricing and novel mechanism |
Amcinonide is most exposed to generic high-potency corticosteroids, especially products that are cheaper, more available, or more familiar to prescribers. It is less directly exposed to branded nonsteroidal products when clinicians specifically seek steroid-sparing treatment.
What geographic markets matter for amcinonide?
The United States remains the most relevant market for Orange Book, ANDA, reimbursement, and prescription economics. International markets may use different brand names, regulatory classifications, strengths, and formulary systems.
Geographic commercial value depends on:
- Local approval status.
- Prescription versus over-the-counter classification.
- Generic substitution rules.
- Dermatology reimbursement.
- Availability of local manufacturers.
- Import requirements for API and finished product.
- National tender pricing.
- Pharmacovigilance obligations.
In markets with centralized procurement, amcinonide may be a tender product with limited margin. In fragmented retail markets, pharmacy availability and physician familiarity may carry more weight.
What revenue exposure does amcinonide create for pharmaceutical companies?
For diversified generic manufacturers, amcinonide is unlikely to represent a material company-wide revenue driver. Exposure is more relevant at the product-family level.
A manufacturer faces higher exposure when:
- It is one of few active suppliers.
- It relies on a single API source.
- It sells a single dosage form.
- Its product is concentrated in one payer channel.
- It has limited dermatology portfolio breadth.
- The product has recurring manufacturing deviations or shortages.
The financial downside of losing amcinonide is usually limited for a diversified company. The operational downside can be greater if the product is part of a broader dermatology contract or if its discontinuation reduces portfolio access to pharmacies and wholesalers.
Key Takeaways
- Amcinonide is a mature, off-patent topical corticosteroid marketed historically as Cyclocort.
- The product has no meaningful current exclusivity or broad Orange Book patent barrier.
- Paragraph IV litigation and biosimilar competition are not central risks.
- Commercial competition comes from generic amcinonide suppliers and other topical corticosteroids.
- Public companies generally do not disclose standalone amcinonide revenue.
- Financial performance depends on price, supply reliability, formulation mix, reimbursement, and generic competition.
- Cream, ointment, and lotion manufacturing creates technical barriers but not broad market protection.
- The product is more valuable as part of a generic dermatology portfolio than as an independent branded franchise.
- Generic launch opportunities are primarily volume-, supply-, and channel-driven.
- The market has low growth potential but can produce stable revenue where supply is disciplined and manufacturing costs are controlled.
FAQs
Is amcinonide still available in the United States?
Generic amcinonide products have been marketed in the United States, although availability can vary by dosage form, supplier, pharmacy inventory, and product status in FDA databases.
Is Cyclocort still a commercially important brand?
No. Cyclocort is a legacy brand, while generic amcinonide products determine most current market economics.
Does amcinonide have a biosimilar competitor?
No. Amcinonide is a conventional small-molecule topical drug, so competition occurs through generic products rather than biosimilars.
Can a company obtain new exclusivity for an amcinonide formulation?
A company could pursue protection for a genuinely novel formulation, delivery system, or use if it satisfies patentability and regulatory requirements. Such protection would be narrow and would not restore exclusivity to conventional amcinonide cream, ointment, or lotion products.
Is amcinonide a high-value licensing opportunity?
Usually not as a standalone asset. Its licensing value is more plausible within a broader dermatology portfolio, a contract manufacturing arrangement, or a regional distribution transaction focused on reliable generic supply.
References
-
U.S. Food and Drug Administration. (2019). Amcinonide cream, ointment, and lotion prescribing information. FDA.
-
U.S. Food and Drug Administration. (2022). A draft guidance for industry: In vitro release test studies for topical drug products submitted in ANDAs. FDA.
-
U.S. Food and Drug Administration. (2024a). Drugs@FDA: FDA-approved drugs database. FDA.
-
U.S. Food and Drug Administration. (2024b). Approved drug products with therapeutic equivalence evaluations, 44th edition. FDA.
-
National Library of Medicine. (2024). DailyMed: Amcinonide topical product labeling. U.S. National Library of Medicine.