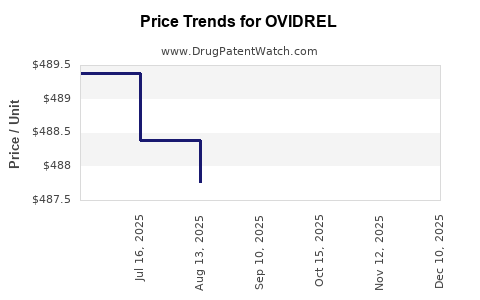
Last updated: September 8, 2026
Ovidrel is a mature recombinant human chorionic gonadotropin product used to trigger ovulation in assisted reproductive technology. Its commercial position depends more on fertility-cycle volumes, physician protocols, pharmacy access and supply reliability than on remaining exclusivity. Merck KGaA and its U.S. affiliate EMD Serono do not separately disclose Ovidrel revenue, preventing a defensible brand-level sales forecast. The product has limited visible patent protection, no material biosimilar competition, and increasing substitution risk from urinary hCG products and future recombinant or long-acting ovulation-trigger products.
What is Ovidrel and how is it used?
Ovidrel contains choriogonadotropin alfa, a recombinant form of human chorionic gonadotropin. The U.S. product is supplied as a single-use prefilled syringe containing 250 micrograms, equivalent to approximately 6,500 international units of hCG. It is administered subcutaneously after ovarian stimulation to induce final follicular maturation and ovulation.
The product is used in:
- Ovulation induction in patients undergoing fertility treatment.
- Timed intercourse protocols.
- Intrauterine insemination cycles.
- In vitro fertilization and related assisted reproductive procedures.
Ovidrel is marketed by EMD Serono in the United States and by Merck KGaA or regional affiliates in international markets. The product is distinct from urinary-derived hCG products such as Pregnyl and Novarel.
What is the FDA regulatory status of Ovidrel?
Ovidrel received U.S. Food and Drug Administration approval in 2000. The U.S. product is regulated under an NDA rather than through the modern biosimilar reference-product framework used for many newer therapeutic biologics. Its approval predates the commercial development of the current biosimilar pathway under the Biologics Price Competition and Innovation Act.
The approved use is to induce ovulation and pregnancy in infertile women whose infertility is attributable to anovulation and who have been appropriately pretreated with follicle-stimulating hormone. The label contains warnings concerning ovarian hyperstimulation syndrome, multiple gestation and thromboembolic events. [1]
Ovidrel is also authorized in Europe and other markets for ovulation induction and assisted reproduction. Its European regulatory history supports broad international recognition, but commercial access and reimbursement vary by country. [2]
When does Ovidrel lose exclusivity?
Ovidrel's core commercial exclusivity has already expired in the United States and major international markets.
The relevant exclusivity profile is:
| Protection category |
Ovidrel position |
| U.S. approval |
2000 |
| U.S. new chemical entity exclusivity |
Historical period expired |
| U.S. biologic reference-product exclusivity |
Not a meaningful current barrier because approval predates the modern 12-year framework |
| Core composition and recombinant-production patents |
No longer considered a material commercial barrier |
| Orange Book patent protection |
No currently material, publicly identifiable patent barrier tied to the core product |
| Biosimilar competition |
No widely marketed FDA-approved biosimilar publicly associated with Ovidrel |
| Generic or alternative hCG competition |
Present through urinary-derived hCG products and other fertility medicines |
The absence of active core exclusivity does not mean immediate generic erosion. Ovidrel is a recombinant glycoprotein with a complex manufacturing process, glycosylation profile and biological activity assay. A competing product must establish adequate quality, potency, safety and clinical comparability under the applicable FDA pathway.
What is the Orange Book status of Ovidrel?
Ovidrel's commercial protection does not appear to depend on a current, enforceable Orange Book patent estate. The product's value is therefore based on brand recognition, established physician use, supply-chain execution and the technical difficulty of reproducing recombinant hCG.
An Orange Book listing would be relevant to an abbreviated new drug application and any Paragraph IV certification. Publicly visible information does not indicate an active, high-value Ovidrel patent litigation program comparable with the litigation surrounding major oncology, immunology or diabetes biologics. [3]
How many patents cover Ovidrel?
The number of historical patents associated with recombinant hCG technology is less important than whether any unexpired patent blocks commercial competition. Ovidrel's original protection involved recombinant production, protein expression and fertility-use technology. Those rights are old relative to the product's 2000 approval and are unlikely to provide a durable barrier today.
The practical patent assessment is:
| Patent issue |
Commercial assessment |
| Active-ingredient protection |
Expired or commercially weak |
| Recombinant-production patents |
Primarily historical |
| Formulation patents |
No widely recognized blocking estate |
| Method-of-use patents |
Limited relevance because ovulation-trigger use is established and broadly known |
| Manufacturing know-how |
More important than patent term |
| Trade secrets |
Potentially relevant to cell culture, purification and analytical controls |
The principal residual barrier is manufacturing capability. Recombinant hCG must be produced with consistent molecular structure, glycosylation, purity, potency and stability. A competitor may face development costs even when the patent estate is weak.
What formulations are protected by Ovidrel?
Ovidrel's commercial differentiation is tied to its prefilled, subcutaneous delivery format and recombinant active ingredient. The presentation reduces the handling burden associated with reconstituted urinary hCG products.
Key product characteristics include:
- Single-use prefilled syringe.
- Subcutaneous administration.
- 250-microgram dose.
- Refrigerated storage requirements.
- Recombinant choriogonadotropin alfa.
- Use after follicle stimulation with gonadotropins.
The formulation itself is unlikely to support a meaningful long-term monopoly. Prefilled delivery is commercially useful but technically reproducible. Competitive advantage depends on device reliability, cold-chain execution, pharmacy availability and prescriber familiarity.
What is the competitive landscape for Ovidrel?
Ovidrel competes within a broader fertility-drug basket rather than in a standalone hCG market. The economic decision is made at the level of a treatment cycle.
Direct hCG competitors
The principal direct competitors are urinary-derived hCG products, including:
- Pregnyl, marketed by Organon in the United States.
- Novarel, historically associated with Ferring and other distributors.
- Other human chorionic gonadotropin products supplied through fertility pharmacies and compounding channels.
Urinary hCG products can be less convenient because they may require vial reconstitution and intramuscular administration. They can still compete effectively when price, insurance coverage or supply availability is more important than convenience.
Indirect fertility competitors
Ovidrel also competes indirectly with changes in ovarian stimulation protocols. Relevant products include:
- Follitropin alfa and follitropin beta.
- Menotropins.
- Urofollitropin.
- Gonadotropin-releasing hormone agonists and antagonists used in IVF protocols.
- Emerging oral ovarian stimulation products.
- Alternative ovulation-trigger protocols using GnRH agonists in selected IVF patients.
The product is therefore exposed to treatment-protocol substitution even when no direct hCG competitor gains market share.
How does Ovidrel compare with urinary hCG?
| Attribute |
Ovidrel |
Urinary hCG products |
| Source |
Recombinant |
Extracted from human urine |
| Administration |
Subcutaneous |
Often intramuscular or reconstituted injection |
| Presentation |
Prefilled syringe |
Vial and diluent in many products |
| Dose standardization |
High |
Product-dependent |
| Patient convenience |
Generally higher |
Generally lower |
| Price position |
Often premium |
May be lower or variable |
| Supply risk |
Dependent on recombinant manufacturing |
Dependent on urine collection and purification |
| Regulatory substitution |
Complex biologic comparability |
Established legacy products |
What is Ovidrel's financial trajectory?
Merck KGaA does not publicly report Ovidrel as a separate revenue line. The product is included within a broader healthcare or fertility portfolio, so brand-level revenue, gross margin and operating profit cannot be calculated from company filings.
The financial trajectory is best characterized as mature and defensive rather than high-growth:
- Launch and adoption phase: Ovidrel gained acceptance by offering recombinant consistency and a convenient prefilled injection for fertility treatment.
- Maturity phase: Revenue became tied to assisted-reproduction volumes, fertility-clinic activity and reimbursement.
- Late-life phase: Growth is constrained by expired exclusivity, therapeutic substitution and the lack of a new indication platform.
- Current commercial phase: Cash generation likely depends on repeat use, brand retention and reliable supply rather than price expansion.
Merck's fertility business benefits from recurring treatment cycles. A patient may use Ovidrel once per cycle, but the number of cycles varies by age, diagnosis, treatment pathway and payer coverage. This creates volume sensitivity to:
- IVF and intrauterine insemination procedure growth.
- Fertility clinic capacity.
- Delayed childbearing.
- Insurance mandates and reimbursement.
- Out-of-pocket treatment costs.
- Regional fertility-treatment penetration.
- Drug shortages affecting competing hCG products.
The product's financial exposure is likely modest relative to Merck KGaA's largest pharmaceutical brands. A decline in Ovidrel sales would not materially alter group-level results, but it could matter to the profitability and strategic value of the company's reproductive-health portfolio.
What market forces will drive Ovidrel sales?
Assisted reproduction demand
The strongest structural driver is the expansion of fertility treatment. The United States and Europe have experienced sustained demand for IVF, intrauterine insemination and ovulation induction. The Centers for Disease Control and Prevention reports annual growth in assisted reproductive technology utilization over long periods, although individual years vary by economic conditions and clinic capacity. [4]
Reimbursement and patient affordability
Ovidrel is vulnerable to payer-driven substitution because the product is an established trigger medicine with alternatives. Where insurance covers the full cycle, convenience and physician preference support the brand. Where patients pay directly, lower-cost urinary hCG products gain leverage.
Drug supply
Fertility drugs have experienced periodic shortages and distribution interruptions. A reliable Ovidrel supply can increase share during competitor shortages. The reverse is also true: a manufacturing or distribution disruption can quickly shift prescriptions to alternatives because treatment cycles are time-sensitive.
Pharmacy and clinic purchasing
Specialty pharmacies, fertility clinics and group purchasing arrangements influence net price. Discounting can be more important than list price, particularly where Ovidrel competes with lower-priced hCG products.
Protocol innovation
Changes in IVF protocols can affect hCG utilization. Some clinics use GnRH agonist triggers in patients at elevated risk of ovarian hyperstimulation syndrome. That approach can reduce reliance on hCG in selected patients, although hCG remains widely used in other protocols.
Which companies are challenging Ovidrel?
No major, widely commercialized FDA-approved biosimilar to Ovidrel is publicly established as a direct competitor. Competitive pressure comes primarily from manufacturers and suppliers of urinary hCG and from companies selling other fertility drugs.
The relevant competitive groups are:
- Merck KGaA and EMD Serono, as Ovidrel's commercial sponsor.
- Organon, through Pregnyl and its fertility portfolio.
- Ferring Pharmaceuticals, through reproductive-health products and historical hCG competition.
- Generic and specialty fertility-drug manufacturers.
- Compounding pharmacies, where legally permitted and clinically accepted.
- Manufacturers of gonadotropins and alternative ovulation-trigger products.
A future recombinant hCG entrant would need to prove product quality and biological comparability while securing distribution through fertility pharmacies and clinics. Patent litigation would be less likely to determine market entry than regulatory approval, manufacturing validation and payer access.
What patent litigation or settlement agreements affect Ovidrel?
No major publicly prominent Paragraph IV litigation or settlement agreement appears to define the current Ovidrel market. The absence of litigation is consistent with a mature product whose core patent protection is no longer the primary commercial issue.
The principal legal risks are more likely to involve:
- Patent disputes over a new recombinant hCG formulation.
- Manufacturing-process patents asserted against an entrant.
- Regulatory disputes concerning reference-product status.
- Trade-secret claims involving cell lines, purification or analytical methods.
- Distribution and supply agreements.
The lack of a visible litigation record reduces legal uncertainty for competitors but does not eliminate development risk.
What generic entry risks exist for Ovidrel?
Generic entry risk is moderate over the long term and limited in the immediate term.
A conventional small-molecule ANDA model is unlikely to be sufficient for a fully equivalent recombinant glycoprotein product. A challenger may need to use a biologic or hybrid regulatory route, depending on FDA classification and product characteristics. The development program would require:
- Recombinant cell-line development.
- Structural and glycosylation characterization.
- Potency and receptor-binding assays.
- Stability studies.
- Comparative clinical or pharmacodynamic evidence.
- Validated manufacturing controls.
- Commercial-scale supply capacity.
The likely entry sequence is gradual rather than abrupt. A competing product could first gain share through selected fertility pharmacies, lower pricing or regional distribution, then expand if physicians accept its clinical and operational profile.
How strong is the Ovidrel patent estate?
Ovidrel's patent estate is weak as a current exclusivity barrier but remains supported by manufacturing complexity and brand equity.
| Factor |
Strength |
| Core patent protection |
Low |
| Regulatory exclusivity |
Low |
| Biosimilar competition today |
Low |
| Manufacturing barrier |
Moderate to high |
| Brand and physician familiarity |
Moderate |
| Patient convenience |
Moderate |
| Payer protection |
Low to moderate |
| Litigation protection |
Low |
| Supply-chain value |
Moderate |
The product is therefore a classic mature biologic-adjacent asset: legally exposed but operationally resilient.
What are the geographic market dynamics for Ovidrel?
The United States remains commercially important because fertility treatment prices and procedure volumes are high, but access is highly dependent on insurance coverage and state mandates. Europe has broad regulatory access but greater price controls and tender pressure. Emerging fertility markets may grow faster but generally have lower per-cycle spending and more uneven reimbursement.
Geographic performance depends on:
- National IVF reimbursement.
- Local fertility-clinic density.
- Availability of specialty pharmacies.
- Public or private coverage of fertility medicines.
- Pricing controls.
- Cold-chain infrastructure.
- Physician adoption of recombinant versus urinary hCG.
Ovidrel's prefilled presentation has greater value in markets where patients self-administer treatment and convenience is reimbursed or affordable.
Key Takeaways
- Ovidrel is a mature recombinant hCG product used to trigger ovulation in assisted reproduction.
- Its U.S. approval dates to 2000, and core exclusivity has expired.
- No major active patent estate or prominent Paragraph IV litigation currently defines the market.
- No widely marketed FDA-approved biosimilar is publicly established as a direct Ovidrel competitor.
- The main alternatives are Pregnyl, Novarel and other urinary hCG products, plus protocol-level substitutes.
- Merck KGaA does not separately disclose Ovidrel revenue, so brand-level financial forecasting is not supportable from public filings.
- Revenue is driven by fertility-cycle volume, reimbursement, clinic utilization, supply reliability and patient affordability.
- Manufacturing complexity provides a stronger remaining barrier than patent protection.
- Ovidrel is likely to remain a stable, mature product unless a lower-cost recombinant competitor or a materially different ovulation-trigger protocol gains broad adoption.
FAQs
Is Ovidrel a biosimilar?
No. Ovidrel is the original branded recombinant choriogonadotropin alfa product in its relevant markets. It is not marketed as a biosimilar to another hCG reference product.
Does Ovidrel have a patent-protected monopoly?
No material current monopoly is evident from its historical approval and patent profile. Any remaining protection is more likely to involve manufacturing know-how or limited formulation rights than a blocking core patent.
Can a generic company make Ovidrel?
A competitor may develop a comparable recombinant hCG product, but the regulatory and manufacturing pathway is more complex than a conventional small-molecule generic application. Product characterization, potency, glycosylation and clinical comparability are central requirements.
Does insurance usually cover Ovidrel?
Coverage varies substantially by country, payer, state and fertility benefit design. Ovidrel may be covered as part of infertility treatment, but many patients face significant out-of-pocket costs and may be directed toward lower-cost alternatives.
Is Ovidrel financially important to Merck KGaA?
Ovidrel is commercially relevant within reproductive health, but Merck KGaA does not report it as a standalone revenue category. Its financial contribution is therefore not separately quantifiable from public company disclosures.
References
-
U.S. Food and Drug Administration. (2000). Ovidrel: Choriogonadotropin alfa prescribing information. FDA.
-
European Medicines Agency. (2001). Ovitrelle: EPAR product information. EMA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. FDA.
-
Centers for Disease Control and Prevention. (2023). 2021 assisted reproductive technology fertility clinic and national summary report. U.S. Department of Health and Human Services.
-
Merck KGaA. (2023). Annual report 2023. Merck KGaA.