Last updated: October 25, 2026
Vistogard, the brand name for uridine triacetate, occupies a narrow but defensible pharmaceutical market: emergency rescue after fluorouracil or capecitabine overdose and treatment of early-onset severe or life-threatening fluoropyrimidine toxicity. FDA approval, orphan-drug status, hospital stocking requirements, and the absence of an established direct substitute support pricing power. Market growth is constrained by low event frequency, specialist prescribing, generic fluoropyrimidine use, and limited public disclosure of product sales.
What is Vistogard and what clinical problem does it address?
Vistogard is an oral antidote that supplies uridine, which competes with toxic fluorouracil metabolites and reduces cellular injury. It is approved for adults and pediatric patients who:
- Have received an overdose of fluorouracil or capecitabine, whether accidental or intentional.
- Develop early-onset, severe or life-threatening toxicity within 96 hours of fluorouracil or capecitabine administration.
The product is administered as granules mixed with soft food or liquid. The recommended adult and pediatric dose is 10 grams orally every six hours for 20 doses over five days. The product is not approved for routine prevention of chemotherapy toxicity or for delayed toxicity appearing more than 96 hours after treatment.[1]
Vistogard addresses a high-severity, low-frequency event. This creates a market with high willingness to pay per treated patient but limited volume.
What is Vistogard’s FDA regulatory status?
| Regulatory item |
Status |
| Active ingredient |
Uridine triacetate |
| Brand |
Vistogard |
| Sponsor |
Wellstat Therapeutics Corporation |
| FDA application |
NDA 208306 |
| Approval date |
October 11, 2015 |
| Dosage form |
Oral granules |
| Primary use |
Fluorouracil or capecitabine overdose and early severe toxicity |
| Regulatory pathway |
New drug application |
| Orphan-drug relevance |
The product was developed for a rare, high-mortality toxicity setting |
| Biosimilar pathway |
Not applicable |
| Generic pathway |
Potentially applicable through an ANDA, subject to current regulatory and patent conditions |
FDA approval relied on open-label clinical studies rather than a conventional randomized efficacy trial. In the overdose population, survival was approximately 96%. In patients treated for early-onset severe or life-threatening toxicity, survival was approximately 89%.[1,2]
The evidence base is commercially useful because the clinical setting makes placebo-controlled trials difficult to conduct. The same feature limits conventional market expansion: the product is used when a rare emergency occurs, not as part of every chemotherapy cycle.
How large is the Vistogard market?
The addressable market is determined by four variables:
- The number of patients receiving fluorouracil or capecitabine.
- The incidence of overdose and severe early toxicity.
- Recognition and diagnosis within the 96-hour treatment window.
- Hospital and oncology-center willingness to stock the product.
Fluorouracil and capecitabine are widely used in colorectal, breast, gastric, pancreatic, head and neck, and other cancers. Their broad use creates a large exposure base. Vistogard, however, treats an uncommon adverse event rather than the underlying cancer population.
Market drivers
- Continued use of fluorouracil and capecitabine across solid tumors.
- Greater awareness of dihydropyrimidine dehydrogenase deficiency and fluoropyrimidine toxicity.
- Hospital risk-management policies requiring access to emergency antidotes.
- Use in pediatric oncology and outpatient chemotherapy networks.
- Potential demand following compounding, dosing, pump-programming, or prescribing errors.
- Clinical preference for an FDA-approved antidote over unapproved uridine products.
Market constraints
- Low annual treatment volume.
- Product expiration risk for hospitals that stock emergency doses.
- Need for rapid diagnosis and administration.
- Reimbursement friction in emergency treatment settings.
- Competition from treatment interruption, supportive care, hydration, intensive care, and other off-label interventions.
- Limited repeat use per patient.
Vistogard’s economics are therefore closer to an emergency hospital product than to a chronic oncology medicine. Revenue depends on distribution breadth, formulary adoption, awareness, and reimbursement execution as much as on the number of fluoropyrimidine-treated patients.
What is the financial trajectory of Vistogard?
Publicly available information does not provide a reliable, standalone Vistogard revenue series. Wellstat Therapeutics is a private company, and its financial disclosures do not provide the level of product-specific reporting available from public pharmaceutical companies.
The commercial trajectory can be divided into four phases:
| Period |
Commercial phase |
Market characteristics |
| 2015-2017 |
Launch and clinical adoption |
Establishment of hospital accounts, emergency protocols, and oncology awareness |
| 2018-2020 |
Access and distribution development |
Expansion of institutional stocking and payer coverage; private-company financial visibility remained limited |
| 2021-2023 |
Defensive specialty commercialization |
Demand linked to fluoropyrimidine use, toxicity recognition, and hospital purchasing discipline |
| 2024 onward |
Mature orphan rescue market |
Growth depends on penetration, price realization, stocking compliance, and generic or patent-entry risk |
The product can generate substantial revenue per treated patient without reaching blockbuster volume. Its financial profile is likely characterized by:
- High gross margin potential for an oral specialty product.
- High selling price relative to manufacturing cost.
- Significant commercial value from hospital stocking.
- Uneven quarterly demand because use is event-driven.
- Working-capital costs from inventory expiration and emergency distribution.
- Concentrated dependence on oncology prescribers, hospitals, and specialty pharmacies.
A top-line forecast based only on the number of fluoropyrimidine prescriptions would materially overstate the market. The relevant denominator is the number of eligible toxicity or overdose events treated within 96 hours.
When did Vistogard lose regulatory exclusivity?
Vistogard received FDA approval in 2015. Orphan-drug exclusivity, if applied to the approved indication, generally provides seven years of protection from approval against approval of the same drug for the same use. That period would have reached its nominal endpoint in October 2022.
Regulatory exclusivity does not prevent all forms of competition. It does not block:
- A different drug with a different active ingredient.
- A product approved for a different use.
- Certain abbreviated applications after applicable exclusivity expires.
- Patent challenges.
- Off-label use of other uridine-containing products.
The end of orphan exclusivity did not automatically eliminate Vistogard’s commercial protection. Patent term, Orange Book listings, formulation claims, manufacturing know-how, distribution arrangements, and physician adoption can continue to affect entry.
What patents protect Vistogard?
Vistogard’s relevant intellectual-property protection is expected to center on uridine triacetate compositions, oral formulations, dosing regimens, and methods of treating fluoropyrimidine toxicity. The commercial product’s protection should be evaluated across four categories:
Composition patents
These may cover uridine triacetate itself, crystalline forms, purity parameters, or pharmaceutical compositions containing the active ingredient. Composition claims are generally more valuable than narrow process claims because they can reach competing products regardless of manufacturing method.
Formulation patents
The product is supplied as oral granules. Formulation claims may address particle size, excipients, stability, taste, packaging, reconstitution, or delivery characteristics. Formulation patents can delay a directly substitutable generic even if the active ingredient is no longer broadly protected.
Method-of-use patents
Vistogard’s labeled use is treatment after fluorouracil or capecitabine overdose or early severe toxicity. Method claims may cover timing, dosing, patient selection, or treatment of a defined toxicity population. These claims are commercially relevant because the market is indication-specific.
Manufacturing and trade-secret protection
Manufacturing controls, raw-material specifications, granulation, stability, analytical methods, and supply arrangements may create barriers that are not visible in the Orange Book. These barriers matter more in a low-volume product because a generic entrant must validate economics at modest sales volume.
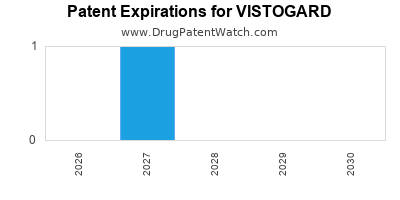
A definitive patent-expiration analysis requires the current FDA Orange Book patent-and-exclusivity listing and the underlying USPTO prosecution records. Public product information alone does not establish a complete, accurate list of enforceable claims or terminal-disclaimer-adjusted expiration dates.
What is the Orange Book status of Vistogard?
Vistogard is associated with NDA 208306 and should be assessed through the current FDA Orange Book for:
- Listed patents.
- Patent-use codes.
- Expiration dates.
- Pediatric exclusivity.
- Any delistings or updates.
- The presence of a reference listed drug entry relevant to an ANDA.
The Orange Book does not provide a complete freedom-to-operate analysis. It does not capture every patent that could be asserted against a generic, including some formulation, manufacturing, packaging, or non-Orange-Book-eligible patents.
For commercial diligence, the critical question is not simply whether the product has a listed patent. It is whether a generic could obtain approval, launch at risk, or design around the asserted claims while achieving acceptable manufacturing economics.
Which companies are challenging Vistogard?
No major public Paragraph IV litigation campaign against Vistogard is established in the principal public FDA materials and widely reported federal case records available for this analysis. The absence of a visible challenge does not prove that no ANDA has been filed or that no confidential patent notice exists.
The most credible future challengers would be:
- Generic oncology manufacturers with oral-granule manufacturing capacity.
- Specialty generic companies targeting low-volume, high-price products.
- Companies with existing fluorouracil or capecitabine portfolios.
- Contract manufacturers able to produce uridine triacetate at low scale.
The market is less attractive to a generic than a conventional high-volume tablet because emergency products must be commercially available before the event occurs. A generic would need to support hospital stocking, specialty distribution, short-notice shipment, and payer access.
What generic entry risks exist for Vistogard?
Generic entry risk is moderate in regulatory terms but potentially lower in commercial terms.
Regulatory risk
Uridine triacetate is a small molecule, so it is theoretically eligible for an ANDA pathway. A generic applicant would need to address:
- Pharmaceutical equivalence.
- Bioequivalence.
- Granule formulation and administration.
- Stability and packaging.
- Labeling and indication requirements.
- Patent certifications and any applicable litigation stay.
The lack of a biosimilar barrier makes Vistogard more exposed than a biologic rescue product.
Commercial risk
A generic could face difficulties because:
- The market is small and geographically dispersed.
- Hospitals may prefer the established brand during emergencies.
- Emergency stock must be maintained before demand is known.
- A low price may not compensate for distribution and inventory costs.
- The product must be available continuously, not only ordered after a prescription arrives.
A first generic could cause substantial price erosion if it secures broad hospital contracts. A later entrant would likely face weaker economics unless it has a differentiated distribution model.
What patent litigation affects Vistogard?
No clearly established, high-profile federal patent litigation involving Vistogard is identified in the principal public sources reviewed for this market assessment. The main legal exposure is prospective:
- An ANDA filing with a Paragraph IV certification.
- Patent litigation initiated after notice to the NDA holder.
- A potential 30-month stay if statutory requirements are met.
- A settlement involving a licensed generic entry date.
- An at-risk launch after approval if the applicant elects to proceed before patent expiration.
Because the product serves an emergency indication, litigation strategy may focus on the strongest method-of-use or formulation claims rather than attempting to preserve every peripheral patent.
Are there biosimilar risks for Vistogard?
No. Vistogard contains uridine triacetate, a small-molecule active ingredient. Biosimilar regulation under the Public Health Service Act does not apply.
The relevant competitive threat is generic substitution, not biosimilar substitution. Off-label use of compounded or non-equivalent uridine products may create limited clinical competition, but those products would not automatically be therapeutically or regulatorily interchangeable with Vistogard.
How does Vistogard compare with alternative treatments?
| Treatment approach |
FDA-approved antidote for this use |
Speed and practicality |
Commercial effect |
| Vistogard |
Yes |
Oral, predefined five-day regimen |
Supports premium emergency pricing |
| Treatment interruption and supportive care |
No specific antidote |
Widely available but may be inadequate in severe toxicity |
Caps total market and provides clinical alternative |
| Intensive-care management |
No |
Necessary for advanced toxicity but resource intensive |
Complements rather than directly replaces Vistogard |
| Off-label uridine products |
Not necessarily |
Variable formulation, evidence, and access |
Potential low-cost substitute in selected settings |
| Prevention through pharmacogenetic testing |
Not a rescue treatment |
Reduces future toxicity risk |
May reduce long-term event volume but does not replace emergency treatment |
Vistogard’s strongest competitive advantage is not broad efficacy across oncology. It is the combination of FDA approval, a defined dosing regimen, and use in a time-sensitive event where clinicians have limited approved options.
What licensing deals affect Vistogard?
The public commercial record does not establish a major, widely disclosed licensing transaction that has materially changed Vistogard’s ownership or revenue profile. Wellstat has been the principal company associated with the product’s development and commercialization.
Any distribution, specialty-pharmacy, co-promotion, or regional licensing arrangement should be distinguished from an assignment of the underlying NDA or patents. For valuation, the key questions are:
- Who controls NDA 208306?
- Who owns the relevant patent families?
- Who receives U.S. net sales?
- Are there minimum purchase or royalty obligations?
- Are there termination rights tied to supply or regulatory performance?
Without product-level financial disclosures and confirmed transaction documents, licensing economics cannot be quantified reliably.
What is the geographic coverage of Vistogard?
The United States is the clearest commercial market because FDA approval creates a defined regulatory and reimbursement framework. International opportunity depends on separate approvals and local recognition of uridine triacetate.
Geographic expansion faces several obstacles:
- Low event incidence in each country.
- Need for 24-hour oncology access.
- Local hospital purchasing structures.
- Different fluoropyrimidine prescribing patterns.
- Country-specific orphan-drug pricing rules.
- Requirements for local pharmacovigilance and distribution.
A global strategy would likely prioritize countries with high fluoropyrimidine use, concentrated oncology networks, and reimbursement mechanisms for emergency medicines.
How strong is the Vistogard patent estate?
Vistogard’s commercial protection is best characterized as a layered orphan-product estate rather than a high-volume composition-of-matter franchise.
| Protection layer |
Relative value |
| FDA approval and clinical evidence |
High in the emergency-use setting |
| Orphan exclusivity |
Expired on its nominal seven-year schedule in 2022 |
| Active composition claims |
Potentially high if broad and unexpired |
| Granule formulation claims |
Moderate to high depending on claim scope |
| Method-of-use claims |
Important because the market is indication-specific |
| Manufacturing know-how |
Moderate, particularly for small-volume supply |
| Brand and hospital protocols |
Moderate and potentially durable |
| Biosimilar barrier |
None |
The estate is commercially strongest when patent protection, hospital stocking, and physician familiarity operate together. Its weakest point is the possibility that a generic can reproduce the therapeutic product without replicating a narrow formulation or process claim.
What is the likely generic launch scenario?
Base case
Vistogard remains the reference brand in a small emergency market, with limited direct competition. Revenue is stable or gradually declines as hospital purchasing becomes more price-sensitive.
Downside case
A first generic obtains approval and captures hospital contracts. Net price declines materially, but total treated volume changes little because the underlying toxicity incidence remains stable.
Upside case
The sponsor expands hospital stocking, improves reimbursement, increases awareness of fluoropyrimidine toxicity, and broadens international access. Revenue grows through account penetration rather than through a large increase in patients.
The most important commercial trigger is a first substitutable generic, not a competing oncology drug. A generic entrant could reduce price quickly even if it does not significantly increase treatment volume.
Key Takeaways
- Vistogard is an FDA-approved oral antidote for fluorouracil and capecitabine overdose and early severe toxicity.
- Its market is narrow, high-acuity, and driven by hospital stocking rather than routine prescribing.
- FDA approval occurred on October 11, 2015; nominal seven-year orphan exclusivity reached its endpoint in October 2022.
- The product has no biosimilar risk because uridine triacetate is a small molecule.
- Generic risk is technically feasible through the ANDA pathway but commercially constrained by low volume and emergency distribution requirements.
- Public product-level revenue data are not available because the sponsor is privately held.
- The most valuable protections are likely the combined effect of formulation, method-of-use, manufacturing, regulatory, and hospital-adoption barriers.
- A first approved generic would be the principal event capable of causing rapid price erosion.
FAQs
Is Vistogard used for routine fluorouracil side effects?
No. It is approved for overdose and early-onset severe or life-threatening toxicity, generally when treatment begins within 96 hours of fluorouracil or capecitabine administration.
Can Vistogard be substituted automatically by a generic?
Automatic substitution depends on FDA therapeutic-equivalence ratings, state pharmacy law, payer rules, and the specific approved generic. FDA approval alone does not determine every state-level substitution outcome.
Does Vistogard have a pediatric exclusivity extension?
The existence and duration of any pediatric exclusivity should be confirmed in the current FDA Orange Book. The 2015 approval date alone does not establish an additional six-month extension.
What is the main manufacturing barrier for a Vistogard generic?
The main barriers are production of a stable, pharmaceutically equivalent oral-granule product, validated analytical methods, dependable low-volume supply, and emergency distribution rather than complex biologic manufacturing.
Could pharmacogenetic testing reduce Vistogard demand?
Yes. Wider testing for dihydropyrimidine dehydrogenase deficiency could reduce some preventable fluoropyrimidine toxicity events. It would not eliminate accidental overdoses, administration errors, or toxicity in patients without an identified high-risk genotype.
References
- U.S. Food and Drug Administration. (2015). Vistogard (uridine triacetate) prescribing information.
- Haller, D. G., Cassidy, J., Clarke, S. J., et al. (2016). Potentially fatal early-onset severe or life-threatening toxicity following fluoropyrimidine treatment: A prospective study of uridine triacetate rescue. Cancer, 122(8), 1160-1167.
- U.S. Food and Drug Administration. (n.d.). Drugs@FDA: Vistogard, NDA 208306.
- U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations, Orange Book.
- National Library of Medicine. (n.d.). DailyMed: Vistogard, uridine triacetate.