Share This Page
Drug Sales Trends for LEXAPRO
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for LEXAPRO (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
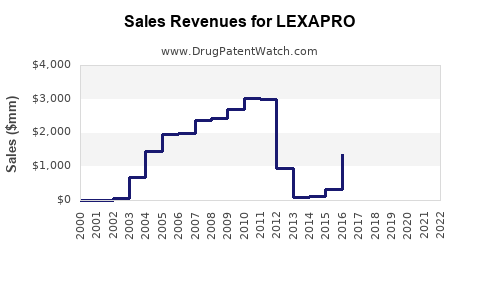
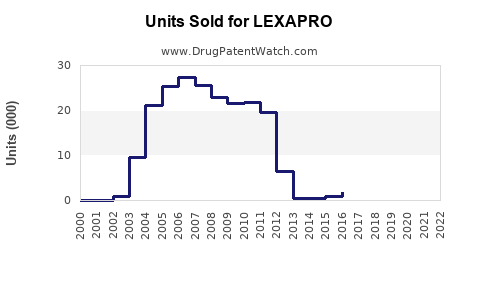
Annual Sales Revenues and Units Sold for LEXAPRO
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| LEXAPRO | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| LEXAPRO | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| LEXAPRO | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| LEXAPRO | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| LEXAPRO | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Lexapro (Escitalopram) Market Analysis, Patent Status and Sales Projections
Lexapro, the branded version of escitalopram, is a mature selective serotonin reuptake inhibitor with minimal remaining brand value and extensive generic competition. The commercial market is driven by low-cost escitalopram tablets, oral solutions and authorized generic products rather than the Lexapro brand. U.S. brand exclusivity ended in 2012, and no biosimilar risk applies because escitalopram is a conventional small-molecule drug. Future market growth will depend mainly on prescription volume, pricing, treatment duration and geographic expansion.
What is Lexapro and what is its current market position?
Lexapro is escitalopram oxalate, the S-enantiomer of citalopram. The FDA approved Lexapro in 2002 for major depressive disorder in adults and later expanded the label to generalized anxiety disorder in adults and pediatric patients in the United States (FDA, 2023a).
| Market attribute | Assessment |
|---|---|
| Active ingredient | Escitalopram oxalate |
| Drug class | Selective serotonin reuptake inhibitor |
| Original U.S. sponsor | Forest Laboratories |
| Current corporate ownership | AbbVie, through the acquisition of Allergan |
| U.S. approval | 2002 |
| Primary indications | Major depressive disorder; generalized anxiety disorder |
| Dosage forms | 5 mg, 10 mg and 20 mg tablets; oral solution |
| U.S. patent position | Core exclusivity expired |
| Current competitive status | Generic-dominated |
| Biosimilar exposure | None |
| Main commercial risk | Generic price erosion and substitution |
Lexapro became one of the leading antidepressants in the U.S. before generic entry. Forest Laboratories reported Lexapro net sales of approximately $2.3 billion in fiscal 2011, shortly before the loss of U.S. exclusivity (Forest Laboratories, 2011). The product’s brand revenue declined sharply after generic escitalopram launched.
When did Lexapro lose exclusivity?
Lexapro lost effective U.S. exclusivity in 2012 after settlement arrangements allowed generic escitalopram to enter before the expiry of the principal patent term.
The Orange Book-listed patent commonly associated with Lexapro was U.S. Patent No. 4,943,590, covering citalopram-related compounds and expiring in 2009, subject to regulatory extensions and other legal protections. A later patent, U.S. Patent No. 6,916,941, covered escitalopram and had a reported expiration date in 2020, although generic entry occurred earlier under settlement terms. Forest also obtained pediatric exclusivity and other regulatory protections that affected market timing (FDA, 2023b; FTC, 2012).
Lexapro exclusivity timeline
| Event | Date | Commercial effect |
|---|---|---|
| FDA approval of Lexapro | 2002 | Initial U.S. market entry |
| New chemical entity exclusivity | 2006 | Restricted ANDA approval until exclusivity ended |
| Core patent and regulatory disputes | 2009-2011 | Delayed or contested generic entry |
| First authorized generic arrangements | 2012 | Reduced post-entry brand erosion |
| Generic escitalopram launch | 2012 | Rapid conversion from brand to generic |
| Current market | 2024 onward | Generic-dominated; limited brand pricing power |
The exact exclusivity sequence depended on the listed patents, pediatric exclusivity, litigation settlements and the FDA’s approval timing for individual ANDAs. FDA Orange Book records remain the controlling source for current patent listings and expiration data.
What patents protect Lexapro?
Lexapro’s core composition and pharmaceutical protection has expired or become commercially ineffective against generic competition. The most important historical patents include the following.
| Patent | Subject matter | Historical relevance |
|---|---|---|
| U.S. Patent No. 4,943,590 | Citalopram-related compounds | Foundational compound protection |
| U.S. Patent No. 6,916,941 | Escitalopram and related pharmaceutical compositions | Principal later Lexapro patent |
| U.S. patent listings related to formulations and uses | Dosage forms, treatment methods or formulations | Limited ability to preserve brand sales after generic entry |
The commercial value of a mature drug’s patent estate depends on whether a listed patent blocks an ANDA, supports a Paragraph IV lawsuit or protects a commercially important formulation. For Lexapro, the market outcome shows that the core estate did not sustain meaningful branded revenue after generic entry.
What formulations are protected by Lexapro patents?
Lexapro was marketed primarily as immediate-release tablets and an oral solution. Formulation and method-of-use patents had less strategic value than the core active-ingredient protection because generic manufacturers could generally enter with bioequivalent immediate-release products.
Potential formulation barriers included:
- Tablet composition and manufacturing processes.
- Oral-solution formulation.
- Pharmaceutical salts and stereochemical purity.
- Dosing methods for depression and anxiety.
- Pediatric use and titration regimens.
These protections did not create a durable commercial barrier comparable to a long-lived extended-release delivery system, injectable formulation or device combination. Escitalopram’s conventional oral dosage forms are comparatively easy for generic manufacturers to reproduce.
What is the Orange Book status of Lexapro?
Lexapro’s Orange Book status is commercially mature. The FDA Orange Book identifies approved reference-listed drug products, therapeutic equivalents and relevant patent or exclusivity information. Generic escitalopram products have long been approved through the abbreviated new drug application pathway.
The practical implications are:
- Generic substitution is established.
- Brand Lexapro does not control the U.S. escitalopram market.
- Any remaining listed patent must be assessed at the product level and against current ANDA approvals.
- Patent litigation is unlikely to restore meaningful brand pricing absent a new, differentiated formulation.
A current Orange Book review should distinguish between the original Lexapro reference product, authorized generic products and generic escitalopram manufacturers. Patent listings can change by product and dosage form.
Which companies challenged Lexapro patents?
The principal generic challenge involved Ivax, later associated with Teva, and other generic manufacturers seeking approval to market escitalopram before the full expiry of Forest’s patent protections. Forest Laboratories pursued patent litigation and entered settlement arrangements that structured the timing of generic entry.
The Lexapro disputes were part of a broader period in which brand pharmaceutical companies used patent litigation, authorized generics and settlement agreements to manage the transition from branded to generic sales. The Federal Trade Commission has reviewed several pharmaceutical patent settlements, including settlements involving antidepressants and other high-volume drugs (FTC, 2012).
What Paragraph IV risks affected Lexapro?
Paragraph IV certifications created the principal generic-entry risk. A generic applicant could certify that a listed patent was invalid, unenforceable or would not be infringed. That certification could trigger litigation and a statutory stay of FDA approval, generally for up to 30 months under the Hatch-Waxman framework.
For Lexapro, the outcome was not indefinite exclusion. The market eventually received generic escitalopram, and the subsequent price decline was substantial. This indicates that the patent estate had limited ability to sustain exclusion once generic applicants established a viable legal and regulatory pathway.
What was Lexapro’s peak revenue and how much revenue is exposed today?
Lexapro’s U.S. brand sales peaked near $2 billion annually, with Forest Laboratories reporting approximately $2.3 billion in fiscal 2011 worldwide net product sales. That revenue base was exposed to generic substitution beginning in 2012.
| Period | Brand revenue profile | Market interpretation |
|---|---|---|
| 2002-2006 | Rapid growth | New branded SSRI with broad physician adoption |
| 2007-2011 | Peak sales | High-volume maintenance therapy and anxiety indication |
| 2012-2013 | Steep decline | Generic entry and payer substitution |
| 2014 onward | Low residual brand value | Generic escitalopram became the economic standard |
| Current | Small brand opportunity | Brand sales are secondary to molecule volume |
The current financial exposure is concentrated in generic escitalopram manufacturers, pharmacy distributors and retailers. AbbVie’s direct Lexapro revenue is not comparable with the historical Forest Laboratories sales base.
What are the market drivers for escitalopram?
Escitalopram demand is supported by several durable factors:
- High prevalence of depression and anxiety disorders.
- Long treatment duration for maintenance patients.
- Primary-care prescribing rather than exclusive specialist use.
- Low generic cost and broad insurance coverage.
- Familiarity among physicians and patients.
- Availability in multiple strengths and oral solution.
- Continued use in young adults and older patients.
The main volume constraint is therapeutic competition. Sertraline, fluoxetine, paroxetine, venlafaxine, duloxetine, bupropion and newer branded psychiatric therapies compete for the same or overlapping patient populations.
Escitalopram also faces switching pressure from generic sertraline and other SSRIs when payers use formulary controls. Unlike newer branded antidepressants, it has limited ability to command a premium based on mechanism or delivery technology.
How does Lexapro compare with competing antidepressants?
| Drug | Class | U.S. market status | Competitive position |
|---|---|---|---|
| Escitalopram | SSRI | Generic | Strong adherence and broad familiarity |
| Sertraline | SSRI | Generic | Major low-cost competitor |
| Fluoxetine | SSRI | Generic | Long half-life and low price |
| Paroxetine | SSRI | Generic | Older option with tolerability limitations |
| Venlafaxine | SNRI | Generic | Used where dual serotonin-norepinephrine activity is preferred |
| Duloxetine | SNRI | Generic | Competes in depression, anxiety and pain |
| Bupropion | NDRI | Generic | Different side-effect and smoking-cessation profile |
| Vortioxetine | Multimodal antidepressant | Branded | Premium alternative with differentiated positioning |
| Vilazodone | Serotonin modulator | Branded/generic transition depending jurisdiction | Smaller commercial position |
Escitalopram’s advantage is not patent protection. It is prescribing familiarity, low cost and continued use in patients who respond adequately and tolerate treatment.
What are the sales projections for Lexapro and escitalopram?
Because public companies generally do not disclose global escitalopram sales by manufacturer, the most useful forecast separates Lexapro brand revenue from the total escitalopram molecule market.
Base-case projection
The following model assumes mature generic pricing, stable or modestly growing prescription volume, continued generic substitution and no major supply disruption. Figures represent estimated global manufacturer revenue for all escitalopram products, not retail pharmacy sales.
| Year | Low case | Base case | High case |
|---|---|---|---|
| 2024 | $0.65 billion | $0.85 billion | $1.05 billion |
| 2025 | $0.63 billion | $0.86 billion | $1.08 billion |
| 2026 | $0.61 billion | $0.87 billion | $1.11 billion |
| 2027 | $0.58 billion | $0.88 billion | $1.13 billion |
| 2028 | $0.56 billion | $0.89 billion | $1.15 billion |
| 2029 | $0.54 billion | $0.90 billion | $1.17 billion |
The base case implies approximately 1% annual growth in nominal global molecule revenue. Volume growth is partly offset by continuing price erosion in the United States and other mature markets.
Lexapro brand projection
| Year | Estimated U.S. brand revenue | Expected trend |
|---|---|---|
| 2024 | Less than $25 million | Residual brand demand |
| 2025 | Less than $25 million | Stable to declining |
| 2026 | Less than $20 million | Limited commercial relevance |
| 2027-2029 | Less than $20 million annually | Primarily legacy or formulary-driven demand |
These figures are directional market estimates, not reported company guidance. The brand is unlikely to regain a material share without a new formulation, a major relaunch or a regulatory strategy that creates differentiated use.
What generic entry scenarios exist for escitalopram?
Scenario one: Continued price erosion
This is the most likely outcome. Multiple ANDA holders compete for pharmacy contracts, causing low prices and periodic margin compression. Revenue declines even if prescription volume remains stable.
Scenario two: Stable volume with supply-driven price increases
A manufacturing disruption, API shortage or product withdrawal could temporarily increase prices. Such increases would benefit suppliers with reliable capacity but would not create durable patent value.
Scenario three: Premium formulation strategy
A manufacturer could seek approval for an improved formulation, such as modified release, an abuse-deterrent presentation or a differentiated pediatric formulation. The commercial opportunity would depend on clinical evidence, reimbursement and the ability to avoid direct therapeutic-equivalence substitution.
Scenario four: International volume growth
Emerging markets may produce modest volume growth as diagnosis and treatment access increase. Price realization would generally remain below U.S. branded levels.
How strong is the Lexapro patent estate?
The Lexapro patent estate is weak as a current commercial defense.
| Factor | Assessment |
|---|---|
| Core compound protection | Expired or no longer commercially blocking |
| Formulation protection | Limited |
| Method-of-use protection | Narrow relative to generic indications |
| ANDA litigation leverage | Low |
| Generic substitution risk | Very high |
| Manufacturing barrier | Low to moderate |
| Brand pricing power | Minimal |
| Biosimilar barrier | Not applicable |
| New product lifecycle opportunity | Possible only through differentiated formulation |
Escitalopram is a relatively simple oral small molecule. Manufacturing know-how, quality systems and regulatory compliance matter, but they do not create a barrier equivalent to biologic cell-line ownership, complex injectables or device-integrated products.
What licensing deals and settlement agreements affected Lexapro?
Forest Laboratories used commercial arrangements and settlement structures with generic companies to manage generic entry. Authorized generic strategies were important because they allowed the brand company to participate in post-exclusivity volume while reducing the commercial impact of independent generic launches.
The economic value of these arrangements depended on:
- Launch timing.
- Authorized generic supply rights.
- Royalty or profit-sharing terms.
- Patent litigation resolution.
- Allocation of dosage strengths and channels.
- The number of independent generic entrants.
Public disclosures provide historical information on the arrangements, but the full economic terms of private settlement agreements are not always available. Their strategic effect was clear: generic entry occurred, but the transition was managed rather than left entirely to an immediate multi-supplier price collapse.
What regulatory status does Lexapro have?
Lexapro is an FDA-approved prescription drug. Generic escitalopram products are approved through ANDAs demonstrating pharmaceutical equivalence and bioequivalence to the reference product (FDA, 2023a).
Key regulatory points include:
- No biologics license application applies.
- No biosimilar pathway applies.
- Generic tablets can generally obtain therapeutic-equivalence ratings.
- Oral solution products must satisfy formulation, quality and bioequivalence requirements applicable to the product.
- Pediatric labeling and dosing remain relevant to market positioning.
- New indications would require supplemental clinical and regulatory support.
FDA approval does not prevent substitution where state pharmacy laws, payer policies and product-specific therapeutic-equivalence ratings support generic dispensing.
What geographic markets offer the most opportunity?
The United States remains a high-volume market but has limited price upside. Western Europe also has substantial escitalopram use, but national reimbursement systems constrain pricing. Growth potential is greater in selected emerging markets where antidepressant diagnosis and treatment penetration remain lower.
| Region | Volume outlook | Price outlook | Commercial assessment |
|---|---|---|---|
| United States | Stable to modest growth | Low and declining | Scale market, weak margins |
| Western Europe | Stable | Low to moderate | Reimbursement-controlled |
| Japan | Mature | Moderate | Regulatory and channel-specific |
| Latin America | Moderate growth | Variable | Local registration and distribution matter |
| China | Growth potential | Competitive | Domestic generic competition is strong |
| India | High generic supply | Low | Manufacturing and export platform |
| Middle East and Africa | Lower base, gradual growth | Variable | Access expansion supports volume |
What manufacturing and intellectual-property barriers exist?
Escitalopram manufacturing barriers are primarily operational rather than patent-based. Suppliers must control stereochemical purity, impurity profiles, dissolution, stability and batch consistency. API sourcing can affect cost and continuity of supply.
Important operational risks include:
- Dependence on a limited number of API producers.
- Regulatory observations at manufacturing sites.
- Serialization and supply-chain compliance.
- Product recalls caused by contamination or dissolution failures.
- Shortages caused by low generic margins.
- Country-specific registration requirements.
- Difficulty maintaining profitability when several suppliers compete.
A manufacturer with vertically integrated API and finished-dose production can protect margins better than a distributor purchasing commodity product on the open market.
Key Takeaways
- Lexapro is a mature escitalopram brand with little remaining U.S. commercial value.
- U.S. generic entry began in 2012, ending the product’s high-margin lifecycle.
- The historical Lexapro franchise generated approximately $2.3 billion in fiscal 2011 sales.
- Escitalopram remains commercially important because of prescription volume, treatment persistence and low cost.
- The active market is generic and highly price-sensitive.
- The base-case global escitalopram manufacturer market is estimated at approximately $850 million in 2024, rising gradually toward $900 million by 2029.
- Brand Lexapro revenue is likely below $25 million annually in the United States.
- Patent strength is low; manufacturing quality and supply reliability are more important than exclusionary IP.
- Paragraph IV litigation and settlement agreements shaped entry timing but did not preserve long-term brand economics.
- No biosimilar risk applies. The relevant threat is conventional generic substitution.
- A new formulation or clinically differentiated delivery system would be required to create a meaningful lifecycle-management opportunity.
FAQs
Is Lexapro still sold as a brand-name drug?
Yes. Lexapro may remain available in some markets, but most U.S. prescriptions are filled with generic escitalopram. Brand demand is limited by formulary controls and therapeutic substitution.
Does escitalopram have an active U.S. patent?
The original Lexapro patent estate no longer provides a meaningful barrier to ordinary generic escitalopram tablets. Current Orange Book listings should be reviewed for product-specific patents and formulations.
Can a company launch an authorized generic of Lexapro?
An authorized generic can be marketed under an arrangement with the brand owner or through an approved generic pathway. Its value depends on supply rights, pricing and the number of competing ANDA products.
Is escitalopram a good generic investment?
It can provide stable volume but usually offers limited pricing power. Investment attractiveness depends on manufacturing cost, supply reliability, market access and the ability to avoid excessive dependence on a single low-price tender.
Could a new Lexapro formulation regain premium pricing?
Only if the formulation provides clinically meaningful differentiation, receives regulatory approval and obtains favorable reimbursement. A minor tablet change would be unlikely to overcome established generic substitution.
More… ↓
