Last updated: September 17, 2026
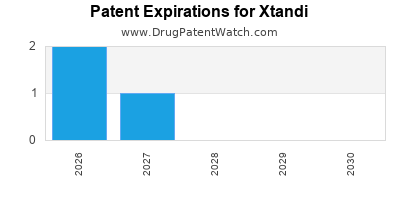
XTANDI, the enzalutamide androgen-receptor inhibitor marketed by Astellas Pharma and Pfizer, remains a major prostate-cancer franchise despite increasing competition from NUBEQA, ERLEADA, generic abiraterone, and other androgen-deprivation therapies. Global sales have remained near the $4 billion level, supported by expanded use in metastatic castration-sensitive prostate cancer and nonmetastatic castration-resistant prostate cancer. The principal commercial risk is U.S. generic entry after the core patent estate begins expiring in 2027, although formulation patents, litigation settlements, regulatory exclusivities, and manufacturing complexity may delay broad substitution.
What is XTANDI and how does it generate revenue?
XTANDI contains enzalutamide, an oral androgen-receptor signaling inhibitor. It binds the androgen receptor, inhibits nuclear translocation, reduces DNA binding, and suppresses transcription of androgen-responsive genes.
The FDA approved XTANDI in 2012 for metastatic castration-resistant prostate cancer after docetaxel treatment. Its U.S. label later expanded to include:
- Metastatic castration-resistant prostate cancer.
- Metastatic castration-sensitive prostate cancer.
- Nonmetastatic castration-resistant prostate cancer at high risk of metastasis.
The product is sold primarily as 40 mg capsules and 80 mg tablets. The standard adult dose is 160 mg once daily, administered as four 40 mg capsules or two 80 mg tablets. The tablet formulation improves pill burden and may strengthen lifecycle management against capsule-only generic products.
Astellas and Pfizer commercialize XTANDI under a global collaboration. Astellas has historically reported the larger share of global product sales, while Pfizer reports alliance revenue from the U.S. collaboration. The companies also share development and commercialization economics under their strategic partnership.
How large is the XTANDI market?
XTANDI has developed into one of the largest oral oncology products worldwide. Reported sales have generally remained in the range of $3.5 billion to $4.5 billion annually, depending on currency conversion and fiscal-year reporting.
| Metric |
Recent position |
| Active ingredient |
Enzalutamide |
| Primary disease area |
Prostate cancer |
| Global annual sales range |
Approximately $4 billion |
| U.S. commercial partner |
Pfizer |
| Global originator |
Astellas |
| Principal competitors |
NUBEQA, ERLEADA, abiraterone, ORGOVYX |
| Main loss-of-exclusivity window |
Core U.S. patents begin expiring in 2027 |
| U.S. FDA pathway for competitors |
ANDA, with Paragraph IV litigation risk |
Astellas reported XTANDI sales of approximately ¥300 billion in fiscal 2023, the year ended March 31, 2024. Pfizer reported approximately $1.3 billion in 2023 U.S. alliance revenue for XTANDI. Differences between the companies' reported figures reflect geography, accounting treatment, currency, and revenue-sharing arrangements rather than different global demand estimates (Astellas Pharma, 2024; Pfizer, 2024).
The franchise has benefited from treatment migration into earlier disease settings. Use in metastatic castration-sensitive disease expands the addressable population, while nonmetastatic castration-resistant disease supports treatment before radiographic metastases emerge. The commercial value of these indications depends on continued guideline use, payer access, treatment duration, and competition from other next-generation androgen-receptor inhibitors.
What is the XTANDI revenue trajectory?
XTANDI revenue growth has shifted from rapid launch expansion to maturity. Early growth came from new indications and geographic penetration. More recent performance has depended on volume growth, treatment duration, pricing, and currency.
| Period |
Revenue direction |
Principal driver |
| 2012-2015 |
Rapid expansion |
Initial mCRPC approval and international rollout |
| 2016-2019 |
Strong growth |
Earlier-line use and nmCRPC approval |
| 2020-2022 |
Continued scale |
mCSPC adoption and broader diagnosis |
| 2023-2025 |
Mature franchise |
Volume growth offset by competition and currency |
| 2027 onward |
Declining U.S. revenue risk |
Core patent expiry and generic entry |
Astellas has continued to rely on XTANDI as one of its largest products. Its relative contribution to total company revenue remains material even as oncology products such as PADCEV and other pipeline assets diversify the portfolio.
Pfizer’s exposure is more concentrated in its U.S. alliance economics. A U.S. generic launch would therefore affect Pfizer’s alliance revenue and Astellas’ global product economics, but the impact would not be identical because foreign patent terms and market structures differ.
When does XTANDI lose exclusivity?
The key U.S. composition-of-matter patent is U.S. Patent No. 7,709,517, covering enzalutamide-related compounds. Public patent records identify a September 2027 expiration date for the principal patent, subject to applicable patent-term adjustments and regulatory calculations (U.S. Patent and Trademark Office, 2010).
The effective loss-of-exclusivity date can differ from the nominal expiration date because of:
- Patent-term adjustment.
- Patent-term extension.
- Pediatric exclusivity.
- Orange Book-listed formulation or method-of-use patents.
- Court-ordered injunctions.
- ANDA litigation settlements.
- Authorized generic decisions.
- Different timing for capsules and tablets.
The primary U.S. commercial risk is therefore a launch window beginning around 2027 rather than a single universal cliff date.
XTANDI exclusivity timeline
| Date |
Event |
| 2004 |
Priority filings for enzalutamide-related patent technology |
| 2010 |
U.S. Patent No. 7,709,517 issued |
| 2012 |
FDA approval for post-docetaxel mCRPC |
| 2014 |
FDA approval expanded to pre-chemotherapy mCRPC |
| 2018 |
FDA approval for high-risk nmCRPC |
| 2019 |
FDA approval for mCSPC |
| 2027 |
Principal U.S. composition patent expiration window |
| 2027 onward |
Potential U.S. generic launches, subject to litigation and settlement terms |
The Orange Book should be reviewed for the current patent list because listed patents, expiration dates, and exclusivity codes can change through FDA updates and court outcomes. Patent expiry alone does not establish that a generic product will enter on that date.
What patents protect XTANDI?
XTANDI protection has historically relied on a layered estate covering the active compound, pharmaceutical compositions, dosing, and approved uses.
Core composition patents
U.S. Patent No. 7,709,517 is the most commercially important patent family associated with enzalutamide. It covers diaryl thiohydantoin compounds and related androgen-receptor antagonists. The patent family has been central to XTANDI’s primary exclusivity position.
Formulation and dosage-form patents
XTANDI’s capsule and tablet presentations create separate technical positions. Formulation protection may address:
- Specific enzalutamide dosage forms.
- Excipients and solid formulations.
- Bioavailability characteristics.
- Tablet or capsule composition.
- Dosing regimens and administration schedules.
Formulation patents can delay substitution only when they are valid, enforceable, properly listed, and relevant to the generic applicant’s proposed labeling or product design. An ANDA applicant may certify that a listed formulation patent is not infringed or is invalid.
Method-of-use patents
Method-of-use patents may cover treatment of defined prostate-cancer populations, including:
- Castration-resistant disease.
- Nonmetastatic castration-resistant disease.
- Metastatic castration-sensitive disease.
- Patient selection based on prior therapy or disease status.
- Specific dosing or treatment combinations.
A generic applicant can seek approval for non-patented indications through a section viii statement or by submitting a label that omits protected uses. The commercial effectiveness of a method-of-use patent depends on whether the protected indication is central to prescribing and whether physicians can readily substitute the generic for unprotected uses.
What is the Orange Book status of XTANDI?
XTANDI is an FDA-approved small-molecule drug listed in the Orange Book. Orange Book patents are relevant to ANDA approval and Paragraph IV litigation.
The commercial assessment should distinguish among:
- The active-ingredient patent.
- Formulation patents.
- Method-of-use patents.
- Regulatory exclusivity.
- Patent certifications submitted by ANDA applicants.
The FDA does not decide patent validity through the Orange Book. The agency lists qualifying patents and applies statutory approval timing rules. Patent disputes are resolved through federal litigation or settlement agreements.
The main Orange Book risk is that the core composition patent may provide less protection after 2027, while secondary patents may not prevent a fully substitutable generic product if competitors can design around them or use a skinny label.
Which companies are challenging XTANDI patents?
Generic manufacturers have pursued or evaluated enzalutamide ANDA strategies as the principal patents approach expiration. Publicly reported litigation and patent challenges have involved companies including:
- Sun Pharmaceutical Industries.
- Zydus Pharmaceuticals.
- Dr. Reddy’s Laboratories.
- Lupin.
- Teva Pharmaceuticals.
- Apotex and other generic applicants.
The precise defendant group, asserted patents, and case status vary by jurisdiction and filing period. A Paragraph IV certification can trigger a patent-infringement action within 45 days, creating a statutory stay of FDA approval for up to 30 months unless the litigation is resolved earlier or the stay is modified.
What does a Paragraph IV challenge mean for XTANDI?
A Paragraph IV challenge alleges that a listed patent is invalid, unenforceable, or will not be infringed by the proposed generic. It does not guarantee an early launch. Outcomes include:
- Generic launch after a favorable court decision.
- Launch after settlement.
- Launch at the agreed settlement date.
- Delayed approval because of the 30-month stay.
- Loss of the challenge through patent validation.
- Commercial entry by an authorized generic.
The most important litigation question is whether generic applicants can launch before September 2027 or must wait until that date or a negotiated later date.
What patent litigation affects XTANDI?
XTANDI litigation has centered on the validity and infringement of Orange Book-listed patents. Astellas has an economic incentive to assert secondary patents because early generic entry would affect a multibillion-dollar franchise.
Key litigation variables include:
| Issue |
Commercial significance |
| Core patent validity |
Determines whether early entry is possible |
| Formulation patent scope |
May affect tablet or capsule substitution |
| Skinny-label strategy |
Can permit approval for unprotected uses |
| 30-month stay |
Delays FDA approval during litigation |
| Settlement date |
Establishes predictable entry timing |
| Authorized generic terms |
Determines price erosion and market share |
| Multiple challengers |
Increases probability of competition after entry |
Settlement agreements can reduce uncertainty but may preserve substantial revenue through delayed generic launch. The economic value of an agreement depends on the negotiated entry date, royalty terms, authorized-generic restrictions, and the number of competing manufacturers.
What generic entry risks exist for XTANDI?
XTANDI faces a high post-2027 generic erosion risk because it is an oral small molecule with no biologic interchangeability barrier. Generic manufacturers do not need to replicate a complex biologic manufacturing process. They must demonstrate pharmaceutical equivalence and bioequivalence under the ANDA pathway.
Generic entry risk is highest when:
- The core composition patent expires.
- Several ANDAs are approved at the same time.
- Multiple manufacturers have manufacturing capacity.
- Payers impose mandatory substitution.
- The branded product has limited clinical differentiation.
- The generic can enter with a broad or commercially sufficient label.
Revenue erosion could be rapid in the United States. Oral oncology products can lose substantial branded share after the first generic launch, particularly when pharmacy benefit managers and health plans apply automatic substitution or tiered reimbursement.
Astellas and Pfizer may moderate erosion through:
- Contracting.
- Patient-support programs.
- Authorized-generic supply.
- Brand-prescription retention.
- Further label expansion.
- International lifecycle management.
- Differentiation through tablets, packaging, or distribution.
These measures generally slow price and share erosion rather than preserve pre-expiry revenue.
How strong is the XTANDI patent estate?
The XTANDI patent estate is strong historically but weaker after core composition-patent expiry.
| Patent-strength factor |
Assessment |
| Composition protection |
Strong until the principal expiry window |
| Regulatory history |
Strong, with multiple approved indications |
| Formulation protection |
Potentially useful but more vulnerable to design-around |
| Method-of-use protection |
Valuable where indications are commercially concentrated |
| Generic substitution barrier |
Low compared with biologic products |
| Manufacturing barrier |
Moderate, not prohibitive |
| Litigation leverage |
Meaningful before core expiry |
| Post-2027 durability |
Dependent on secondary patents and settlements |
The strongest part of the estate is the composition protection. Formulation and method-of-use patents provide incremental protection but are less likely to replicate the economic effect of the original compound patent.
How does XTANDI compare with NUBEQA and ERLEADA?
XTANDI competes directly with NUBEQA, or darolutamide, marketed by Bayer and Orion, and ERLEADA, or apalutamide, marketed by Johnson & Johnson.
| Product |
Active ingredient |
Originator |
Main competitive position |
| XTANDI |
Enzalutamide |
Astellas/Pfizer |
Broad prostate-cancer label and established use |
| NUBEQA |
Darolutamide |
Bayer/Orion |
Differentiation around safety profile and combination use |
| ERLEADA |
Apalutamide |
Johnson & Johnson |
Strong early-use and mCSPC positioning |
| ZYTIGA |
Abiraterone |
Johnson & Johnson |
Generic competition and low-cost alternative |
| ORGOVYX |
Relugolix |
Myovant/Rigel |
Oral androgen-deprivation therapy |
NUBEQA and ERLEADA can take share from XTANDI before generic entry through physician preference, safety considerations, combination regimens, payer contracting, and treatment sequencing. Generic abiraterone imposes price pressure, although it is not a direct pharmacologic substitute in every clinical setting.
NUBEQA has commercial importance because Bayer has expanded its prostate-cancer use and has pursued combination strategies. ERLEADA benefits from Johnson & Johnson’s oncology infrastructure and broad prostate-cancer commercial reach. XTANDI retains advantages from long clinical experience, global availability, and a mature evidence base.
What is the FDA regulatory status of XTANDI?
XTANDI is fully FDA approved for prostate-cancer indications. Its regulatory status is materially different from a product dependent on accelerated approval because the principal indications are supported by randomized clinical development and confirmatory evidence.
The FDA label covers adults with specified forms of prostate cancer, generally in combination with ongoing androgen-deprivation therapy unless patients have undergone bilateral orchiectomy. The label and safety profile include risks such as seizures, falls, fractures, ischemic heart disease, hypertension, and posterior reversible encephalopathy syndrome.
Regulatory risk is lower than patent risk. The principal commercial questions are label durability, competitive clinical data, treatment sequencing, and payer management.
What licensing deals support XTANDI?
The XTANDI commercial model originated from the collaboration between Medivation and Astellas. Pfizer acquired Medivation in 2016 for approximately $14 billion, bringing Pfizer into the XTANDI partnership and U.S. commercial economics (Pfizer, 2016).
The partnership has strategic value because:
- Astellas retains a major global oncology franchise.
- Pfizer contributes U.S. commercialization scale.
- The companies share development and sales economics.
- XTANDI benefits from two global commercial organizations.
- The arrangement reduces the need for one company to independently fund all global commercialization.
No licensing transaction eliminates the underlying patent-expiry risk. The principal value of the collaboration is revenue sharing and market execution rather than extended legal exclusivity.
What revenue exposure exists after generic launch?
A U.S. generic launch could reduce XTANDI revenue through both volume substitution and price compression. The first generic may capture meaningful pharmacy volume, while later entrants typically intensify price competition.
A practical scenario range is:
| Scenario |
Entry pattern |
Revenue impact |
| Delayed entry |
Settlement or litigation delays entry beyond 2027 |
Revenue remains high until entry |
| Single generic |
One approved competitor initially |
Moderate erosion, with pricing pressure |
| Multi-generic launch |
Several challengers enter near expiry |
Rapid share and price loss |
| Authorized generic |
Originator supplies or licenses a generic |
Slower external competition but lower net price |
| Internationally staggered entry |
U.S. expiry precedes foreign expiry |
Global decline is gradual |
The U.S. market is likely to experience the fastest erosion because of ANDA substitution and concentrated payer control. International erosion should be more staggered because patent terms, reimbursement systems, litigation outcomes, and generic approval pathways differ by country.
What manufacturing and intellectual-property barriers remain?
Enzalutamide is a small molecule, so manufacturing does not create the same barrier found with monoclonal antibodies, cell therapies, or complex injectables. Generic manufacturers must still establish:
- Active pharmaceutical ingredient supply.
- Consistent impurity control.
- Bioequivalent finished dosage forms.
- Adequate tablet or capsule manufacturing capacity.
- Regulatory-compliant packaging and distribution.
- Commercial supply at oncology-market scale.
The active ingredient’s chemical synthesis and formulation may require specialized process controls, but those requirements are unlikely to prevent well-capitalized generic manufacturers from entering once patent barriers fall.
Key Takeaways
- XTANDI is a multibillion-dollar enzalutamide franchise marketed by Astellas and Pfizer.
- Revenue growth has matured after major label expansions into nmCRPC and mCSPC.
- The principal U.S. composition patent, U.S. Patent No. 7,709,517, expires in the September 2027 window.
- Paragraph IV challenges and settlement agreements will determine whether generic entry occurs before or after the nominal expiry date.
- Formulation and method-of-use patents provide additional protection but are less durable than the core composition patent.
- NUBEQA and ERLEADA are the principal branded competitive threats before generic entry.
- Generic abiraterone adds price pressure but is not a complete clinical substitute in every treatment setting.
- U.S. revenue is exposed to rapid erosion after the first commercially effective generic launch.
- International revenue should decline more gradually because patent and reimbursement timing varies by country.
- The franchise’s post-expiry value depends on settlement terms, authorized-generic strategy, tablet lifecycle management, and continued clinical differentiation.
FAQs About XTANDI Patent and Market Risk
When will generic enzalutamide likely enter the U.S. market?
The principal commercial entry window begins around September 2027, subject to Paragraph IV litigation, settlements, court decisions, and any applicable patent-term adjustments or extensions.
Is XTANDI a biologic drug with biosimilar risk?
No. XTANDI is an oral small-molecule drug. Its competitive threat comes from ANDA-approved generics rather than biosimilars.
Can a generic company launch XTANDI before all indications lose patent protection?
Yes. A generic applicant may use a section viii statement or a skinny label that omits patented indications, provided the proposed labeling and product do not unlawfully rely on protected uses.
Which XTANDI formulation is most exposed to generic substitution?
The oral capsule and tablet products are both exposed after relevant patent protection ends. The tablet formulation may provide lifecycle-management value, but it does not create a biologic-style substitution barrier.
What is the largest financial risk to Astellas and Pfizer?
The largest risk is rapid U.S. price and volume erosion after the first effective generic launch. The impact will depend on launch timing, the number of approved manufacturers, settlement restrictions, payer substitution, and whether Astellas supplies an authorized generic.
References
-
Astellas Pharma Inc. (2024). Annual report 2024. https://www.astellas.com/en/investors
-
Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
-
Pfizer Inc. (2016). Pfizer to acquire Medivation for $14 billion. https://www.pfizer.com/news/press-release
-
Pfizer Inc. (2024). 2023 annual report. https://www.pfizer.com/investor-relations/financial
-
U.S. Patent and Trademark Office. (2010). U.S. Patent No. 7,709,517: N-phenyl thiohydantoin compounds. https://patents.google.com/patent/US7709517B2/en