Share This Page
Drug Sales Trends for pantoprazole sodium
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for pantoprazole sodium (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
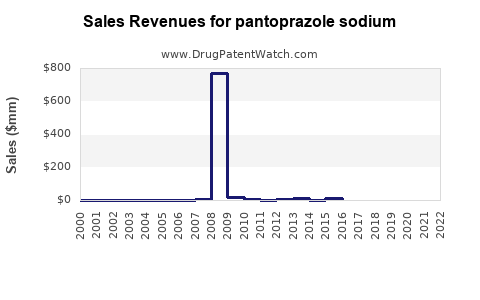
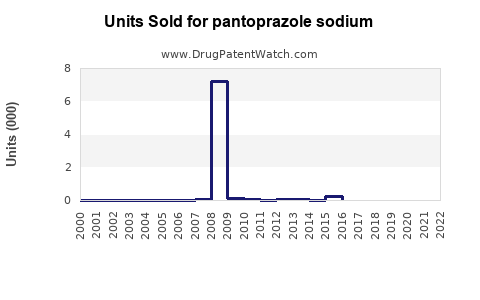
Annual Sales Revenues and Units Sold for pantoprazole sodium
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| PANTOPRAZOLE SODIUM | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| PANTOPRAZOLE SODIUM | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| PANTOPRAZOLE SODIUM | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| PANTOPRAZOLE SODIUM | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| PANTOPRAZOLE SODIUM | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| PANTOPRAZOLE SODIUM | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| PANTOPRAZOLE SODIUM | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Pantoprazole Sodium Market Analysis and Sales Projections
Pantoprazole sodium is a mature proton-pump inhibitor with broad generic availability, low unit pricing, and stable demand in gastroesophageal reflux disease, erosive esophagitis, peptic ulcer disease, and hospital acid-suppression protocols. Commercial growth is limited. The strongest opportunities are in high-volume generic tablets, injectable hospital supply, private-label products, and markets where branded or semi-branded pricing persists.
What is the current market position of pantoprazole sodium?
Pantoprazole sodium is marketed primarily as:
- Delayed-release tablets, commonly 20 mg and 40 mg
- Delayed-release oral granules in selected markets
- Intravenous products, commonly 40 mg vials
- Generic and private-label products
- Branded or licensed products, including Protonix and regional brands
The drug is approved for acid-related disorders and is available through prescription channels in the United States. Protonix was originally commercialized by Wyeth and later held by Pfizer after the Wyeth acquisition. The U.S. market has shifted from branded Protonix to generic pantoprazole sodium supplied by multiple manufacturers.
Pantoprazole competes with omeprazole, esomeprazole, lansoprazole, rabeprazole, and vonoprazan. Its clinical differentiation is limited, but physicians and hospitals continue to use it because of established efficacy, intravenous availability, formulary familiarity, and broad generic supply.
How large is the pantoprazole sodium market?
No single public source reports a complete global market total covering prescription, hospital, private-label, and country-specific generic sales. A practical commercial estimate is best built from prescription volume, hospital utilization, dosage form, and net price.
Modeled global market range
| Segment | Estimated 2024 net sales range | Five-year outlook |
|---|---|---|
| Oral generic pantoprazole | $450 million-$750 million | Flat to low-single-digit decline |
| Intravenous pantoprazole | $250 million-$500 million | Low-single-digit growth in emerging markets |
| Branded and semi-branded products | $150 million-$350 million | Decline in mature markets |
| Consumer and private-label channels | $100 million-$250 million | Low-single-digit growth |
| Total modeled market | $950 million-$1.85 billion | Approximately -2% to +2% CAGR |
These figures are modeled commercial ranges rather than audited market totals. They reflect the drug's mature generic status, relatively low prices, and continued use in hospitals and developing markets.
The United States is a high-volume but low-value market. Western Europe also has substantial volume, but reimbursement controls and generic substitution constrain revenue. India, China, Latin America, Southeast Asia, and the Middle East provide more growth potential through population expansion, private-label products, and branded generics.
What are the main commercial uses of pantoprazole?
Pantoprazole is used for the following indications:
| Indication | Commercial relevance |
|---|---|
| Gastroesophageal reflux disease | Largest chronic outpatient use |
| Erosive esophagitis | Supports prescription and specialist use |
| Peptic ulcer disease | Stable, often combination-based demand |
| Helicobacter pylori regimens | Competitive and price-sensitive use |
| Zollinger-Ellison syndrome | Small-volume specialty indication |
| Stress-ulcer prophylaxis | Important hospital and intensive-care use |
| Upper gastrointestinal bleeding protocols | Supports intravenous demand |
Chronic outpatient treatment generates recurring tablet volume. Hospital use is more important for intravenous products, particularly where oral administration is not possible or where local protocols favor parenteral acid suppression.
The clinical market is under pressure from shorter treatment durations, deprescribing initiatives, concerns about unnecessary long-term PPI use, and substitution by lower-cost omeprazole. Hospital demand remains more resilient than chronic outpatient demand because pantoprazole is embedded in treatment protocols.
What are the sales projections for pantoprazole sodium?
Base-case projection
The following projection uses a modeled 2024 global market midpoint of $1.35 billion and assumes continued generic price pressure, stable prescription volume, modest hospital growth, and limited branded-price retention.
| Year | Base-case market value | Growth versus prior year |
|---|---|---|
| 2024 | $1.35 billion | Reference year |
| 2025 | $1.34 billion | -0.7% |
| 2026 | $1.33 billion | -0.7% |
| 2027 | $1.34 billion | +0.8% |
| 2028 | $1.35 billion | +0.7% |
| 2029 | $1.36 billion | +0.7% |
The base case implies approximately 0% to 1% annual growth over five years. Revenue is expected to remain broadly stable because volume growth in emerging markets offsets falling prices in mature markets.
Scenario analysis
| Scenario | 2029 market value | Implied 2024-2029 CAGR | Key assumptions |
|---|---|---|---|
| Downside | $1.00 billion-$1.15 billion | -6% to -3% | Faster generic price erosion, lower chronic use, hospital tender losses |
| Base case | $1.30 billion-$1.45 billion | -1% to +1% | Stable volume, moderate emerging-market growth |
| Upside | $1.60 billion-$1.85 billion | +3% to +6% | Higher injectable demand, branded-generic expansion, supply disruptions |
The downside case is more likely in the United States and Western Europe. The upside case depends on volume growth, not breakthrough pricing. Pantoprazole has limited ability to support premium prices without differentiated packaging, combination products, or reliable hospital supply.
Which regions offer the strongest growth potential?
United States
The U.S. market is mature and highly genericized. Oral pantoprazole is subject to pharmacy benefit substitution and manufacturer price competition. Intravenous products can produce better margins, but hospital group purchasing organizations and tenders exert significant pricing pressure.
The primary commercial opportunities are:
- Authorized generic and private-label supply
- Hospital injectable contracts
- Consistent supply during competitor shortages
- Niche dosage strengths and packaging configurations
- Specialty pharmacy distribution where applicable
Europe
European markets have high generic penetration and strong government price controls. Germany, France, Italy, Spain, and the United Kingdom provide substantial volume but limited margin expansion. Tender access, reference pricing, and local reimbursement rules are more important than brand recognition.
India
India supports a large branded-generic market. Pantoprazole is often sold under multiple physician-promoted brands, including fixed-dose combinations with domperidone or other agents. The market offers volume and brand-building potential, but competition is intense and regulatory scrutiny of combinations is material.
China
China has substantial demand but increasingly stringent centralized procurement and volume-based purchasing. Injectable and oral products can face sharp price reductions after procurement inclusion. Manufacturers with domestic production, regulatory registrations, and reliable government-tender access have the strongest position.
Latin America and Southeast Asia
These regions offer moderate growth through private-sector prescribing, branded generics, and expanding healthcare access. Currency volatility, registration requirements, and distributor dependence can reduce realized margins.
How does pantoprazole compare with competing proton-pump inhibitors?
| Drug | Market position | Price pressure | Differentiation |
|---|---|---|---|
| Omeprazole | Largest and most established generic competitor | Very high | Low |
| Esomeprazole | Strong branded and generic presence | High | Some efficacy and formulation positioning |
| Lansoprazole | Mature generic product | High | Low |
| Rabeprazole | Smaller but established market | Moderate to high | Physician familiarity and onset claims |
| Pantoprazole | Strong hospital and prescription generic position | High | IV availability and formulary acceptance |
| Vonoprazan | Newer potassium-competitive acid blocker | Lower initially | New mechanism and potential efficacy advantage |
Pantoprazole's most defensible commercial position is not broad outpatient differentiation. It is the combination of established physician use, intravenous availability, hospital formulary presence, and reliable generic supply.
Vonoprazan is the main longer-term therapeutic threat where approved and reimbursed. It may capture patients requiring stronger or faster acid suppression, but its higher price and different regulatory status limit immediate substitution across the full pantoprazole market.
What FDA regulatory status applies to pantoprazole sodium?
Pantoprazole sodium is an FDA-approved active pharmaceutical ingredient used in prescription delayed-release and injectable products. Generic tablets and injectable products are approved through abbreviated new drug applications under Section 505(j) of the Federal Food, Drug, and Cosmetic Act.
The reference listed drug for the U.S. oral product is Protonix delayed-release tablets. FDA labeling identifies pantoprazole sodium as a proton-pump inhibitor that suppresses gastric acid secretion through irreversible inhibition of the gastric H+/K+-ATPase enzyme system. [1]
Generic manufacturers must demonstrate pharmaceutical equivalence and bioequivalence or satisfy applicable requirements for the injectable product. Product quality, enteric protection, dissolution, stability, and manufacturing controls are central regulatory issues for oral delayed-release dosage forms.
What is the Orange Book status of pantoprazole sodium?
Pantoprazole products are listed in the FDA Orange Book through reference and generic entries. The original Protonix patent and regulatory exclusivity periods have expired, and the U.S. market has long supported generic competition. Current commercial risk does not center on a basic compound patent blocking generic entry.
Orange Book considerations remain relevant for:
- Listed formulation patents
- Method-of-use patents
- Pediatric exclusivity history
- Patent certifications in abbreviated new drug applications
- Product-specific litigation involving later-filed patents
For a current product-by-product patent certification analysis, the relevant FDA Orange Book entries must be reviewed against each approved reference and generic product. [2]
When did pantoprazole lose exclusivity?
U.S. basic market exclusivity for Protonix expired in the early 2010s. Protonix had compound and formulation-related patent litigation before generic entry. Teva and other manufacturers entered after patent disputes and settlements involving Wyeth and related parties.
The commercial effect was significant:
- Branded Protonix revenue declined after generic launch
- Generic suppliers gained pharmacy volume
- Average selling prices fell sharply
- Hospital injectable products retained a more favorable margin profile than oral tablets
Because pantoprazole has been generic for more than a decade, future revenue is primarily a manufacturing and distribution issue rather than an innovator-exclusivity issue.
Are there current Paragraph IV risks for pantoprazole?
Paragraph IV litigation risk is limited for the core pantoprazole market because the primary patents covering the mature product have expired. New Paragraph IV activity could arise around:
- Modified-release systems
- New strengths or dosage forms
- Combination products
- Pediatric formulations
- Hospital-use delivery systems
- New indications or administration protocols
A conventional abbreviated new drug application for standard pantoprazole delayed-release tablets is unlikely to face a meaningful blocking patent estate where the relevant Orange Book patents have expired. The principal risks are regulatory deficiencies, manufacturing observations, product recalls, and supply competition.
What manufacturing and intellectual-property barriers remain?
Pantoprazole is technically mature, but manufacturing quality remains commercially important. Key barriers include:
- Control of degradation products
- Enteric-coating performance
- Dissolution and bioequivalence consistency
- API impurity control
- Injectable sterility and particulate control
- Stability under temperature and humidity stress
- Reliable supply of API and packaging components
The drug is acid-sensitive and requires appropriate formulation protection. Manufacturing failures can lead to recalls, supply interruptions, and loss of hospital contracts even when intellectual-property protection is weak.
The most valuable operational assets are often FDA-compliant manufacturing capacity, validated processes, regulatory registrations, and a dependable supply chain rather than patents.
Which companies compete in pantoprazole sodium?
The competitive field includes originator-linked suppliers, multinational generic companies, regional branded-generic manufacturers, and contract manufacturers. Depending on country, competitors may include:
- Viatris
- Teva Pharmaceuticals
- Dr. Reddy's Laboratories
- Sandoz
- Lupin
- Sun Pharmaceutical Industries
- Cipla
- Torrent Pharmaceuticals
- Zydus Lifesciences
- Hikma Pharmaceuticals
- Fresenius Kabi
- Aurobindo Pharma
- Pfizer and legacy Protonix-related channels
Market shares vary substantially by country and dosage form. Injectable competition is more concentrated than tablet competition because sterile manufacturing, regulatory compliance, and hospital procurement requirements create higher entry barriers.
What are the main sales risks?
The largest risks are generic price erosion, substitution by omeprazole or esomeprazole, reductions in unnecessary PPI prescribing, hospital tender losses, and manufacturing interruptions.
Commercial upside is concentrated in:
- Injectable hospital products
- Emerging-market branded generics
- Private-label pharmacy supply
- Combination products where legally permitted
- Supply-constrained markets
- Contract manufacturing and API supply
A company evaluating pantoprazole should prioritize cost position, regulatory execution, sterile capacity, tender access, and supply reliability. Patent ownership alone provides little strategic value for the standard molecule.
Key Takeaways
- Pantoprazole sodium is a mature, genericized proton-pump inhibitor with approximately $950 million-$1.85 billion in modeled global annual sales.
- The base-case market is broadly stable through 2029, with a modeled CAGR near 0% to 1%.
- Oral products face severe price competition and limited differentiation.
- Intravenous pantoprazole has stronger commercial durability because of hospital use and higher manufacturing barriers.
- U.S. basic exclusivity and core patent protection have expired; current Paragraph IV risk is limited for conventional products.
- Emerging markets provide the clearest volume growth, while the United States and Europe offer scale but limited pricing power.
- The best commercial strategy is based on cost-efficient production, reliable supply, regulatory registrations, and hospital contracting.
FAQs
Is pantoprazole sodium still commercially attractive?
Yes, but primarily as a high-volume generic, injectable hospital product, private-label product, or branded generic. It is not an attractive conventional innovation asset because core exclusivity has expired.
What is the most profitable pantoprazole dosage form?
Intravenous pantoprazole generally has better margin potential than standard tablets because sterile manufacturing and hospital procurement create higher entry barriers. Actual profitability depends on tender pricing and plant utilization.
Can a new pantoprazole formulation obtain patent protection?
A new formulation may obtain patent protection if it demonstrates novelty, non-obviousness, and utility. Potential targets include modified release, improved stability, pediatric delivery, combination therapy, or a differentiated injectable system.
Does pantoprazole compete directly with vonoprazan?
Yes. Both are acid-suppression therapies, but vonoprazan has a different mechanism and may compete more strongly in patients requiring potent or rapid acid control. Pantoprazole retains an advantage in generic price and established hospital use.
What is the outlook for pantoprazole API suppliers?
API demand should remain stable, but pricing will stay competitive. Suppliers with regulatory approvals, multi-region registrations, impurity-control capabilities, and reliable delivery should outperform low-cost suppliers that lack quality-system resilience.
References
-
U.S. Food and Drug Administration. (2024). Protonix (pantoprazole sodium) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. FDA.
-
Pfizer Inc. (2009). Annual report 2009. Pfizer.
-
U.S. Food and Drug Administration. (2024). Guidance for industry: Bioavailability and bioequivalence studies submitted in ANDAs. FDA.
More… ↓
