Drug Sales Trends for nicotine polacrilex
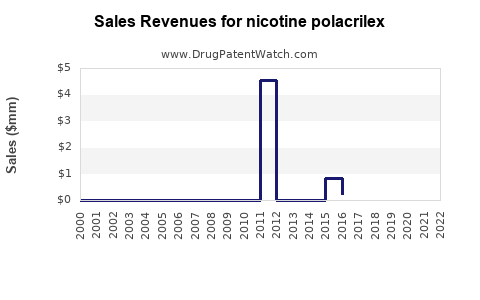
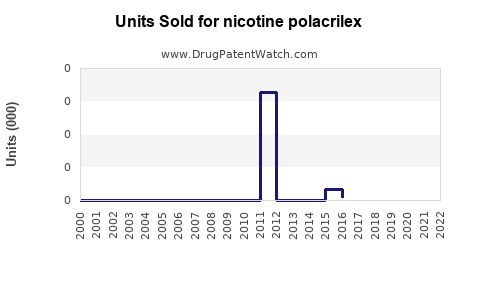
Annual Sales Revenues and Units Sold for nicotine polacrilex
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| NICOTINE POLACRILEX | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| NICOTINE POLACRILEX | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| NICOTINE POLACRILEX | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| NICOTINE POLACRILEX | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Nicotine Polacrilex Market Analysis and Sales Projections
Nicotine polacrilex is an established nicotine-replacement therapy ingredient used primarily in chewing gum and lozenges. The market is mature, highly genericized, and concentrated in over-the-counter products such as Nicorette and store-brand equivalents. Growth is likely to come from pricing, online distribution, switching from combustible tobacco, and demand for nonprescription cessation products rather than from new patent exclusivity.
Public companies generally do not report nicotine-polacrilex revenue separately. Sales are usually combined with nicotine patches, sprays, smoking-cessation portfolios, or broader consumer-health businesses. A product-specific forecast therefore requires a market model based on retail sales, market share, smoking prevalence, and substitution among nicotine products.
What is nicotine polacrilex and how is it used?
Nicotine polacrilex is an ion-exchange resin complex that releases nicotine in the mouth. It is used in nicotine gum and lozenges to reduce withdrawal symptoms associated with smoking cessation.
The principal dosage forms are:
| Dosage form | Typical strengths | Primary use |
|---|---|---|
| Chewing gum | 2 mg and 4 mg nicotine | Intermittent craving control |
| Lozenge | 2 mg and 4 mg nicotine | Intermittent craving control |
| Mini-lozenge | 2 mg and 4 mg nicotine | Faster-dissolving oral delivery |
| Combination therapy | Gum or lozenge with patch | Baseline nicotine plus breakthrough-craving control |
Nicotine polacrilex products are sold under brand, authorized-generic, and store-brand labels. The leading brand is Nicorette, marketed globally by Haleon and its local commercial partners. Other products are sold by Perrigo, Dr. Reddy's Laboratories, Walgreens, CVS, Walmart, Rite Aid, and private-label manufacturers, depending on country.
The products are generally used over an eight- to twelve-week cessation program, with dosage gradually reduced. In the United States, many products are available without a prescription under the FDA's over-the-counter nicotine-replacement framework.[1]
How large is the nicotine polacrilex market?
A precise global nicotine-polacrilex market size is not publicly disclosed. Commercial market reports often combine nicotine gum and lozenges with patches, sprays, inhalers, prescription smoking-cessation medicines, and sometimes nicotine pouches. Those categories have different pricing, margins, regulatory status, and consumer behavior.
The addressable market can be divided into four segments:
- Branded nicotine gum and lozenges.
- Private-label and store-brand products.
- Institutional and government cessation programs.
- E-commerce and subscription-based smoking-cessation sales.
Nicotine gum and lozenges remain important because they are portable, nonprescription, and usable on demand. Their market position is weaker than it was before the expansion of nicotine pouches, vaping products, and digital cessation programs.
Key demand drivers
Demand is linked to:
- The number of smokers attempting to quit.
- Insurance coverage and government reimbursement.
- OTC availability and pharmacy distribution.
- Consumer preference for oral nicotine delivery.
- Relative pricing versus nicotine pouches and vaping products.
- Public-health campaigns and tobacco-control regulation.
- Retail shelf placement and online search visibility.
- Availability of combination therapy with nicotine patches.
The Centers for Disease Control and Prevention estimates that millions of U.S. adults smoke cigarettes, while a substantial proportion attempt to quit each year.[2] That creates recurring demand, but many consumers use nicotine-replacement therapy for only a limited period. Repeat purchases depend on relapse, multiple quit attempts, or continued use beyond the recommended cessation period.
What companies sell nicotine polacrilex products?
Haleon and Nicorette
Haleon's Nicorette franchise is the best-known branded nicotine-replacement business. Nicorette products include gum, lozenges, sprays, patches, and other delivery systems, depending on market. Haleon reports nicotine-replacement products within broader consumer-health categories rather than providing a complete nicotine-polacrilex revenue breakout.[3]
Nicorette has advantages in brand recognition, pharmacy distribution, product breadth, and physician familiarity. Its disadvantages are higher pricing than store brands and exposure to substitution by lower-cost generics and nicotine pouches.
Perrigo
Perrigo supplies consumer-health products and private-label OTC medicines. Its nicotine-replacement business includes store-brand and retailer-branded products in selected markets. Private-label products compete primarily on price and retailer access.
Retailer and generic manufacturers
Major pharmacy and mass-retail chains sell nicotine gum and lozenges under their own labels. Generic competition limits pricing power and reduces the commercial value of formulation differentiation.
Other competitors
The broader smoking-cessation market includes:
- Transdermal nicotine patches.
- Nicotine nasal sprays and oral inhalers.
- Varenicline.
- Bupropion.
- Nicotine pouches.
- Electronic cigarettes and heated-tobacco products.
- Digital cessation services.
Nicotine pouches are the most direct commercial substitute in the oral nicotine category, although they are generally marketed for nicotine consumption rather than FDA-approved smoking cessation in the United States. This distinction affects regulatory positioning and consumer claims.
What is the FDA regulatory status of nicotine polacrilex?
Nicotine polacrilex gum and lozenges are regulated as OTC smoking-cessation products in the United States. FDA labeling establishes the permitted uses, strength formats, warnings, directions, and age restrictions.[1]
The FDA has authorized nicotine-replacement products through OTC drug pathways, including applications and monograph-based compliance depending on the product and labeling configuration. The commercial market includes approved branded products, authorized generics, and private-label products manufactured under applicable FDA requirements.
Nicotine polacrilex is not a biologic and does not create biosimilar risk. The relevant competitive risks are generic substitution, private-label entry, formulation replication, manufacturing compliance, and consumer migration to alternative nicotine products.
Orange Book status
The Orange Book is relevant primarily to FDA-approved drug applications. OTC nicotine gum and lozenges are not protected by a single, commercially decisive Orange Book patent estate comparable to patented prescription drugs.
Where an individual product is approved through a prescription or supplemental application pathway, application-specific listings may exist. For the broader OTC market, commercial exclusivity is driven mainly by brand equity, retail distribution, manufacturing scale, trademarks, formulation know-how, and regulatory compliance.
What patents protect nicotine polacrilex products?
The core nicotine-polacrilex technology is old and broadly commoditized. Patent protection for the original resin complex, basic nicotine gum, and conventional lozenge concepts is generally expired or commercially weak.
Current protection can arise from:
- Specific gum-base compositions.
- Flavor systems and taste-masking agents.
- Lozenge hardness and dissolution profiles.
- Packaging that limits moisture or nicotine loss.
- Manufacturing processes.
- Combination products.
- Novel dosage regimens.
- Device or delivery-system claims.
- Trademarks and trade dress.
Formulation patents
Formulation patents may cover the physical composition of the gum or lozenge, including resin particle size, excipient selection, sweeteners, pH modifiers, flavor systems, and release characteristics. These patents can delay direct copying of a particular commercial formulation, but they usually do not prevent competitors from selling nicotine polacrilex products using different excipients or manufacturing parameters.
Method-of-use patents
Method-of-use protection is limited because the principal use, smoking cessation, is well established. New claims could target specific dosing schedules, combination therapy, or populations, but the practical enforceability and commercial value of such claims are generally lower than for a new prescription medicine.
Manufacturing and quality barriers
The most durable barriers are operational rather than patent-based:
- Consistent nicotine loading.
- Control of nicotine release.
- Taste masking.
- Gum texture and lozenge dissolution.
- Stability and moisture control.
- Scale-up validation.
- Batch-to-batch uniformity.
- Compliance with FDA current good manufacturing practices.
- Supply of pharmaceutical-grade nicotine and resin intermediates.
These barriers support incumbent participation but do not prevent entry by established OTC manufacturers.
When does nicotine polacrilex lose exclusivity?
Nicotine polacrilex has already lost meaningful molecule-level exclusivity. The active ingredient and basic dosage forms are mature. Individual products may have continuing protection through trademarks, formulation patents, packaging rights, regulatory exclusivity, or private commercial agreements, but those rights do not create broad market exclusivity for nicotine gum or lozenges.
The relevant commercial timeline is therefore:
| Period | Market condition |
|---|---|
| 1980s-1990s | Development and expansion of nicotine-replacement therapy |
| 1990s-2000s | Brand growth and increasing OTC adoption |
| 2000s-2010s | Generic and private-label expansion |
| 2010s-2020s | Competition from vaping, nicotine pouches, and digital cessation |
| 2025 onward | Mature category with selective growth in online and combination therapy |
There is no widely recognized upcoming patent cliff that would materially change the entire nicotine-polacrilex market.
Which companies are challenging nicotine polacrilex products?
Competition is fragmented rather than centered on Paragraph IV litigation. Generic and private-label manufacturers challenge branded products through price, retailer contracts, and alternative formulations.
The main competitive groups are:
| Competitive group | Competitive method |
|---|---|
| Haleon | Brand, distribution, broad cessation portfolio |
| Perrigo | Private label, OTC manufacturing, retailer relationships |
| Pharmacy chains | Store-brand pricing and shelf access |
| Online retailers | Convenience, price comparison, subscription sales |
| Nicotine-pouch companies | Oral nicotine substitution |
| Prescription-drug companies | Varenicline and bupropion |
| Digital health providers | Coaching, adherence, and cessation programs |
Paragraph IV challenges are not the primary market mechanism because the foundational nicotine-polacrilex products are largely mature OTC products rather than high-value, patent-protected prescription products.
What is the competitive outlook versus nicotine patches and nicotine pouches?
Nicotine gum and lozenges versus patches
Patches provide steady nicotine exposure and are often used as the baseline component of combination therapy. Gum and lozenges provide flexible dosing for acute cravings.
| Factor | Gum or lozenge | Patch |
|---|---|---|
| Dosing | Intermittent | Continuous |
| Consumer control | High | Moderate |
| Main limitation | Taste, chewing technique, frequent dosing | Skin irritation, fixed exposure |
| Combination use | Often paired with patch | Often paired with gum or lozenge |
| Price competition | High | High |
| Product differentiation | Moderate | Low to moderate |
Nicotine gum and lozenges versus nicotine pouches
Nicotine pouches compete for consumers seeking discreet, oral nicotine delivery. Pouches generally have stronger appeal among consumers who are not actively following a smoking-cessation program. Nicotine gum and lozenges retain an advantage in FDA-recognized cessation positioning and pharmacy credibility.
The outcome depends on whether the consumer prioritizes cessation labeling, taste, discretion, nicotine intensity, convenience, or price. Regulatory treatment remains a major differentiator.
What are the nicotine polacrilex sales projections?
Because company filings do not isolate nicotine-polacrilex revenue, a product-specific projection is best presented as an indexed scenario model. The following model uses 2024 sales as an index of 100 for branded and generic nicotine gum and lozenge products combined.
| Scenario | 2025 | 2026 | 2027 | 2028 | 2029 | Implied 2024-2029 CAGR |
|---|---|---|---|---|---|---|
| Downside | 96 | 92 | 88 | 84 | 80 | -4.4% |
| Base case | 102 | 104 | 106 | 108 | 110 | 1.9% |
| Upside | 106 | 112 | 119 | 126 | 134 | 6.0% |
Base-case assumptions
The base case assumes:
- Unit demand remains broadly stable.
- Retail price increases offset part of volume erosion.
- Nicotine pouches take share from some oral nicotine consumers.
- Smoking-cessation demand remains supported by public-health programs.
- Online sales grow faster than traditional pharmacy sales.
- Generic and private-label products gain modest share.
- Combination therapy supports lozenge and gum utilization.
Under this model, nominal sales rise modestly through 2029, while unit volumes are flat to slightly negative. The category is more likely to produce low-single-digit revenue growth than prescription-drug-style expansion.
Downside scenario
The downside case reflects faster migration to nicotine pouches, lower smoking prevalence, reduced cessation-program funding, and intensified private-label pricing. Under that scenario, nicotine-polacrilex sales decline about 4% annually.
Upside scenario
The upside case assumes stronger tobacco-control measures, expanded reimbursement, improved digital cessation referrals, and greater use of combination therapy. It also assumes brand manufacturers defend retail distribution successfully.
What revenue exposure do manufacturers have?
Revenue exposure is highest for companies with dedicated nicotine-replacement brands, but public disclosure remains limited.
| Company type | Exposure to nicotine polacrilex | Main risk |
|---|---|---|
| Branded consumer-health company | Moderate within a broader portfolio | Brand switching and pouch substitution |
| OTC manufacturer | Moderate to high by product contract | Price compression |
| Retailer | Low direct manufacturing exposure | Category margin erosion |
| Nicotine-pouch company | Indirect substitution exposure | Regulatory restrictions |
| Pharmaceutical company | Low unless selling cessation medicines | Physician and payer preference |
Haleon has the clearest strategic exposure through Nicorette, but the company's overall revenue is diversified across oral health, pain relief, respiratory health, and other consumer-health products.[3] Nicotine polacrilex is therefore unlikely to be a company-level earnings driver on its own, although it can matter to brand-level portfolio decisions.
What generic launch risks exist?
Generic entry is already a structural feature of the category. The principal risks to an incumbent brand are:
- Retailer conversion to private label.
- Price reductions by generic suppliers.
- Online discounting.
- Substitution by nicotine pouches.
- Reduced consumer adherence to formal cessation regimens.
- Retail shelf-space reallocation toward higher-growth nicotine products.
- Manufacturing recalls or supply interruptions.
A new entrant with FDA-compliant manufacturing, stable nicotine release, acceptable taste, and national retail access could enter without overcoming a major active-ingredient patent barrier.
How strong is the nicotine-polacrilex patent estate?
The patent estate is weak at the molecule and basic dosage-form level and moderate at the product-formulation and manufacturing levels. Brand strength, retailer access, regulatory compliance, and consumer trust are more important than patent exclusion.
| Protection layer | Strength |
|---|---|
| Active ingredient | Low |
| Basic gum or lozenge concept | Low |
| Specific formulation | Low to moderate |
| Manufacturing process | Moderate |
| Trademark and trade dress | Moderate to strong |
| Retail distribution | Moderate |
| Regulatory know-how | Moderate |
| Biosimilar protection | Not applicable |
What litigation and settlement risks affect the market?
Large-scale patent litigation is less likely than in innovative prescription pharmaceuticals. Litigation risk is more likely to involve:
- Trademark infringement.
- False or misleading cessation claims.
- Product liability.
- Manufacturing defects.
- Advertising practices.
- Retailer and supplier disputes.
- Regulatory noncompliance.
- Competition involving nicotine pouches or vaping products.
Settlement agreements involving Paragraph IV challenges are not a central feature of the nicotine-polacrilex market. Commercial settlements, supply agreements, retailer contracts, and private-label manufacturing arrangements are more relevant to market access.
Key Takeaways
- Nicotine polacrilex is a mature OTC nicotine-replacement ingredient used mainly in gum and lozenges.
- Nicorette is the leading global brand, with Haleon holding the strongest commercial position.
- Product-specific revenue is not generally reported separately by manufacturers.
- Molecule-level and basic dosage-form patent protection is largely exhausted.
- Formulation, manufacturing, trademark, and distribution rights provide the main competitive barriers.
- Generic and private-label competition is already established.
- Nicotine pouches are the most important emerging substitute for oral nicotine products.
- A reasonable base case is low-single-digit annual nominal sales growth through 2029, with flat or declining unit volume.
- The category has limited Paragraph IV and biosimilar risk.
- Commercial execution matters more than patent exclusivity.
FAQs
Is nicotine polacrilex the same as nicotine salt?
No. Nicotine polacrilex is a nicotine-resin complex used to control nicotine release in oral products. Nicotine salts are nicotine combined with an acid, commonly used in some vaping products and oral nicotine products.
Who owns the Nicorette brand?
Haleon owns and markets the Nicorette brand in major markets, subject to local registrations, licensing arrangements, and distribution structures.[3]
Are nicotine-polacrilex products prescription drugs?
Many nicotine gum and lozenge products are available over the counter in the United States. Product status varies by country and by formulation.
Can nicotine polacrilex be used in combination with a patch?
Yes. FDA-approved labeling and clinical practice support the use of short-acting nicotine-replacement products with patches in appropriate cessation regimens.[1]
Will nicotine pouches eliminate demand for nicotine gum and lozenges?
No. Nicotine pouches may reduce demand among consumers seeking discreet oral nicotine, but nicotine gum and lozenges retain regulatory recognition for smoking cessation and remain relevant in pharmacies, public-health programs, and combination therapy.
References
-
U.S. Food and Drug Administration. (2024). Nicotine replacement therapy products. https://www.fda.gov/drugs/postmarket-drug-safety-information-patients-and-providers/nicotine-replacement-therapy-products
-
Centers for Disease Control and Prevention. (2024). Smoking cessation: Fast facts. https://www.cdc.gov/tobacco/data_statistics/fact_sheets/cessation/
-
Haleon plc. (2024). Annual report and financial statements 2023. https://www.haleon.com/investors/annual-report
-
World Health Organization. (2023). WHO report on the global tobacco epidemic 2023. https://www.who.int/teams/health-promotion/tobacco-control/who-report-on-the-global-tobacco-epidemic-2023
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/ index.cfm
More… ↓
