Share This Page
Drug Sales Trends for ZESTORETIC
✉ Email this page to a colleague
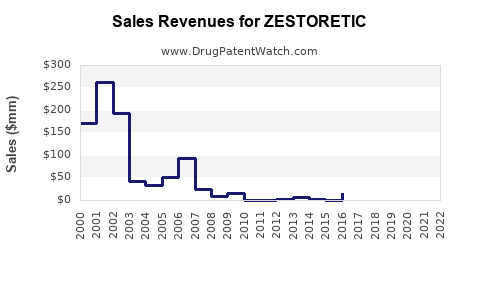
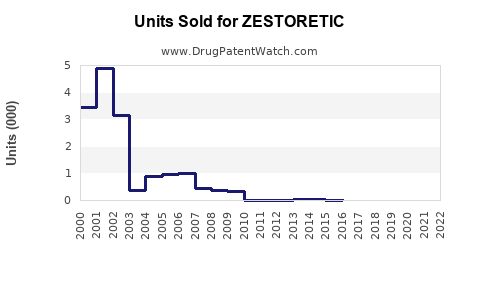
Annual Sales Revenues and Units Sold for ZESTORETIC
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ZESTORETIC | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ZESTORETIC | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ZESTORETIC | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ZESTORETIC | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ZESTORETIC | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ZESTORETIC | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Zestoretic Market Analysis, Sales Projections, Patent Status, and Competitive Outlook
Zestoretic is the fixed-dose combination of lisinopril and hydrochlorothiazide (HCTZ) for hypertension. Its U.S. brand franchise has limited commercial value because the underlying active ingredients and combination are long off-patent. Current demand is driven by generic lisinopril/HCTZ products, Medicaid and Medicare utilization, retail pharmacy substitution, and low-cost hypertension treatment protocols. The brand itself is unlikely to generate material U.S. revenue unless supported by a niche cash-pay, international, or co-branded strategy.
Public sources do not disclose current Zestoretic brand sales as a standalone product. The projections below therefore estimate the broader U.S. lisinopril/HCTZ market under explicit unit and price assumptions rather than presenting unverified brand revenue.
What is Zestoretic and how is it used?
Zestoretic combines the angiotensin-converting enzyme inhibitor lisinopril with the thiazide diuretic hydrochlorothiazide. It is prescribed for hypertension when either component alone does not adequately control blood pressure or when clinicians prefer a fixed-dose combination.
| Product | Strengths | Dosage form | Primary use |
|---|---|---|---|
| Zestoretic | 10 mg/12.5 mg | Tablet | Hypertension |
| Zestoretic | 20 mg/12.5 mg | Tablet | Hypertension |
| Zestoretic | 20 mg/25 mg | Tablet | Hypertension |
| Generic lisinopril/HCTZ | Multiple strengths | Tablet | Hypertension |
The combination has clinical advantages related to adherence and complementary pharmacology. Lisinopril reduces angiotensin-mediated vasoconstriction and aldosterone activity. HCTZ promotes sodium and fluid excretion. The fixed-dose product can reduce pill burden compared with prescribing the two agents separately.
The product is not a high-growth branded medicine. It is a mature, low-price combination used in a large but highly commoditized therapeutic category.
What is the FDA regulatory status of Zestoretic?
The FDA approved Zestoretic as a prescription antihypertensive combination. The product is associated with the lisinopril/HCTZ fixed-dose combination and has been available in the U.S. for decades. Current market access is primarily through generic equivalents rather than a differentiated branded product.
Key regulatory points include:
- Prescription-only status.
- Oral tablet formulation.
- Approved indication for hypertension.
- Generic approval pathway through Abbreviated New Drug Applications.
- No biologic or biosimilar pathway.
- No meaningful regulatory exclusivity remaining for the original brand.
The label contains standard ACE inhibitor warnings, including fetal toxicity, angioedema, hyperkalemia, renal-function concerns, and interactions involving potassium supplements, potassium-sparing diuretics, nonsteroidal anti-inflammatory drugs, and renin-angiotensin system blockers. HCTZ adds risks involving electrolyte imbalance, dehydration, photosensitivity, hyperuricemia, and glucose effects. The FDA labeling remains commercially relevant because generic products must provide equivalent labeling and meet bioequivalence requirements.[1]
What patents protect Zestoretic?
No commercially meaningful U.S. patent barrier is expected to prevent generic competition for Zestoretic.
| IP category | Commercial status |
|---|---|
| Lisinopril compound patent | Expired |
| Hydrochlorothiazide compound protection | Expired |
| Lisinopril/HCTZ combination protection | Expired or no longer commercially blocking |
| Original formulation protection | Expired |
| Method-of-use protection | No known current barrier to routine generic substitution |
| FDA regulatory exclusivity | Expired |
| Orange Book blocking patents | No active exclusivity expected for the legacy brand |
Lisinopril and hydrochlorothiazide are established small-molecule ingredients. Any original compound or combination patents were filed several decades ago and have passed their ordinary patent terms. Patent-term restoration or pediatric exclusivity cannot preserve a meaningful barrier for the current legacy product.
The relevant competitive risk is therefore not a Paragraph IV challenge to an active brand patent. Generic competition is already established. New entrants can seek approval through ANDAs if they satisfy FDA requirements for pharmaceutical equivalence, bioequivalence, manufacturing quality, and labeling.
What is the Orange Book status of Zestoretic?
The Orange Book remains the primary FDA reference for approved drug products, therapeutic equivalence evaluations, and listed patents. For a legacy product such as Zestoretic, the commercial question is whether any unexpired, enforceable patents are listed against the reference product.
The expected Orange Book position is:
- No current patent-based exclusivity that supports premium pricing.
- Generic products listed as therapeutically equivalent where approved.
- No practical ability for the brand holder to prevent substitution based solely on legacy patent rights.
- Any remaining listing, if present, would need to be assessed against its expiration date and enforceability.
An Orange Book listing does not itself create market power after patent expiration. The economic value comes from whether the listed patent blocks ANDA approval or generic launch. For Zestoretic, that blocking value is effectively absent.
When did Zestoretic lose exclusivity?
Zestoretic lost meaningful market exclusivity years ago. The relevant exclusivity periods ended after the expiration of the underlying lisinopril and combination-product patent rights. Generic lisinopril/HCTZ products have been available for many years, and the market now operates under standard generic substitution economics.
A simplified exclusivity timeline is:
| Period | Market event |
|---|---|
| 1980s | Original branded combination introduced and marketed |
| 1990s to early 2000s | Original patent and regulatory protections expired over time |
| Following patent expiry | Generic lisinopril/HCTZ entrants expanded |
| Current market | Generic-dominated, low-price hypertension segment |
No new data exclusivity, orphan-drug exclusivity, pediatric exclusivity, or qualified infectious-disease exclusivity is relevant to Zestoretic.
How large is the lisinopril/HCTZ market?
The market is supported by the prevalence of hypertension, which affects a substantial share of U.S. adults. The Centers for Disease Control and Prevention estimates that nearly half of U.S. adults have hypertension or use antihypertensive medication.[2] Fixed-dose combinations account for a smaller share of antihypertensive prescriptions than monotherapies and some newer combinations, but they remain important in treatment escalation and adherence programs.
Market demand is influenced by:
- Aging populations.
- Higher diagnosis and treatment rates.
- Clinical preference for combination therapy when monotherapy is inadequate.
- Medicare and Medicaid generic utilization.
- Low copay access.
- Pharmacy substitution.
- Continued use in primary care and internal medicine.
The market is constrained by several factors:
- Very low generic prices.
- Substitution by lisinopril alone plus separately prescribed HCTZ.
- Competition from losartan/HCTZ and other angiotensin receptor blocker combinations.
- Greater use of amlodipine-based regimens.
- Guideline-driven use of newer fixed-dose combinations in selected patients.
- Limited ability to differentiate an unprotected tablet.
What are the sales projections for Zestoretic?
The brand and generic markets must be separated. Zestoretic brand sales are likely negligible relative to the total lisinopril/HCTZ market. The broader U.S. market can be modeled using prescription volume and net price rather than historical brand revenue.
Base-case U.S. projection
The following scenario assumes approximately 18 million annual prescriptions for lisinopril/HCTZ across all manufacturers, with a weighted average net revenue of $3.00 to $5.00 per prescription after generic discounts and rebates.
| Year | Estimated prescriptions | Assumed net revenue per prescription | Estimated market revenue |
|---|---|---|---|
| 2025 | 18.0 million | $3.00 | $54 million |
| 2026 | 18.2 million | $3.00 | $55 million |
| 2027 | 18.4 million | $3.00 | $55 million |
| 2028 | 18.5 million | $3.00 | $56 million |
| 2029 | 18.6 million | $3.00 | $56 million |
This represents a volume-growth case with essentially flat real pricing. If the average net price is $5.00, the implied market rises to approximately $90 million to $93 million annually. If average net price falls to $2.00, the market is approximately $36 million to $37 million.
These estimates cover the U.S. generic and branded-equivalent market, not confirmed Zestoretic brand sales. A reasonable standalone brand revenue range is near zero to low single-digit millions annually unless the product has an undisclosed distribution arrangement or retains a material non-U.S. market.
Scenario analysis
| Scenario | Prescription trend | Net price trend | 2029 U.S. market estimate |
|---|---|---|---|
| Downside | Decline from substitution and therapeutic switching | Continued erosion | $30 million-$40 million |
| Base case | Low single-digit volume growth | Stable generic pricing | $55 million-$60 million |
| Upside | Higher fixed-dose use and adherence demand | Limited price stabilization | $85 million-$95 million |
The upside case does not imply strong brand economics. It reflects the total combination market and would still leave manufacturers competing mainly on supply reliability, contracting, and cost.
Which companies compete with Zestoretic?
Competition comes from generic manufacturers and alternative antihypertensive combinations. The principal competitive sets are:
Direct generic competitors
Products labeled as lisinopril/hydrochlorothiazide compete directly with Zestoretic. Generic suppliers typically compete through:
- Wholesale acquisition cost.
- Pharmacy benefit manager contracts.
- Manufacturing reliability.
- National wholesaler coverage.
- Product availability across multiple strengths.
- FDA inspection and compliance record.
Major generic companies that have marketed lisinopril/HCTZ or related antihypertensive products have included Viatris, Teva Pharmaceutical Industries, Lupin, Sandoz, Rising Pharmaceuticals, and other ANDA holders. Product availability changes as suppliers enter, exit, or face manufacturing constraints.
Therapeutic substitutes
| Alternative | Competitive effect |
|---|---|
| Lisinopril monotherapy | Can replace the combination with separate titration |
| HCTZ plus lisinopril prescribed separately | Reduces need for fixed-dose tablets |
| Losartan/HCTZ | Competes where cough or ACE-inhibitor intolerance is a concern |
| Valsartan/HCTZ | Competes in ARB-based treatment |
| Amlodipine combinations | Competes through calcium-channel blocker use |
| Chlorthalidone-based regimens | Competes where longer diuretic action is preferred |
The strongest substitution risk is from separate generic components. Both lisinopril and HCTZ are inexpensive, allowing prescribers to adjust doses independently.
What formulation patents protect Zestoretic?
Zestoretic’s conventional immediate-release tablet has limited formulation differentiation. The commercial product does not depend on an extended-release delivery system, specialty device, depot formulation, or complex manufacturing process.
Potential technical protections in this category could involve:
- Tablet composition.
- Excipient selection.
- Stability.
- Dissolution characteristics.
- Manufacturing controls.
- Packaging.
Those features are unlikely to create a durable barrier for the legacy product. Generic manufacturers can generally develop equivalent immediate-release tablets using established manufacturing processes. Any residual formulation patent would require a specific, unexpired claim covering the marketed product and an enforceable remedy against an ANDA applicant. That condition is not expected to apply to standard Zestoretic tablets.
What generic entry risks exist for Zestoretic?
Generic entry risk is already realized rather than prospective. The principal commercial risks are:
- Further price erosion from additional ANDA suppliers.
- Temporary shortages caused by manufacturing or quality problems.
- Pharmacy substitution away from any remaining branded inventory.
- Contract losses to manufacturers with lower cost structures.
- Declining use of HCTZ in favor of other diuretic strategies.
- Therapeutic substitution into ARB combinations.
- Volume migration to separately prescribed lisinopril and HCTZ.
There is no material biosimilar risk because Zestoretic is a small-molecule tablet, not a biologic. The relevant regulatory pathway is generic approval, not biosimilar interchangeability.
What patent litigation or Paragraph IV activity affects Zestoretic?
No major current patent-litigation threat is expected to affect the legacy Zestoretic franchise. Paragraph IV litigation is typically material when a generic applicant challenges an unexpired Orange Book patent. Zestoretic’s core patent estate is old, and generic competition is already established.
Any future dispute would more likely concern:
- Manufacturing quality.
- Product liability.
- Supply contracts.
- ANDA approval details.
- Labeling or regulatory compliance.
- A newly introduced reformulation, if one were developed.
A settlement agreement would have limited commercial relevance unless it concerned a separately protected reformulation or a new branded combination. No such current product-specific settlement is necessary to explain the market position.
How strong is the Zestoretic patent estate?
The patent estate is weak from a commercial protection perspective.
| Patent-strength factor | Assessment |
|---|---|
| Compound patents | Expired |
| Combination patents | Expired or nonblocking |
| Formulation patents | No material current barrier identified |
| Method-of-use patents | No meaningful exclusivity expected |
| Manufacturing patents | Limited relevance to ordinary generic tablets |
| Regulatory exclusivity | Expired |
| Litigation leverage | Low |
| Ability to sustain premium pricing | Very low |
The asset’s value is operational rather than IP-based. A manufacturer could still derive modest revenue from efficient sourcing, reliable supply, retail distribution, and low-cost production. Those advantages are vulnerable to price competition and have limited transferability.
What licensing deals or commercial partnerships affect Zestoretic?
The original brand history involved commercial activity by the originator and later generic distribution arrangements. Current economic value is more likely to sit with generic supply agreements, wholesaler contracts, private-label arrangements, and pharmacy benefit manager formulary placement than with a high-value licensing deal.
No publicly disclosed, current licensing transaction is required to explain the product’s market performance. A licensee evaluating Zestoretic should focus on:
- Net realized price.
- Annual prescription volume.
- Contract duration.
- Returns and chargebacks.
- Manufacturing cost.
- FDA compliance history.
- Supply continuity.
- Geographic rights.
- Whether the agreement covers brand, generic, or private-label product.
What is the international market outlook for Zestoretic?
International demand may persist in markets where fixed-dose ACE inhibitor/thiazide combinations remain common and generic penetration is incomplete. The economics vary substantially by country.
| Region | Commercial outlook |
|---|---|
| United States | Mature generic market, minimal brand premium |
| European Union | Generic competition and national reimbursement controls |
| Japan | Regulatory and prescribing patterns differ; fixed-dose combinations remain relevant |
| Latin America | Brand and generic coexistence may support higher prices in selected markets |
| Emerging markets | Volume opportunity, but pricing and registration costs constrain returns |
Geographic expansion would require country-specific registrations, local pharmacovigilance, serialization or packaging compliance, and reimbursement access. Patent protection is unlikely to be the primary market-entry obstacle. Regulatory registration and distribution economics are more important.
What are the key investment conclusions for Zestoretic?
Zestoretic is a mature generic-market product, not a conventional branded-growth asset. The best commercial case is based on high prescription volume, manufacturing efficiency, and supply reliability. The weak case is based on brand-led pricing or patent protection.
The product may be commercially rational for a manufacturer that has:
- Existing lisinopril and HCTZ manufacturing capacity.
- Low-cost tablet production.
- Established U.S. wholesaler access.
- A portfolio strategy centered on mature generics.
- Ability to supply all three common strengths.
- International regulatory infrastructure.
It is less attractive for a company seeking:
- Patent-backed pricing power.
- New chemical entity economics.
- Significant U.S. brand revenue.
- Defensible formulation exclusivity.
- Strong licensing leverage.
Key Takeaways
- Zestoretic is lisinopril combined with hydrochlorothiazide for hypertension.
- The U.S. market is generic-dominated and has no meaningful remaining exclusivity.
- The brand is unlikely to generate material standalone revenue.
- The broader U.S. lisinopril/HCTZ market could reasonably range from $30 million to $95 million annually under different volume and net-price assumptions.
- Direct competition comes from generic lisinopril/HCTZ products and separate lisinopril plus HCTZ prescriptions.
- Losartan/HCTZ, valsartan/HCTZ, amlodipine regimens, and chlorthalidone-based therapy are important substitutes.
- Biosimilar risk does not apply.
- Paragraph IV litigation and patent settlements are not central to the current market.
- Commercial value depends on manufacturing cost, supply reliability, contracting, and geographic distribution rather than patent strength.
FAQs
Is Zestoretic still available in the United States?
The active ingredients remain widely available as generic lisinopril/hydrochlorothiazide tablets. Brand availability may vary by wholesaler and pharmacy because generic substitution dominates the market.
Is lisinopril/HCTZ a high-value generic product?
It is a volume product rather than a high-margin product. Value depends on efficient manufacturing, reliable supply, and access to pharmacy and payer contracts.
Does Zestoretic have an active patent?
The original compound and combination protections are decades old. No commercially meaningful active patent barrier is expected to protect ordinary Zestoretic tablets in the United States.
What drug is the closest substitute for Zestoretic?
The closest direct substitute is generic lisinopril/HCTZ. Clinically, separate lisinopril and HCTZ tablets, losartan/HCTZ, valsartan/HCTZ, and other antihypertensive combinations also compete.
Could a new Zestoretic formulation create exclusivity?
A new formulation could potentially support patent protection if it contained a novel, non-obvious, and clinically relevant technical feature. The legacy immediate-release tablet itself does not provide that type of protection.
References
-
U.S. Food and Drug Administration. (2024). Zestoretic: Prescribing information. Drugs@FDA. https://www.accessdata.fda.gov/scripts/cder/daf/
-
Centers for Disease Control and Prevention. (2024). About high blood pressure. https://www.cdc.gov/high-blood-pressure/about/index.html
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
-
U.S. Food and Drug Administration. (2024). ANDA submissions: Abbreviated new drug application process. https://www.fda.gov/drugs/types-applications/abbreviated-new-drug-application-anda
-
Centers for Medicare & Medicaid Services. (2024). Medicare Part D prescription drug event data and utilization information. https://www.cms.gov/medicare/payment/part-d-prescription-drug-coverage/pricing-data-analysis-resources
More… ↓
