Drug Sales Trends for EPIPEN 2-PAK
Payment Methods and Pharmacy Types for EPIPEN 2-PAK (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
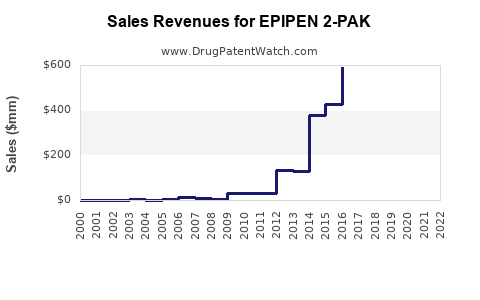
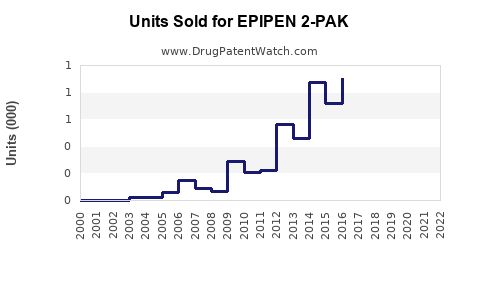
Annual Sales Revenues and Units Sold for EPIPEN 2-PAK
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| EPIPEN 2-PAK | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| EPIPEN 2-PAK | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| EPIPEN 2-PAK | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
EpiPen 2-Pak Market Analysis, Sales Forecast, Patent Position, and Generic Competition
EpiPen 2-Pak is a mature epinephrine auto-injector franchise owned and marketed by Viatris through its Mylan business. U.S. regulatory exclusivity has ended, and generic competitors have been approved. The commercial franchise remains sizable because of repeat prescriptions, school and workplace stocking, payer coverage, patient familiarity, and the clinical need for two devices per prescription.
The base-case outlook is for gradual unit growth but continued net-price pressure. Estimated worldwide EpiPen-branded sales are approximately $250 million to $350 million annually in the mid-2020s, compared with more than $1 billion in the franchise's peak period. A reasonable base-case projection is low-single-digit annual revenue decline through 2028, with downside risk from generic substitution and upside potential from supply disruptions, contracting, and international demand.
What is EpiPen 2-Pak and who markets it?
EpiPen 2-Pak contains two single-use epinephrine auto-injectors. The product is indicated for emergency treatment of severe allergic reactions, including anaphylaxis.
| Product attribute | EpiPen 2-Pak detail |
|---|---|
| Active ingredient | Epinephrine |
| Strengths | 0.15 mg and 0.3 mg |
| Delivery form | Single-use auto-injector |
| Standard package | Two auto-injectors |
| U.S. sponsor | Mylan Specialty L.P., now part of Viatris |
| FDA application | NDA 019430 |
| Original U.S. approval | 1987 |
| Prescription status | Prescription-only |
| Main competitors | Generic EpiPen, Auvi-Q, other epinephrine auto-injectors |
| Regulatory category | Drug-device combination product |
The two-device format is commercially important. Patients, schools, restaurants, airlines, employers, and public venues often purchase multiple two-packs because a second dose may be needed or because devices must be stored at separate locations.
How large is the EpiPen 2-Pak market?
The total epinephrine auto-injector market is substantially larger than the branded EpiPen product. It includes the EpiPen brand, authorized and generic EpiPen products, Auvi-Q, international products, and alternative epinephrine delivery systems.
Public company filings show that EpiPen reached peak annual sales above $1 billion before pricing pressure and generic competition materially reduced revenue. Mylan reported approximately $1.1 billion in EpiPen net sales in fiscal 2016, when the product faced intense public scrutiny over price increases and market access. Revenue subsequently declined as payers, patients, and competitors shifted away from the original branded product (Mylan N.V., 2017).
Key market drivers
Demand is supported by:
- Rising diagnosis of food allergy and anaphylaxis.
- Greater emergency preparedness in schools and workplaces.
- Recommendations that high-risk patients carry two doses.
- Replacement demand caused by expiration dates.
- Increased prescribing for children and adolescents.
- Public access programs for schools and community organizations.
Market pressure comes from:
- Generic EpiPen availability.
- Auvi-Q competition.
- Payer formulary exclusions and preferred-product arrangements.
- Patient abandonment caused by out-of-pocket cost.
- Device expiration and inventory management.
- Substitution from branded to generic products.
EpiPen demand is therefore relatively resilient at the category level but less resilient at the branded-product level.
What are EpiPen 2-Pak sales projections through 2028?
The following projections are analyst estimates for the global EpiPen-branded franchise, not reported Viatris guidance. They assume no major recall, manufacturing interruption, acquisition, or material regulatory change.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 estimated sales | $220 million | $300 million | $380 million |
| 2025 projected sales | $195 million | $288 million | $376 million |
| 2026 projected sales | $172 million | $277 million | $372 million |
| 2027 projected sales | $151 million | $266 million | $368 million |
| 2028 projected sales | $133 million | $255 million | $364 million |
| 2024-2028 CAGR | -11.8% | -4.0% | -1.1% |
Projection assumptions
The base case assumes:
- U.S. branded EpiPen revenue declines approximately 5% annually as generic substitution expands.
- International revenue is more stable because generic penetration and reimbursement systems vary by country.
- Category demand grows approximately 2% annually in units.
- Average selling price declines as payers increase generic utilization.
- EpiPen retains a meaningful share among patients, physicians, schools, and institutions that prefer the established brand.
- Viatris continues marketing and distribution without a major portfolio divestiture.
The bull case assumes persistent supply constraints affecting competitors, stable formulary access, and continued institutional preference for EpiPen. The bear case assumes accelerated generic conversion, lower branded reimbursement, and reduced prescription retention after price-sensitive patients switch.
What is the current FDA status of EpiPen 2-Pak?
EpiPen 2-Pak is an FDA-approved prescription product under NDA 019430. The product is a combination of a drug component, epinephrine, and a delivery-device component, the auto-injector.
The core EpiPen product is not protected by meaningful new-drug exclusivity. Its original approval dates to 1987, and the relevant regulatory exclusivity periods have expired. Later changes to labeling, device design, manufacturing, and strengths do not recreate the original market exclusivity period.
The FDA has approved generic epinephrine auto-injectors referencing EpiPen. Teva announced FDA approval of its generic epinephrine auto-injector in 2018. Mylan also marketed an authorized generic version of EpiPen, allowing the EpiPen owner to compete in the generic segment while retaining manufacturing and distribution control (FDA, 2018; Teva Pharmaceuticals, 2018).
What is the Orange Book status of EpiPen 2-Pak?
EpiPen 2-Pak is associated with FDA Orange Book listing and patent-certification activity typical of an approved drug-device product. The practical commercial position is more important than historic listing detail: the core product has no remaining regulatory barrier preventing approved generic competition.
| Exclusivity issue | Current commercial effect |
|---|---|
| Original NDA exclusivity | Expired |
| Pediatric exclusivity | Expired or no longer commercially relevant |
| Core product patents | Expired, invalidated, or no longer blocking ordinary generic entry |
| Device patents | Limited blocking value for the original EpiPen design |
| Method-of-use protection | No broad, commercially blocking exclusivity identified for emergency epinephrine use |
| Generic pathway | Established through ANDA approvals |
| Biosimilar pathway | Not applicable |
EpiPen is not a biologic, so biosimilar risk does not apply. Competitive risk comes from generics and alternative drug-device products rather than biosimilars.
What patents protect EpiPen 2-Pak?
The strongest historical protection came from patents covering the auto-injector mechanism, cartridge configuration, packaging, and related device technology. Those protections supported the product during its earlier commercial life, but they do not provide a current broad barrier to approved generic entry.
Patent estate assessment
| Patent category | Current strength |
|---|---|
| Original auto-injector mechanism | Low as a blocking asset because core terms have expired |
| Epinephrine formulation | Low; epinephrine is an old, well-characterized active ingredient |
| Two-pack packaging | Low; packaging is readily design-around-able |
| Device labeling and instructions | Low to moderate, subject to FDA requirements |
| Manufacturing know-how | Moderate, especially for reliable sterile filling and device assembly |
| Supply-chain qualification | Moderate operational barrier |
| Brand and physician familiarity | Strong commercial asset but not patent protection |
| Regulatory file and product history | Moderate commercial advantage |
The remaining barriers are primarily executional. Reliable manufacture requires control of the syringe, needle, spring, activation mechanism, dose delivery, sterility, packaging, and shelf-life performance. These barriers can slow entry or create quality problems, but they do not prevent competition after generic approval.
Which companies are challenging EpiPen 2-Pak?
The main competitive threats are Teva's generic epinephrine auto-injector, Mylan's authorized generic, and Kaléo's Auvi-Q.
| Competitor | Product type | Competitive position |
|---|---|---|
| Teva | Generic epinephrine auto-injector | Price-based substitution |
| Mylan/Viatris authorized generic | Generic EpiPen | Retains manufacturing and channel control |
| Kaléo | Auvi-Q | Differentiated audio and compact device |
| Other generic manufacturers | Epinephrine auto-injectors | Potential formulary and retail competition |
Auvi-Q is not a conventional interchangeable generic in commercial positioning. Its value proposition includes a compact form factor, voice instructions, and a distinct user interface. It can command a higher price where coverage is available, particularly among patients who prioritize portability or ease of administration.
Are there Paragraph IV challenges to EpiPen?
Historical generic entry involved patent certifications and litigation risk associated with EpiPen's listed patents. The most important commercial fact is that Paragraph IV challenges succeeded in opening the market to generic competition.
The FDA approved Teva's generic epinephrine auto-injector in 2018 after a prolonged patent dispute. That approval materially changed EpiPen's market structure by giving pharmacies and payers a lower-cost alternative (Teva Pharmaceuticals, 2018).
Current Paragraph IV activity is less commercially significant than it was before the first generic approvals. The core patent estate no longer provides the same leverage over market entry. Future disputes would more likely concern specific device improvements, manufacturing processes, labeling, or later product configurations rather than the basic EpiPen concept.
What litigation affects EpiPen 2-Pak?
EpiPen has faced several categories of litigation:
- Patent litigation involving generic manufacturers.
- Antitrust and price-related claims.
- False advertising and market-conduct disputes.
- Product-liability claims associated with injection injuries or device use.
- Government scrutiny of pricing and reimbursement practices.
The most commercially important litigation concerned Mylan's pricing and contracting practices and patent enforcement against generic competitors. These matters contributed to payer resistance, public criticism, and greater generic adoption.
Litigation risk remains higher for the product category than for a typical mature tablet because EpiPen combines a drug with a mechanical delivery device. Device defects, failure to activate, needle injuries, and improper use can produce product-liability exposure even when the epinephrine itself is well established.
What is the generic launch risk for EpiPen?
Generic launch risk is high because:
- The active ingredient is old and inexpensive.
- The product has long-established clinical use.
- The reference product has extensive FDA safety and efficacy history.
- Generic auto-injectors have already entered the U.S. market.
- Payers have a direct economic incentive to favor lower-cost alternatives.
- The device can be developed without reproducing every brand feature.
Generic substitution is not complete because auto-injectors are not purely commodity products. Patients and caregivers may prefer the device they already know. Schools and institutions may standardize on one product. Physicians may consider usability and training. Pharmacies may substitute only where state law and payer rules allow.
The most likely launch scenario is continued erosion rather than an immediate collapse. Branded EpiPen can retain a premium segment, while authorized and independent generics take a larger share of price-sensitive prescriptions.
What formulations and delivery systems are protected?
EpiPen 2-Pak does not depend on a novel epinephrine formulation. Its differentiation comes from the delivery system and package configuration.
Relevant technical elements include:
- Fixed-dose epinephrine delivery.
- Spring-driven needle deployment.
- Automatic injection after activation.
- Two-device packaging.
- Distinct dose strengths for adults and children.
- Stability through labeled shelf life.
- Safety labeling and patient instructions.
Auvi-Q competes through device design rather than a new active ingredient. Future products may target needle concealment, connected adherence monitoring, smaller form factors, longer shelf life, or alternative delivery routes. Those products would compete with EpiPen but would not necessarily be therapeutically interchangeable under all payer and regulatory rules.
How does EpiPen compare with Auvi-Q and generic epinephrine?
| Attribute | EpiPen 2-Pak | Generic EpiPen | Auvi-Q |
|---|---|---|---|
| Active ingredient | Epinephrine | Epinephrine | Epinephrine |
| Core differentiation | Brand recognition and installed base | Lower price | Device usability and compact design |
| FDA pathway | NDA | ANDA or equivalent approved pathway | NDA |
| Price position | Premium or mid-premium | Discounted | Often premium |
| Payer appeal | Variable | Strong | Variable |
| Patient familiarity | Very high | Increasing | High in selected segments |
| Patent barrier | Weak for core product | Limited current barrier | Device-specific protection may be stronger |
| Main risk | Generic erosion | Margin compression | Reimbursement and adoption cost |
EpiPen's primary advantage is commercial scale and familiarity. Generic products have the cost advantage. Auvi-Q has the clearest device-level differentiation.
How much revenue is exposed to generic competition?
In the base case, roughly 60% to 75% of EpiPen-branded revenue is exposed to U.S. generic substitution over the medium term. The exposure is greater in retail pharmacy than in institutional or government channels where procurement, training, and product standardization influence purchasing.
The revenue-risk profile is:
| Revenue source | Generic exposure | Outlook |
|---|---|---|
| U.S. retail prescriptions | High | Continued branded decline |
| U.S. schools and public access | Moderate | Contract-driven and policy-sensitive |
| Employer and institutional stock | Moderate | Brand and training can support retention |
| International markets | Low to high, varies by country | Mixed |
| Authorized generic channel | High but partially retained by Viatris | Offsets some branded erosion |
| Premium patient segment | Moderate | Sensitive to coverage and device preference |
The authorized generic strategy can preserve part of the franchise economics, but generic revenue generally carries lower net price and margin than branded EpiPen.
What licensing deals affect EpiPen 2-Pak?
EpiPen's commercial history includes manufacturing, distribution, and commercialization arrangements associated with the product's legacy ownership and Mylan's global operations. The largest strategic transaction affecting the franchise was Viatris' formation through the combination of Mylan and Upjohn, completed in 2020.
No current licensing arrangement is more commercially important than Viatris' control of the EpiPen brand, regulatory rights, manufacturing network, and authorized generic strategy. The franchise's value is primarily operational and commercial rather than dependent on a third-party technology license.
What geographic markets matter most?
The United States remains the most important market because of high prescription volume, strong brand recognition, school stocking programs, and historically high pricing. Europe and other developed markets are more fragmented. National reimbursement systems and local competitors can limit pricing.
| Region | Market characteristics |
|---|---|
| United States | Largest commercial opportunity; high generic and payer pressure |
| Canada | Established demand; smaller market and reimbursement differences |
| Western Europe | Fragmented procurement and national pricing |
| Australia | Strong allergy awareness; regulated reimbursement and supply dynamics |
| Emerging markets | Lower per-unit revenue but potential volume growth |
Geographic diversification reduces dependence on U.S. pricing but does not eliminate the effect of generic competition. Local registration, device requirements, distribution, and reimbursement determine market access.
What is the patent strength of EpiPen 2-Pak?
EpiPen's current patent strength is weak to moderate. The historical estate was effective in protecting the product before generic entry, but it no longer creates a broad, durable barrier around epinephrine auto-injectors.
The franchise is stronger in:
- Brand recognition.
- Distribution.
- Clinical familiarity.
- Institutional purchasing relationships.
- Regulatory history.
- Manufacturing know-how.
- Ability to supply an authorized generic.
It is weaker in:
- Active-ingredient exclusivity.
- Core formulation protection.
- Blocking device patents.
- Long-term pricing power.
- Defense against approved generic substitution.
Key Takeaways
- EpiPen 2-Pak is a mature Viatris franchise with expired core exclusivity.
- The product's U.S. peak sales exceeded $1 billion, but current branded sales are likely closer to the low hundreds of millions annually.
- Generic entry began changing the market materially after Teva's 2018 FDA approval.
- The base-case forecast is approximately 4% annual revenue decline through 2028.
- The EpiPen brand remains commercially relevant because of familiarity, institutional use, and the need for two devices.
- Patent protection is no longer the main barrier. Manufacturing reliability, distribution, contracting, and brand trust are more important.
- Biosimilar risk does not apply because epinephrine is a small-molecule drug.
- Auvi-Q is the principal differentiated branded competitor.
- Viatris' authorized generic can retain part of the franchise's economics while accelerating branded price erosion.
- The highest generic risk is in U.S. retail pharmacy and payer-controlled channels.
FAQs
When did EpiPen lose market exclusivity?
EpiPen's original regulatory exclusivity expired decades ago. Practical competition increased materially after FDA approval of generic epinephrine auto-injectors, including Teva's product in 2018.
Is EpiPen 2-Pak still patent protected?
The original EpiPen concept is not protected by a broad, commercially blocking patent estate. Product-specific improvements or manufacturing technologies may have separate protection, but they do not prevent generic competition with the established product.
Is EpiPen 2-Pak interchangeable with generic epinephrine?
FDA-approved generic versions may be therapeutically equivalent to the reference product under their approved pathway, but pharmacy substitution depends on the specific FDA designation, state law, payer rules, and product availability.
Does EpiPen have biosimilar competition?
No. EpiPen contains epinephrine, a small-molecule active ingredient. Its competitive threats are generic auto-injectors and alternative branded devices, not biosimilars.
What is the most likely EpiPen sales scenario through 2028?
The most likely scenario is gradual branded revenue erosion of approximately 3% to 6% annually, partly offset by category growth, institutional demand, international sales, and authorized generic revenue.
References
-
Food and Drug Administration. (2018). FDA approves first generic version of EpiPen. U.S. Department of Health and Human Services.
-
Mylan N.V. (2017). Annual report for the fiscal year ended March 31, 2017. Mylan N.V.
-
Teva Pharmaceuticals. (2018). Teva announces FDA approval of generic EpiPen auto-injector. Teva Pharmaceutical Industries Ltd.
-
Viatris Inc. (2021). Annual report for the fiscal year ended December 31, 2020. Viatris Inc.
-
Viatris Inc. (2024). Annual report and Form 10-K. Viatris Inc.
More… ↓
