Share This Page
Drug Sales Trends for EPINEPHRINE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for EPINEPHRINE (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
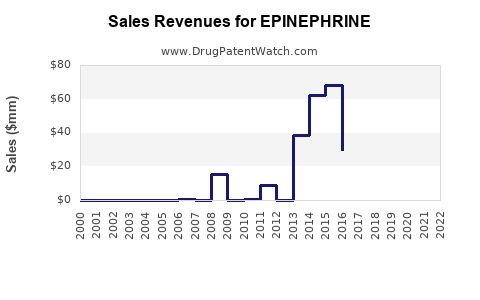
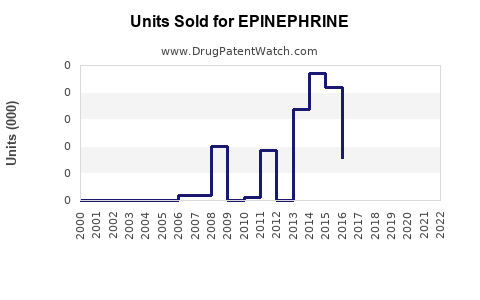
Annual Sales Revenues and Units Sold for EPINEPHRINE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| EPINEPHRINE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| EPINEPHRINE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| EPINEPHRINE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| EPINEPHRINE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| EPINEPHRINE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Epinephrine Market Analysis, Sales Forecast, Patent Risks, and Competitive Landscape
Epinephrine is a mature, high-volume emergency medicine market with limited active-ingredient protection and continuing commercial value in delivery systems. The largest revenue pool is prescription auto-injectors, led by EpiPen and authorized or independent generic equivalents. Intranasal epinephrine, introduced in the United States with neffy in 2024, is the main source of potential market expansion.
The global epinephrine market is estimated at approximately $2.0 billion to $2.5 billion in 2024 across auto-injectors, prefilled syringes, ampoules, vials, and hospital products. The addressable market is projected to reach roughly $2.7 billion to $3.2 billion by 2030, representing a modeled compound annual growth rate of about 5% to 7%. Prescription emergency-use products account for the highest margins, while hospital epinephrine products are largely commoditized.
What is the current market size for epinephrine?
Published market estimates differ because some reports include hospital injectables and others count only allergy rescue products. A normalized market view is shown below.
| Segment | Estimated 2024 global sales | 2030 modeled sales | 2024-2030 growth |
|---|---|---|---|
| Epinephrine auto-injectors | $1.1B-$1.4B | $1.5B-$1.9B | 4%-6% |
| Intranasal epinephrine | Less than $50M | $250M-$500M | High from low base |
| Prefilled syringes and emergency injectables | $450M-$600M | $550M-$700M | 3%-4% |
| Hospital vials and ampoules | $350M-$500M | $400M-$550M | 2%-3% |
| Total market | $2.0B-$2.5B | $2.7B-$3.2B | 5%-7% |
The auto-injector segment has the strongest commercial economics because patients, schools, employers, emergency services, and caregivers pay for convenience, portability, and ease of administration. Hospital injectable products have lower pricing and greater exposure to tenders, group purchasing organizations, and supply shortages.
The principal demand drivers are:
- Rising diagnosis of food allergy and anaphylaxis.
- Broader prescribing for patients at risk of severe allergic reactions.
- School stocking laws and public-access epinephrine programs.
- Replacement purchases caused by expiration dates.
- Increased use of two-device prescriptions.
- Growth of patient preference for needle-free or lower-training delivery systems.
Which companies sell epinephrine products?
The competitive market is fragmented by dosage form but concentrated in consumer-facing auto-injectors.
| Company | Product or position | Primary competitive role |
|---|---|---|
| Viatris and Pfizer | EpiPen and authorized generic EpiPen | Established auto-injector franchise |
| Viatris | Generic epinephrine auto-injector | Lower-priced alternative |
| Teva Pharmaceutical | Generic epinephrine auto-injector | Generic competition |
| Sandoz | Generic epinephrine auto-injector | Generic competition in selected markets |
| Kaleo | Auvi-Q | Premium, voice-guided auto-injector |
| ARS Pharmaceuticals | Neffy | Intranasal epinephrine |
| Adamis Pharmaceuticals, now associated with generic commercialization | Symjepi | Prefilled syringe product |
| Hikma, Amphastar, Pfizer, and other injectable manufacturers | Vials, ampoules, and prefilled products | Hospital and emergency-care supply |
EpiPen retains the strongest brand recognition. Auvi-Q competes through compact design, voice instructions, and differentiated user experience. Neffy changes the delivery category by removing the needle and replacing intramuscular injection with nasal administration. Generic auto-injectors compete primarily on reimbursement and pharmacy price.
How much revenue does EpiPen generate?
EpiPen remains the most commercially important branded epinephrine product, although its historical peak was followed by price pressure, generic entry, payer restrictions, and reputational damage related to pricing.
Viatris does not consistently disclose EpiPen revenue as a standalone line item in public filings. Its commercial exposure is therefore best assessed through the broader North American established brands portfolio, prescription data, and market-share estimates rather than a reported product-level figure.
A reasonable 2024 estimate for global EpiPen-branded and authorized-generic sales is approximately $500 million to $800 million. This range includes branded EpiPen, authorized generic distribution, and associated market channels, but excludes the entire epinephrine market.
Auvi-Q revenue is lower than EpiPen revenue but has a higher differentiation profile. Its commercial performance depends on insurance coverage, copay support, specialty-pharmacy distribution, and direct-to-consumer marketing. Neffy revenue was limited in 2024 because the product launched late in the year. Its main commercial question is whether physicians and patients will accept nasal delivery for severe allergic emergencies.
What are the sales projections for epinephrine through 2030?
The forecast below uses a 2024 global market base of $2.25 billion and separates mature injectable products from newer delivery formats.
| Year | Base-case market sales | Annual growth | Key driver |
|---|---|---|---|
| 2024 | $2.25B | - | Established auto-injector market |
| 2025 | $2.38B | 6% | Neffy launch and replacement demand |
| 2026 | $2.52B | 6% | Wider payer and physician adoption |
| 2027 | $2.67B | 6% | Intranasal category expansion |
| 2028 | $2.83B | 6% | Growth in school and public-access programs |
| 2029 | $3.00B | 6% | Broader international commercialization |
| 2030 | $3.18B | 6% | Mature but expanded delivery market |
Scenario analysis
| Scenario | 2030 global sales | Implied 2024-2030 CAGR | Main assumptions |
|---|---|---|---|
| Downside | $2.55B | 2%-4% | Generic price erosion and weak Neffy uptake |
| Base case | $3.18B | 5%-7% | Stable auto-injector demand and moderate nasal adoption |
| Upside | $3.70B | 8%-9% | Strong Neffy conversion, new markets, and higher diagnosis rates |
The base case assumes auto-injector unit volume remains stable while average selling prices decline modestly. Revenue growth comes from larger diagnosed populations, higher prescription persistence, and expansion of non-injectable products.
What is the growth outlook for neffy intranasal epinephrine?
The FDA approved neffy, a 2 mg intranasal epinephrine product from ARS Pharmaceuticals, in August 2024 for the emergency treatment of allergic reactions, including anaphylaxis, in adults and children weighing at least 30 kilograms.[1]
Neffy is the first FDA-approved intranasal epinephrine product in the United States. Its commercial advantages are:
- No needle.
- No injection training.
- Potentially easier administration by teachers, coaches, caregivers, and bystanders.
- Improved portability and patient acceptance.
- Potential use in patients who delay or avoid injection.
The principal risks are clinical adoption, physician confidence in severe anaphylaxis, repeat-dose requirements, payer coverage, and the need for users to understand that emergency medical care remains necessary after administration.
Under the base case, neffy could reach $250 million to $500 million in annual global sales by 2030 if it secures broad formulary access and gains share in schools, pediatric care, emergency preparedness, and patients with injection aversion. The product is more likely to expand the total market than to replace all auto-injector use. Auto-injectors remain important where established treatment protocols, insurance coverage, and caregiver familiarity favor injection.
What patents protect epinephrine products?
The epinephrine molecule is long off-patent. Commercial protection resides mainly in delivery devices, formulation, manufacturing processes, packaging, and regulatory exclusivity.
Auto-injector patents
EpiPen-related patent protection historically covered device mechanics, cartridge configuration, needle deployment, safety features, and automatic injection systems. Those protections have largely expired or become less effective as generic manufacturers developed design alternatives.
The current barriers to entry are therefore less dependent on a single blocking patent and more dependent on:
- FDA device-drug combination requirements.
- Human-factors testing.
- Reliable dose delivery under stress.
- Manufacturing scale.
- Device component sourcing.
- Pharmacy substitution and contracting.
- Product-liability exposure.
Intranasal formulation patents
Neffy has a stronger potential intellectual-property position than standard injectable epinephrine because protection can cover:
- Intranasal delivery of epinephrine.
- Concentration and excipient composition.
- Absorption-enhancing formulations.
- Spray-device geometry.
- Dosing protocols.
- Use in anaphylaxis and severe allergic reactions.
- Manufacturing and stability characteristics.
The commercial value of these rights depends on issued claims, Orange Book listings, patent-term adjustment, pediatric exclusivity, and the ability to establish infringement against alternative nasal formulations.
What is the FDA regulatory and Orange Book status of epinephrine?
Epinephrine auto-injectors are drug-device combination products regulated through the FDA drug pathway. The EpiPen reference product has long-established FDA approval, and generic manufacturers have obtained abbreviated new drug application approvals for equivalent products.
The main FDA categories are:
| Product type | FDA pathway | Regulatory position |
|---|---|---|
| EpiPen and equivalent auto-injectors | NDA and ANDA | Mature approved market |
| Prefilled epinephrine syringes | NDA, ANDA, or injectable drug application | Mature hospital and emergency market |
| Vials and ampoules | NDA or ANDA | Highly genericized |
| Neffy | NDA | Newly approved intranasal product |
Orange Book relevance is highest for branded products with listed formulation, device, or method-of-use patents. For mature epinephrine injectables, the principal challenge is generally generic substitution rather than active-ingredient patent litigation.
Paragraph IV risk is most relevant to newer products, particularly intranasal epinephrine. A generic applicant challenging listed patents could seek approval before patent expiry by arguing that the patents are invalid, unenforceable, or not infringed. The timing of any challenge depends on the final Orange Book listing and the scope of approved claims.
When does epinephrine lose exclusivity?
Epinephrine itself has no meaningful remaining composition-of-matter exclusivity. Market exclusivity depends on the product.
| Product category | Exclusivity position |
|---|---|
| Injectable epinephrine | Long off-patent; generic competition established |
| EpiPen | Core historical device protection expired or weakened; brand remains commercially relevant |
| Auvi-Q | Commercial differentiation and device rights are more important than molecule exclusivity |
| Neffy | New-product regulatory exclusivity and formulation, device, and method patents are the principal protections |
| Hospital epinephrine | Generally commodity pricing with limited practical exclusivity |
Neffy received five-year new chemical entity exclusivity if the FDA classifies its active product protection under the applicable NDA exclusivity framework, although the precise exclusivity treatment depends on FDA regulatory classification and the product’s listed active ingredient status. Patent expiry could extend beyond regulatory exclusivity.
What generic entry risks affect epinephrine sales?
Generic competition is already a permanent feature of the injectable and auto-injector markets. The main future risks are:
- Additional auto-injector approvals that reduce pharmacy reimbursement.
- Authorized-generic pricing that anchors payer negotiations.
- Device redesigns that avoid residual EpiPen claims.
- Generic or alternative intranasal products after Neffy exclusivity and patent expiry.
- Hospital tendering that shifts volume toward the lowest-cost supplier.
- Supply interruptions that cause temporary switching but can also accelerate formulary replacement.
Generic entry affects revenue more severely than volume. Patients continue to need epinephrine, but average selling prices decline as substitution increases.
How strong is the epinephrine patent estate?
The patent estate is weak for the active ingredient and mature injectable products, moderate for established auto-injector platforms, and potentially strong for differentiated intranasal formulations.
| Asset | Patent strength | Commercial durability |
|---|---|---|
| Epinephrine molecule | Weak or exhausted | Low |
| Standard vial or ampoule | Weak | Low |
| Generic auto-injector | Moderate device barriers | Moderate |
| EpiPen brand and platform | Moderate brand and device protection | Moderate |
| Auvi-Q | Moderate device and user-interface differentiation | Moderate |
| Neffy | Potentially strong formulation and delivery protection | Dependent on claims and adoption |
The strongest barriers are regulatory and manufacturing barriers rather than basic molecule patents. A competitor must demonstrate dose accuracy, stability, usability, device reliability, and manufacturing consistency. These requirements can delay entry even when broad patent protection is limited.
What litigation and settlement issues affect epinephrine?
Epinephrine has experienced patent disputes, pricing investigations, product-liability claims, device recalls, and antitrust scrutiny. The most commercially significant historical dispute involved generic entry into the EpiPen market and related patent challenges.
The principal litigation risks now are:
- Patent litigation involving intranasal formulations.
- Device equivalence disputes for auto-injectors.
- Product-liability claims involving failure to deliver a dose.
- Antitrust claims concerning rebates, contracting, and market access.
- Manufacturing and supply-chain litigation.
- State and federal scrutiny of emergency-drug pricing.
Settlement agreements can delay generic launch, but their value depends on the remaining patent term and whether a competitor can enter through a non-infringing design. For mature auto-injectors, settlements have less power than they had before generic alternatives became widely available.
How does epinephrine compare with competing allergy rescue products?
| Product | Delivery | Main advantage | Main weakness |
|---|---|---|---|
| EpiPen | Intramuscular auto-injector | Brand recognition and clinical familiarity | Needle, size, price pressure |
| Generic auto-injector | Intramuscular auto-injector | Lower cost | Less brand loyalty and variable device familiarity |
| Auvi-Q | Compact auto-injector with audio prompts | User guidance and portability | Higher commercial cost and narrower scale |
| Neffy | Intranasal spray | Needle-free administration | New clinical and payer adoption cycle |
| Prefilled syringe | Manual injection | Lower device complexity | Requires more administration skill |
| Vial and ampoule | Manual injection | Low unit cost | Hospital-centered and unsuitable for many lay users |
What are the key investment and commercial risks?
Revenue exposure is concentrated in products with brand pricing, device differentiation, and payer access. A manufacturer with a mature auto-injector franchise faces gradual price erosion rather than sudden demand destruction. A manufacturer launching intranasal epinephrine faces the opposite profile: significant growth potential but substantial market-education and reimbursement risk.
The most important commercial variables through 2030 are:
- Neffy formulary placement.
- Patient and caregiver acceptance of intranasal dosing.
- U.S. school-stock epinephrine adoption.
- Generic auto-injector pricing.
- Frequency of product shortages.
- International approval and distribution.
- Patent durability for nasal formulations.
- Reimbursement for two-device prescriptions.
Key Takeaways
- The global epinephrine market is estimated at $2.0 billion to $2.5 billion in 2024.
- Base-case sales are projected to reach about $3.18 billion by 2030.
- Auto-injectors remain the largest segment, with EpiPen retaining substantial brand value despite generic competition.
- Epinephrine has no meaningful active-ingredient exclusivity; commercial protection is concentrated in devices, formulations, and regulatory approvals.
- Neffy is the main growth catalyst after its FDA approval in August 2024.
- Generic pressure will continue to reduce prices, especially for auto-injectors and hospital injectables.
- The strongest future patent position is likely to arise from intranasal formulation and delivery claims rather than from the epinephrine molecule.
- The base-case outlook favors steady market growth, with the upside scenario dependent on rapid acceptance of needle-free delivery.
FAQs
What is the largest epinephrine product by sales?
EpiPen and its authorized-generic channel remain the largest branded commercial franchise in epinephrine auto-injectors, although precise product-level revenue is not consistently disclosed.
Is epinephrine a biologic drug?
No. Epinephrine is a small-molecule adrenergic agonist. Biosimilar regulation does not apply. Competition occurs through generic drugs and drug-device combination products.
Will neffy replace EpiPen?
Neffy is more likely to take share from auto-injectors in selected populations than to replace them entirely. Needle aversion, pediatric use, school programs, and caregiver preferences are likely early adoption segments.
Does epinephrine have an Orange Book patent?
Some branded epinephrine products may have listed device, formulation, or method-of-use patents. The active ingredient itself is not protected by a current composition-of-matter patent. The controlling analysis requires the product-specific FDA Orange Book entry.
What is the main barrier to launching a generic epinephrine auto-injector?
The main barriers are device reliability, human-factors validation, FDA combination-product requirements, manufacturing scale, and pharmacy substitution. Active-ingredient patent protection is generally not the primary barrier.
References
- U.S. Food and Drug Administration. (2024, August 9). FDA approves first epinephrine nasal spray for emergency treatment of allergic reactions, including anaphylaxis. https://www.fda.gov
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
- Viatris Inc. (2024). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934. U.S. Securities and Exchange Commission.
- Grand View Research. (2024). Epinephrine market size, share and trends analysis report. Grand View Research.
More… ↓
