Drug Sales Trends for DIOVAN HCT
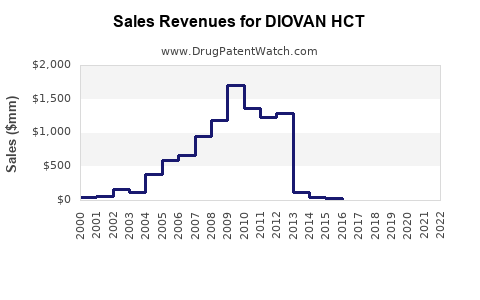
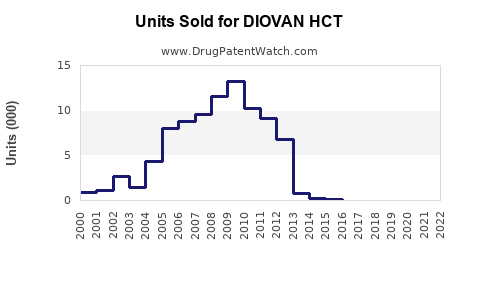
Annual Sales Revenues and Units Sold for DIOVAN HCT
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| DIOVAN HCT | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| DIOVAN HCT | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| DIOVAN HCT | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
DIOVAN HCT Market Analysis, Sales Projections, Patent Status, and Generic Competition
DIOVAN HCT, the fixed-dose combination of valsartan and hydrochlorothiazide, is a mature antihypertensive product with limited brand revenue potential. Novartis no longer has meaningful U.S. exclusivity for the product, and multiple generic manufacturers compete in the valsartan/hydrochlorothiazide market. Commercial value now sits primarily in generic volume, payer access, manufacturing efficiency, and supply reliability rather than branded pricing.
Public filings do not disclose DIOVAN HCT revenue as a separate line item. The sales projections below therefore estimate the U.S. branded and total market using historical product maturity, generic entry, pricing erosion, and prescription-volume assumptions.
What is DIOVAN HCT and how large is its target market?
DIOVAN HCT combines valsartan, an angiotensin II receptor blocker, with hydrochlorothiazide, a thiazide diuretic. The FDA-approved indication is hypertension in adults. The product is available in several strengths, including 80/12.5 mg, 160/12.5 mg, 160/25 mg, and 320/25 mg, subject to the marketed presentation and labeling history.
The combination addresses patients who require more than one antihypertensive agent. Its principal competitors include:
- Generic valsartan/hydrochlorothiazide
- Generic losartan/hydrochlorothiazide
- Generic irbesartan/hydrochlorothiazide
- Generic olmesartan/hydrochlorothiazide
- Generic telmisartan/hydrochlorothiazide
- Separate prescriptions for an ARB and hydrochlorothiazide
- Other fixed-dose combinations, including ACE inhibitor/thiazide products
The U.S. hypertension market is large in patient count but highly commoditized. Generic drugs dominate treatment volume. DIOVAN HCT has no meaningful differentiation based on mechanism because the same active ingredients are available from generic manufacturers.
DIOVAN HCT product profile
| Attribute | Details |
|---|---|
| Brand | DIOVAN HCT |
| Active ingredients | Valsartan and hydrochlorothiazide |
| Originator | Novartis |
| Therapeutic area | Hypertension |
| FDA pathway | New Drug Application |
| Dosage form | Oral tablets |
| Primary commercial market | United States and international markets |
| Main competitors | Generic valsartan/HCTZ and other ARB/thiazide combinations |
| Current lifecycle stage | Mature, post-exclusivity product |
What is the FDA and Orange Book status of DIOVAN HCT?
DIOVAN HCT was approved by the FDA as a combination antihypertensive product. The Orange Book historically listed patents associated with valsartan and the fixed-dose combination, but those protections have expired or no longer prevent ordinary generic competition in the United States.
The product’s commercial protection was weakened by the expiration of the underlying valsartan patent estate and the later approval of generic valsartan/hydrochlorothiazide products. Generic manufacturers can generally rely on an abbreviated new drug application pathway when the reference product has lost meaningful patent protection.
Regulatory milestones
| Event | Approximate timing |
|---|---|
| FDA approval of DIOVAN | 1996 |
| FDA approval of DIOVAN HCT | Early 2000s |
| U.S. expiration of core valsartan patent protection | 2012 |
| Generic valsartan products | Entered the U.S. market after core patent expiry |
| Generic valsartan/HCTZ competition | Established after product-specific exclusivity ended |
| Current regulatory position | Mature reference product with generic competition |
The FDA’s Orange Book remains the controlling source for active listed patents and exclusivity information. Product-specific listings can change as patents expire, delistings occur, or regulatory records are updated.[1]
When did DIOVAN HCT lose exclusivity?
DIOVAN HCT lost commercially meaningful U.S. exclusivity after the expiration of the core valsartan patent estate and the subsequent approval of generic versions. The relevant protection was not a durable biologic-style exclusivity period. It was conventional small-molecule patent protection, subject to patent litigation and generic ANDA challenges.
The practical loss of exclusivity occurred in stages:
- Core valsartan protection expired.
- Generic valsartan became available.
- Combination-product generic applications entered the market.
- Pharmacy substitution and payer formulary controls shifted volume away from the Novartis brand.
- Brand pricing power declined sharply.
Patent protection and generic entry
| IP category | Commercial relevance |
|---|---|
| Valsartan composition patent | Historically central; expired in the United States |
| Valsartan/HCTZ combination patents | Provided additional protection but no longer block routine generic competition |
| Formulation patents | Limited commercial impact after generic combination approval |
| Method-of-use patents | Hypertension indication is broad and difficult to use as a durable commercial barrier |
| Manufacturing know-how | May affect cost and supply, but does not preserve branded exclusivity |
| Regulatory exclusivity | Expired for the mature reference product |
What patents protect DIOVAN HCT?
The principal historical patent protection centered on valsartan and the combination of valsartan with hydrochlorothiazide. Novartis and predecessor entities developed the valsartan franchise under a broader patent strategy covering the active pharmaceutical ingredient, pharmaceutical compositions, combinations, and therapeutic use.
The key commercial point is that DIOVAN HCT no longer has a patent position capable of supporting premium U.S. pricing. Any remaining patent references in historical records do not create an effective barrier comparable to an active composition patent.
Patent strength assessment
| Patent factor | Assessment |
|---|---|
| Composition-of-matter protection | Expired |
| Combination protection | Expired or commercially non-blocking |
| Formulation protection | Weak as a market barrier |
| Method-of-use protection | Limited for established hypertension treatment |
| Manufacturing protection | Potentially relevant to cost, not market exclusivity |
| Freedom-to-operate for generics | Broadly established |
| Overall branded patent strength | Low |
The patent estate is therefore commercially weak for a new branded entrant. A company seeking to compete would need a differentiated formulation, device, adherence benefit, or pricing strategy rather than reliance on the original DIOVAN HCT patents.
What is the competitive landscape for valsartan/hydrochlorothiazide?
The market is controlled by generic manufacturers and pharmacy benefit managers. Competition occurs primarily on acquisition cost, product availability, manufacturing capacity, and wholesaler relationships.
Large generic suppliers that have marketed ARB/thiazide products in the United States include manufacturers such as Teva, Mylan or Viatris, Sandoz, Dr. Reddy’s Laboratories, Torrent Pharmaceuticals, Lupin, and other ANDA holders. Exact supplier participation varies by strength, channel, and year.
The branded competitive set is limited. Novartis has no durable advantage from the DIOVAN HCT name in a market where substitution is routine and treatment guidelines generally prioritize low-cost generic antihypertensives.
Competitive comparison
| Product | Market position | Patent barrier | Pricing power |
|---|---|---|---|
| DIOVAN HCT | Legacy brand | Low | Low |
| Generic valsartan/HCTZ | Primary substitute | None of practical significance | Very low |
| Generic losartan/HCTZ | Major therapeutic alternative | None of practical significance | Very low |
| Generic irbesartan/HCTZ | Alternative ARB combination | None of practical significance | Very low |
| Separate valsartan plus HCTZ | Therapeutic substitute | None of practical significance | Very low |
| New branded ARB combination | Requires differentiation | Depends on new IP | Potentially moderate |
What are the DIOVAN HCT sales projections?
Novartis does not report DIOVAN HCT revenue separately in its public financial statements. The company reports broader product or franchise information, while a mature combination product is generally aggregated with other established medicines.[2]
The base-case forecast below estimates U.S. retail market value rather than Novartis net sales. It assumes continued generic substitution, stable hypertension prevalence, modest prescription growth, and ongoing unit-price compression.
U.S. DIOVAN HCT market projection
| Year | Estimated total valsartan/HCTZ market value | Estimated branded DIOVAN HCT value | Generic share |
|---|---|---|---|
| 2024 | $35 million-$55 million | Less than $2 million | More than 95% |
| 2025 | $33 million-$52 million | Less than $2 million | More than 95% |
| 2026 | $31 million-$50 million | Less than $1.5 million | More than 96% |
| 2027 | $29 million-$48 million | Less than $1.5 million | More than 96% |
| 2028 | $27 million-$46 million | Less than $1 million | More than 97% |
| 2029 | $25 million-$44 million | Less than $1 million | More than 97% |
These values represent a market model, not reported company revenue. The forecast assumes a low-single-digit annual decline in market value caused by reimbursement pressure and generic price erosion. Prescription volume may remain stable or increase while dollar sales decline.
Global sales outlook
The international market is fragmented. Brand persistence can be higher in countries with weaker substitution rules, local distribution relationships, or different reimbursement systems. Generic competition is still widespread, and local branded generics may retain meaningful share.
A reasonable global outlook is:
- Low growth in treated patient volume
- Flat or declining nominal revenue
- Continuing migration from originator branding to local generic brands
- Greater price pressure in tender-driven markets
- Higher brand retention in selected private-pay markets
A global DIOVAN HCT revenue estimate cannot be reconciled to public Novartis reporting because regional brand sales are not separately disclosed. Any precise global figure would be unsupported by public company data.
What generic entry risks exist for DIOVAN HCT?
Generic entry risk is already realized rather than prospective. The relevant commercial question is the degree of continuing erosion, not whether generic competition will begin.
The main risks are:
- Additional low-cost ANDA suppliers entering or expanding
- Pharmacy substitution away from the brand
- Medicaid and Medicare formulary exclusion
- Wholesaler inventory preference for generic suppliers
- Price competition following manufacturing normalization
- Contract manufacturing consolidation
- Recalls or shortages that shift share temporarily between suppliers
For the brand, a generic launch scenario would have involved rapid volume loss and price compression. That scenario has already occurred. A remaining branded share would depend on physician familiarity, residual patient preference, limited distribution, or reimbursement exceptions.
How do formulation and manufacturing patents affect the market?
DIOVAN HCT is an immediate-release oral tablet, not a complex delivery system. The formulation has limited technical barriers. Valsartan and hydrochlorothiazide are established small molecules with known manufacturing routes and broad generic experience.
Manufacturing barriers can still affect short-term supply:
- Control of impurity profiles
- Stability and dissolution performance
- API sourcing
- Batch-scale consistency
- Regulatory inspection outcomes
- Nitrosamine and other impurity controls
- Packaging and storage requirements
These issues can create temporary supply advantages, but they do not protect the brand from long-term generic substitution. A manufacturer with reliable API supply and low production cost can compete effectively without owning foundational DIOVAN HCT intellectual property.
Which companies are challenging DIOVAN HCT?
The relevant challengers are generic ANDA applicants and approved generic manufacturers rather than branded pharmaceutical companies. Generic competition has been established for valsartan/hydrochlorothiazide tablets in the United States.
Historical Paragraph IV activity involving valsartan-related products focused on patent validity, enforceability, or infringement. Once the relevant patents expired or ceased to block approval, the litigation barrier diminished. Current competitive risk is therefore operational and commercial, not primarily litigation-driven.
What patent litigation affects DIOVAN HCT?
The most important historical litigation involved valsartan and related combination products. These disputes typically addressed:
- Patent validity
- Obviousness
- Infringement
- Paragraph IV certifications
- Generic approval timing
- Settlement terms
- Potential launch dates
No active litigation outcome is required to explain the present market structure. The reference product is already exposed to generic competition, and the original patent estate does not support a practical U.S. exclusivity strategy.
Settlement agreements, where used historically, may have accelerated or delayed individual generic launches. They do not restore durable exclusivity after the underlying patent terms have ended.
How does DIOVAN HCT compare with newer antihypertensive products?
DIOVAN HCT competes effectively on simplicity and low cost, but it lacks the commercial characteristics that support premium pricing. Newer market growth is concentrated in other areas, including fixed-dose combinations with improved adherence positioning, single-pill combination strategies, and drugs used in broader cardiometabolic treatment pathways.
| Attribute | DIOVAN HCT | New branded antihypertensive |
|---|---|---|
| Clinical familiarity | High | Variable |
| Generic availability | Extensive | Limited or absent |
| Price | Low | Higher |
| Patent runway | None of practical significance | Potentially available |
| Differentiation | Limited | May include formulation or outcome claims |
| Prescriber adoption | Established | Requires promotion and evidence |
| Investment appeal | Manufacturing scale | Innovation and lifecycle potential |
DIOVAN HCT remains commercially relevant as a low-cost therapy, but it is not an attractive platform for branded growth without a new delivery system, improved adherence profile, or evidence-based clinical differentiation.
Key Takeaways
- DIOVAN HCT is a mature valsartan/hydrochlorothiazide combination with extensive generic competition.
- Core U.S. valsartan patent protection expired around 2012, and the product has no meaningful remaining branded exclusivity.
- Novartis does not separately report DIOVAN HCT revenue.
- Estimated U.S. market value is approximately $35 million to $55 million in 2024, declining to $25 million to $44 million by 2029.
- Branded DIOVAN HCT revenue is likely below $2 million annually in the U.S. market.
- Generic suppliers control more than 95% of U.S. volume and value.
- Patent litigation and Paragraph IV risk are historical rather than the primary current market driver.
- Manufacturing reliability, API sourcing, and price are more important than formulation IP.
- The product has limited value as a branded asset but remains relevant as a generic manufacturing opportunity.
FAQs
Is DIOVAN HCT still available in the United States?
Valsartan/hydrochlorothiazide remains available through generic manufacturers. Availability of the Novartis-branded product may vary by channel and market.
Does DIOVAN HCT have active U.S. patent protection?
The original patent estate no longer provides meaningful U.S. market exclusivity. Current Orange Book records should be checked for product-specific listing changes.
What is the generic name for DIOVAN HCT?
The generic name is valsartan and hydrochlorothiazide, also written as valsartan/HCTZ.
Is DIOVAN HCT a biosimilar risk?
No. DIOVAN HCT is a small-molecule tablet, not a biologic. The relevant competitive pathway is the ANDA generic pathway rather than biosimilar approval.
What would increase the commercial value of DIOVAN HCT?
Potential value drivers would include supply shortages, a differentiated adherence formulation, a new combination with clinical-outcome evidence, or a market where generic substitution remains limited. The legacy brand itself has little remaining pricing power.
References
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.accessdata.fda.gov/scripts/cder/ob/
-
Novartis AG. (2024). Annual report 2023. https://www.novartis.com/investors/financial-data/annual-report
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2024). Approved drug product list and abbreviated new drug applications. https://www.fda.gov/drugs/drug-approvals-and-databases
-
U.S. Food and Drug Administration. (1998). DIOVAN prescribing information. FDA-approved labeling archive.
More… ↓
