Share This Page
Drug Sales Trends for CLOPIDOGREL BISULFATE
✉ Email this page to a colleague
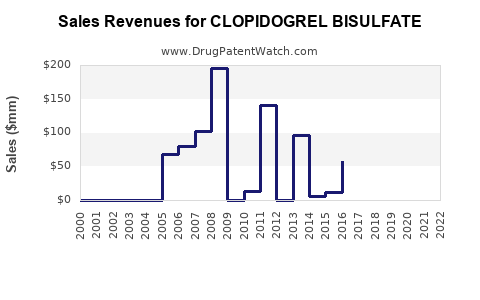
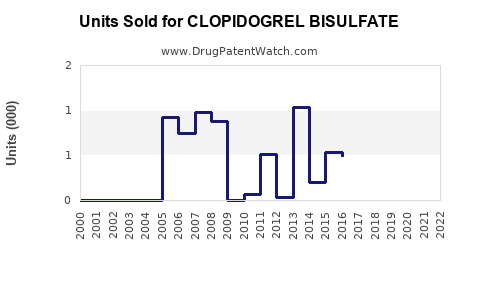
Annual Sales Revenues and Units Sold for CLOPIDOGREL BISULFATE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| CLOPIDOGREL BISULFATE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| CLOPIDOGREL BISULFATE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| CLOPIDOGREL BISULFATE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Clopidogrel Bisulfate Market Analysis, Sales Projections, Patent Status, and Competitive Outlook
Clopidogrel bisulfate is a mature, low-cost antiplatelet drug with durable global demand. Its commercial value is driven by high prescription volume in secondary prevention after myocardial infarction, ischemic stroke, peripheral arterial disease, and acute coronary syndrome. The original Plavix franchise generated more than $9 billion in annual sales before generic entry, but branded revenue collapsed after loss of exclusivity. The current market is fragmented among generic manufacturers, with price competition limiting revenue growth even as patient volume rises.
A base-case model projects global clopidogrel bisulfate sales declining from approximately $1.6 billion in 2024 to $1.2 billion by 2030, representing a compound annual decline of about 4.6%. Volume growth in emerging markets and continued use in maintenance therapy will partly offset falling prices.
What is the current market position of clopidogrel bisulfate?
Clopidogrel bisulfate is the bisulfate salt of clopidogrel, a P2Y12 platelet aggregation inhibitor. It is administered orally, most commonly as 75 mg tablets, with a 300 mg loading dose used in selected acute coronary syndrome and percutaneous coronary intervention settings.
The FDA-approved indications include:
- Recent myocardial infarction
- Recent ischemic stroke
- Established peripheral arterial disease
- Acute coronary syndrome, including non-ST-elevation myocardial infarction and unstable angina
- ST-elevation myocardial infarction in certain treatment settings
The market has three structural characteristics:
- Clopidogrel is clinically established and widely available.
- Generic manufacturing has eliminated most branded pricing power.
- Treatment guidelines increasingly favor ticagrelor or prasugrel for selected high-risk acute coronary syndrome patients, while clopidogrel remains important for long-term maintenance and patients with bleeding, cost, age, or tolerability concerns.
The drug has a large installed patient base because it is used for months or years after a cardiovascular event. Its low cost also supports access in public health systems and lower-income markets.
How large is the clopidogrel bisulfate market?
Public companies generally do not report clopidogrel sales as a separate line item. Market estimates therefore vary according to whether they include hospital tenders, retail prescriptions, combination products, branded products, and multiple geographic markets.
A practical 2024 estimate places global clopidogrel bisulfate sales at approximately $1.3 billion to $2.0 billion. The midpoint of $1.6 billion is used for the base-case projection below.
| Market segment | 2024 estimated share of value | Commercial characteristics |
|---|---|---|
| North America | 20%-25% | High generic penetration and low unit pricing |
| Europe | 25%-30% | Broad reimbursement, centralized procurement, mature generic market |
| Asia-Pacific | 35%-40% | Largest volume opportunity, uneven pricing and regulatory conditions |
| Latin America, Middle East, and Africa | 10%-20% | Demand growth but lower average selling prices |
The distribution of volume differs from the distribution of revenue. Asia-Pacific likely accounts for the largest number of tablets, while North America and Western Europe retain greater revenue per prescription.
What are the sales projections for clopidogrel bisulfate through 2030?
The forecast is based on three variables: treated patient volume, generic price erosion, and geographic mix. Volume is expected to increase modestly, but unit prices should continue to decline in highly competitive markets.
Base-case forecast
| Year | Estimated global sales | Annual change | Primary driver |
|---|---|---|---|
| 2024 | $1.60 billion | - | Baseline |
| 2025 | $1.54 billion | -3.8% | Generic price pressure |
| 2026 | $1.48 billion | -3.9% | Mature-market erosion |
| 2027 | $1.42 billion | -4.1% | Tender pricing and substitution |
| 2028 | $1.35 billion | -4.9% | Continued commoditization |
| 2029 | $1.28 billion | -5.2% | Lower average selling prices |
| 2030 | $1.20 billion | -6.3% | Market maturity |
The forecast implies a 2024-2030 compound annual growth rate of approximately negative 4.6%.
Scenario analysis
| Scenario | 2024 sales | 2030 sales | 2024-2030 CAGR | Assumptions |
|---|---|---|---|---|
| Upside | $1.8 billion | $1.7 billion | -1.0% | Strong emerging-market volume and slower price erosion |
| Base case | $1.6 billion | $1.2 billion | -4.6% | Moderate volume growth and persistent generic competition |
| Downside | $1.4 billion | $0.8 billion | -9.5% | Faster substitution by newer P2Y12 inhibitors and aggressive tenders |
The upside case depends on increased diagnosis and treatment of cardiovascular disease in India, China, Southeast Asia, Latin America, and other underpenetrated markets. The downside case becomes more likely if guideline-driven use of ticagrelor or prasugrel expands beyond acute coronary syndrome into longer-term treatment.
When did clopidogrel lose exclusivity?
The original Plavix exclusivity period ended in the United States in the early 2010s. The core U.S. patent estate included U.S. Patent No. 4,847,265, which covered clopidogrel and related stereochemistry. The patent term was extended beyond the ordinary term and expired in 2012.
FDA-approved generic clopidogrel products entered the U.S. market in 2012. The loss of exclusivity rapidly reduced Plavix revenue and shifted the market toward multiple generic suppliers.
| Event | Approximate timing | Commercial effect |
|---|---|---|
| Initial U.S. FDA approval of Plavix | 1997 | Established the branded market |
| Core patent protection | Through 2012 in the United States | Delayed broad generic competition |
| Generic U.S. approvals and launches | 2012 | Initiated rapid price and share erosion |
| Post-exclusivity market | 2013 onward | Dominated by generic suppliers |
The branded product may remain available in some jurisdictions, but brand economics are no longer comparable with the pre-generic period.
What patents protect clopidogrel bisulfate today?
The commercially important composition and active-ingredient patent protection has expired in major markets. No remaining core patent is expected to prevent ordinary generic production of clopidogrel bisulfate tablets.
Potentially relevant intellectual-property categories include:
- Salt and crystalline-form claims
- Process patents for stereoselective synthesis
- Tablet formulation claims
- Immediate-release dosage-form claims
- Combination-product claims
- Manufacturing know-how and impurity-control methods
- Regional patents covering specific formulations or processes
These rights are materially less important than the expired core compound patent. A process patent could affect a particular manufacturer, but it generally would not recreate product-level exclusivity where alternative manufacturing routes are available.
How strong is the current clopidogrel patent estate?
The current estate is weak from a market-exclusion perspective. Its strength is higher for manufacturing control, impurity specifications, and specific formulations than for the active pharmaceutical ingredient itself.
| Patent category | Current competitive value |
|---|---|
| Core clopidogrel compound | Low; expired |
| Clopidogrel bisulfate salt | Low to moderate, depending on jurisdiction and claim scope |
| Standard 75 mg tablet | Low |
| Manufacturing process | Moderate for affected suppliers |
| Combination products | Moderate where claims remain enforceable |
| New delivery systems | Potentially higher, but limited commercial relevance |
What is the FDA and Orange Book status of clopidogrel?
Clopidogrel is an FDA-approved small-molecule drug with extensive generic availability. It is not a biologic and does not create biosimilar exposure. The relevant competitive pathway is abbreviated new drug application approval under Section 505(j) of the Federal Food, Drug, and Cosmetic Act.
The Orange Book historically listed the patents associated with Plavix. The original patent barriers have expired, and standard clopidogrel tablets are generally available without a current core Orange Book patent barrier preventing generic competition.
FDA regulatory considerations include:
- Demonstration of pharmaceutical equivalence
- Bioequivalence to the reference product
- Control of the clopidogrel active moiety and related impurities
- Manufacturing compliance under current good manufacturing practice requirements
- Accurate labeling for approved cardiovascular indications
- Stability and dissolution performance for tablet products
The active metabolite is formed through hepatic metabolism, with CYP2C19 variability affecting response in some patients. Pharmacogenomic labeling and clinical management may influence product selection, although they do not create meaningful exclusivity for standard generic tablets.
Which companies compete in the clopidogrel market?
Competition is highly fragmented. Major generic manufacturers and regional suppliers have marketed clopidogrel products in the United States, Europe, India, China, and other markets. Depending on jurisdiction and product status, relevant companies have included:
- Teva Pharmaceutical Industries
- Mylan, now part of Viatris
- Sandoz
- Dr. Reddy's Laboratories
- Lupin
- Sun Pharmaceutical Industries
- Cipla
- Torrent Pharmaceuticals
- Zydus Lifesciences
- Aurobindo Pharma
- Apotex
- Hikma Pharmaceuticals
- Various Chinese and regional manufacturers
The competitive advantage is primarily operational rather than scientific. Important factors include manufacturing cost, regulatory-file quality, supply reliability, hospital-tender access, distribution reach, and the ability to maintain acceptable margins at low prices.
How does clopidogrel compare with ticagrelor and prasugrel?
Clopidogrel remains the low-cost incumbent, while ticagrelor and prasugrel compete on potency, onset, and guideline positioning in selected patients.
| Attribute | Clopidogrel | Ticagrelor | Prasugrel |
|---|---|---|---|
| Drug class | P2Y12 inhibitor | P2Y12 inhibitor | P2Y12 inhibitor |
| Administration | Once daily | Twice daily | Once daily |
| Generic availability | Broad | Increasing after loss of exclusivity in major markets | Generic availability in major markets |
| Cost | Lowest | Higher in many markets | Higher than clopidogrel in many markets |
| Key use | Maintenance and broad secondary prevention | Selected acute coronary syndrome patients | Selected PCI patients |
| Main commercial risk to clopidogrel | Price erosion | Clinical substitution | Clinical substitution |
| Main commercial advantage | Cost and familiarity | Faster and more consistent platelet inhibition | Potent platelet inhibition |
A broader generic market for ticagrelor and prasugrel could increase pressure on clopidogrel. However, the low price of clopidogrel creates a durable floor for demand, particularly when treatment extends beyond the acute phase.
What generic entry risks affect clopidogrel sales?
Generic entry is no longer an emerging risk; it is the defining market condition. Future revenue risk comes from additional suppliers, tender rebidding, and therapeutic substitution.
The principal risks are:
- Further price reductions in the United States and Europe
- Hospital and government procurement consolidation
- Manufacturing outages or product recalls
- Substitution by ticagrelor or prasugrel in acute coronary syndrome
- Greater use of aspirin-only regimens where clinically appropriate
- Clinical concerns about CYP2C19 poor metabolizers
- Loss of branded share in markets where Plavix retains residual recognition
The principal protections are:
- Low manufacturing cost
- Extensive physician familiarity
- Broad guideline inclusion
- Long treatment duration
- Availability in oral tablet form
- Strong use in cost-sensitive health systems
What litigation and settlement agreements affect clopidogrel?
The central historic litigation involved Sanofi, Bristol-Myers Squibb, and generic challengers over the Plavix patent estate. Generic challenges accelerated the transition from branded exclusivity to broad generic availability. The major commercial result was generic entry in 2012 rather than continued protection through the full potential life of the branded franchise.
No active litigation is broadly recognized as capable of restoring core clopidogrel exclusivity in the United States. Any current dispute is more likely to involve a supplier-specific manufacturing process, regulatory action, product-quality issue, or regional formulation claim.
Settlement agreements associated with the original patent disputes are commercially relevant because they shaped launch timing and authorized-generic competition. They do not provide an ongoing barrier to ordinary generic clopidogrel sales.
Are there licensing deals for clopidogrel bisulfate?
Clopidogrel has had extensive historical commercialization through the Sanofi and Bristol-Myers Squibb alliance. Those arrangements supported global development, regulatory filings, and distribution of Plavix.
The current generic market is less dependent on high-value licensing. Commercial agreements generally concern:
- Regional distribution
- Contract manufacturing
- Authorized generic supply
- Hospital and government tenders
- Technology transfer
- API sourcing
- Portfolio licensing by geographic market
The value of a new clopidogrel license is therefore limited unless it includes a differentiated formulation, a cost advantage, a major regulated-market approval, or guaranteed procurement access.
What manufacturing and IP barriers remain?
The active ingredient is chemically established, but quality and supply execution remain important. Manufacturers must manage stereochemistry, impurity profiles, API consistency, tablet dissolution, packaging stability, and regulatory inspection requirements.
Manufacturing barriers are highest for:
- Suppliers seeking approvals in tightly regulated markets
- Companies without validated API supply
- Manufacturers dependent on a single production site
- Products requiring multiple regional dossiers
- Suppliers competing in low-margin tenders
The most commercially defensible position is a reliable, multi-market generic platform rather than a standalone patent position.
What revenue exposure exists for manufacturers?
Clopidogrel is unlikely to be a major growth product for diversified pharmaceutical companies. It is more valuable as part of a cardiovascular generic portfolio that includes aspirin, statins, antihypertensives, anticoagulants, and newer antiplatelet agents.
Revenue exposure is highest for companies that:
- Rely heavily on public tenders
- Operate with limited product differentiation
- Have concentrated exposure to one geography
- Lack alternate P2Y12 products
- Depend on a single API supplier
For large generic companies, clopidogrel contributes recurring but declining revenue. For smaller regional manufacturers, a tender win can produce meaningful short-term sales but also creates margin risk when competitors rebid aggressively.
What generic launch scenarios are most likely?
The market is already generic, so future launch scenarios involve portfolio expansion rather than first entry.
Base scenario
Existing suppliers retain share while prices decline gradually. Emerging-market volume grows, offsetting part of the mature-market contraction.
Upside scenario
A manufacturer gains hospital-tender access in India, China, Latin America, or the Middle East and combines clopidogrel with a broader cardiovascular portfolio. Volume growth outweighs price erosion.
Downside scenario
A supplier loses regulatory approval, faces a manufacturing interruption, or is displaced in a major tender. The product remains commercially available, but individual-company revenue drops sharply.
Key Takeaways
- Clopidogrel bisulfate is a mature generic antiplatelet market with durable volume and declining value.
- The original Plavix patent estate expired in the United States in 2012.
- Standard clopidogrel tablets face no meaningful remaining core patent barrier in major markets.
- Global sales are estimated at approximately $1.3 billion to $2.0 billion in 2024.
- A base-case model projects sales declining from $1.6 billion in 2024 to $1.2 billion in 2030.
- Asia-Pacific offers the strongest volume-growth opportunity, while North America and Europe remain highly price competitive.
- Ticagrelor and prasugrel create clinical substitution risk, especially in acute coronary syndrome.
- No biosimilar risk exists because clopidogrel is a small molecule; generic competition is the relevant threat.
- Manufacturing reliability, regulatory compliance, tender access, and low-cost API supply are more important than core patent protection.
- The strongest commercial strategy is a broad cardiovascular generic portfolio rather than a standalone clopidogrel product.
FAQs
Does clopidogrel still have patent protection?
Core patent protection for clopidogrel has expired in major markets, including the United States. Residual process or formulation claims may exist in specific jurisdictions but do not generally prevent ordinary generic tablet sales.
Is Plavix still commercially significant?
Plavix retains brand recognition and may remain marketed in some countries, but its global revenue is far below pre-generic levels. Generic clopidogrel accounts for most current market volume.
Which market has the highest clopidogrel growth potential?
Asia-Pacific has the strongest volume potential because of population size, cardiovascular disease burden, and expanding access to secondary prevention. Revenue growth is constrained by low prices and government procurement.
Can a new clopidogrel formulation obtain market exclusivity?
A differentiated formulation could qualify for patent protection or regulatory exclusivity if it meets applicable requirements. A standard 75 mg immediate-release tablet is unlikely to create meaningful exclusivity because equivalent products are widely available.
Will ticagrelor replace clopidogrel?
Ticagrelor will continue to take share in selected acute coronary syndrome populations, but broad replacement is unlikely. Clopidogrel's low cost, once-daily dosing, long clinical history, and established role in maintenance therapy support continuing demand.
References
- U.S. Food and Drug Administration. (1997). Plavix (clopidogrel bisulfate) prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations.
- U.S. Patent and Trademark Office. (1989). U.S. Patent No. 4,847,265: Dextro-rotatory enantiomer of methyl alpha-(2-chlorophenyl)-6,7-dihydrothieno[3,2-c]pyridine-5(4H)-acetate.
- Sanofi. (2012). Annual report.
- Bristol-Myers Squibb. (2012). Annual report.
- Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations.
- Levine, G. N., et al. (2016). 2016 ACC/AHA guideline focused update on duration of dual antiplatelet therapy in patients with coronary artery disease. Circulation, 134(10), e123-e155.
More… ↓
