Share This Page
Drug Sales Trends for CARAFATE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for CARAFATE (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
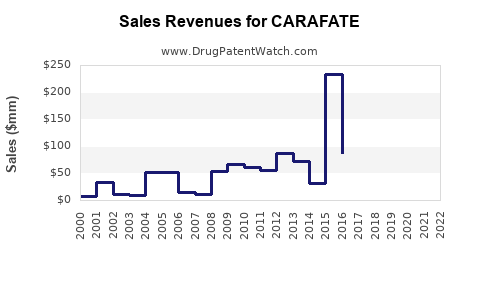
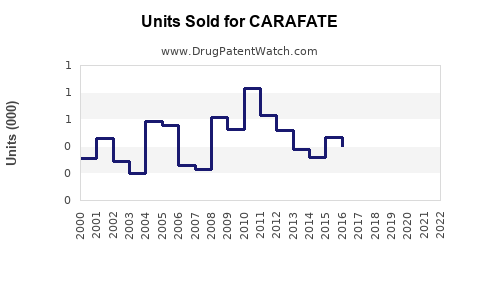
Annual Sales Revenues and Units Sold for CARAFATE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| CARAFATE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| CARAFATE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| CARAFATE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| CARAFATE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
CARAFATE Market Analysis and Sales Projections: Sucralfate Market Size, Competition, Patents, and Generic Outlook
CARAFATE is the branded formulation of sucralfate, an ulcer-protective agent approved in the United States for short-term treatment of active duodenal ulcers. The product has limited commercial value as a branded medicine because sucralfate is available from multiple generic manufacturers, has no meaningful remaining U.S. composition-of-matter exclusivity, and faces therapeutic substitution from proton-pump inhibitors and H2-receptor antagonists. Public filings do not separately disclose CARAFATE sales, so revenue projections require a bottom-up estimate rather than a company-reported baseline.
The commercial outlook is stable to declining in branded terms. Generic sucralfate demand is likely to remain concentrated in lower-cost tablets and oral suspension, with oral suspension retaining a higher value per prescription because of manufacturing complexity, packaging requirements, and lower generic participation.
What is CARAFATE and how large is its addressable market?
CARAFATE contains sucralfate, a locally acting gastrointestinal protectant. It forms an adherent barrier at ulcer sites and is administered orally, generally on an empty stomach. The U.S. label covers short-term treatment of active duodenal ulcer, with a recommended adult course of up to eight weeks.[1]
CARAFATE is marketed in tablet and oral suspension forms. Generic sucralfate is available in the same principal dosage forms. The drug is used less frequently than proton-pump inhibitors for broad acid-related disorders because it does not suppress gastric acid production and has a more burdensome dosing schedule.
U.S. product profile
| Attribute | CARAFATE |
|---|---|
| Active ingredient | Sucralfate |
| Therapeutic class | Gastrointestinal mucosal protectant |
| Original U.S. approval | 1980s |
| U.S. dosage forms | 1-gram tablets; 1-gram/10 mL oral suspension |
| Main approved use | Short-term treatment of active duodenal ulcer |
| Prescription status | Prescription |
| Primary competitors | Generic sucralfate, proton-pump inhibitors, H2 antagonists |
| Current commercial position | Mature branded product with generic competition |
| Biosimilar exposure | None |
| Key market constraint | Low-cost substitution and limited clinical differentiation |
The relevant market is not the total acid-related prescription market. CARAFATE competes in a narrower segment consisting of ulcer-protective therapies, selected gastroesophageal conditions, medication-related mucosal injury, and off-label inpatient or outpatient gastrointestinal use.
What are CARAFATE sales and market-share trends?
AbbVie and predecessor companies have not generally reported CARAFATE as a standalone revenue line in recent public financial filings. The brand’s revenue is therefore not directly measurable from company disclosures. The commercial market is dominated by generic sucralfate rather than the CARAFATE label.
A reasonable market interpretation is:
- The branded CARAFATE share is small relative to total U.S. sucralfate volume.
- Generic tablets account for most unit volume.
- Oral suspension generates a disproportionate share of product revenue.
- Hospital and institutional demand can fluctuate with formulary decisions and supply availability.
- The total sucralfate market is mature, with limited volume growth.
- Revenue declines are more likely to result from generic substitution and price erosion than from rapid clinical obsolescence.
Estimated U.S. revenue structure
Because no authoritative public source reports total CARAFATE and generic sucralfate sales together, the following is a scenario model, not reported market data.
| Segment | Estimated share of U.S. sucralfate revenue | Commercial characteristics |
|---|---|---|
| Generic tablets | 45%-60% | High substitution, low unit pricing |
| Generic oral suspension | 25%-40% | Higher unit value and greater supply sensitivity |
| Branded CARAFATE | 5%-15% | Prescriber recognition but limited formulary advantage |
| Institutional and other channels | 10%-20% | Variable purchasing and contract pricing |
The ranges reflect typical mature-generic market behavior and should not be treated as audited market shares.
What are CARAFATE sales projections through 2030?
A precise forecast cannot be derived from public filings because standalone brand sales, prescription volume, net pricing, and channel mix are not disclosed. A scenario-based forecast is more appropriate.
The base case assumes:
- U.S. branded CARAFATE revenue of approximately $10 million to $20 million in 2025.
- Annual branded revenue decline of 5% to 10%.
- Generic sucralfate revenue that remains broadly stable in volume.
- Net price erosion of 2% to 5% annually for tablets.
- More stable pricing for oral suspension because of fewer suppliers and higher manufacturing costs.
- No major label expansion or new delivery technology.
Base-case branded CARAFATE projection
| Year | Estimated U.S. branded revenue | Annual change |
|---|---|---|
| 2025 | $10 million-$20 million | Baseline |
| 2026 | $9 million-$18 million | -5% to -10% |
| 2027 | $8 million-$17 million | -5% to -10% |
| 2028 | $7 million-$16 million | -5% to -10% |
| 2029 | $6 million-$15 million | -5% to -10% |
| 2030 | $5 million-$14 million | -5% to -10% |
Total U.S. sucralfate projection
A broader market estimate, including generic tablets, generic suspension, and branded CARAFATE, is more commercially relevant. Under a base case of approximately $50 million to $100 million in 2025 U.S. product revenue, the market could reach approximately $43 million to $95 million by 2030.
| Scenario | 2025 U.S. market | 2030 U.S. market | Implied trend |
|---|---|---|---|
| Downside | $40 million-$60 million | $25 million-$45 million | Faster substitution and declining prescriptions |
| Base case | $50 million-$100 million | $43 million-$95 million | Stable volume with moderate price erosion |
| Upside | $80 million-$125 million | $80 million-$135 million | Suspension shortages, institutional demand, or renewed prescribing |
These ranges are directional estimates. They are not company guidance or audited market forecasts.
When does CARAFATE lose exclusivity?
CARAFATE has already lost practical U.S. market exclusivity. Sucralfate is an established small-molecule active ingredient, and generic products have been available for many years.
The principal commercial barriers are no longer patent exclusivity. They are:
- Manufacturing economics.
- FDA approval and bioequivalence requirements.
- Oral suspension production and quality control.
- Supply reliability.
- Pharmacy substitution.
- Formulary contracting.
- Brand recognition in selected prescriber segments.
The FDA Orange Book should be reviewed for current listed patents and exclusivity associated with any specific CARAFATE application.[2] Older drug products may have historical listings that no longer create a meaningful barrier to generic entry. The presence of an Orange Book listing does not by itself establish an enforceable remaining exclusivity period.
Patent and exclusivity position
| Issue | CARAFATE assessment |
|---|---|
| New chemical entity exclusivity | Expired |
| Orphan-drug exclusivity | Not applicable |
| Biologic exclusivity | Not applicable |
| Pediatric exclusivity | No commercially relevant current protection identified |
| Composition-of-matter patent | Expired or commercially immaterial |
| Formulation patent risk | Low for standard tablet and suspension products |
| Method-of-use patent risk | Low for the established ulcer indication |
| Generic entry | Already established |
| Paragraph IV exposure | Historical or product-specific; not a current market-wide barrier |
What patents protect CARAFATE formulations?
The original commercial value of CARAFATE came from the active ingredient and its use as a gastric mucosal protectant, not from a currently dominant platform patent.
Potentially relevant intellectual-property categories include:
- Sucralfate composition and chemical preparation.
- Tablet manufacturing and excipient systems.
- Oral suspension stability and viscosity control.
- Packaging systems for suspension products.
- Manufacturing processes that improve particle size, dispersion, or uniformity.
- Combination products or new administration schedules.
Standard sucralfate tablets are difficult to protect with broad, durable patents because generic manufacturers can generally use different excipients and manufacturing processes while delivering the same active ingredient and strength.
Oral suspension products have more defensible technical features. A company could pursue patents covering:
- Sedimentation control.
- Redispersibility.
- Viscosity.
- Particle-size distribution.
- Taste masking.
- Preservative systems.
- Container closure systems.
- Extended stability.
Those rights would likely provide narrower protection than a composition-of-matter patent and could be designed around by competitors.
What is the FDA regulatory status of CARAFATE?
CARAFATE is an FDA-approved prescription drug. Generic sucralfate products are generally approved through abbreviated new drug applications, which require demonstration of pharmaceutical equivalence and bioequivalence to the relevant reference product.[1,3]
FDA regulatory considerations
Tablets present a relatively straightforward generic pathway. Oral suspension products may face greater development and manufacturing complexity because performance depends on physical characteristics, uniformity, resuspendability, and stability.
The main regulatory risks are:
- Manufacturing-site compliance.
- Product-quality deviations.
- Suspension potency uniformity.
- Microbial control.
- Container and closure integrity.
- Labeling differences between brand and generic products.
- Supply interruptions caused by limited manufacturing capacity.
The FDA-approved indication is narrower than the full range of real-world sucralfate use. Off-label use may support demand, but it does not create additional regulatory exclusivity.
Which companies compete with CARAFATE?
The competitive field includes generic pharmaceutical manufacturers and therapeutic substitutes.
Direct sucralfate competitors
Generic sucralfate has been marketed by multiple U.S. suppliers over time, including manufacturers such as:
- Teva Pharmaceuticals.
- Rising Pharmaceuticals.
- Upsher-Smith.
- Amneal Pharmaceuticals.
- Major Pharmaceuticals and other contracted-label suppliers.
- Regional and institutional generic suppliers.
Supplier participation changes as products are discontinued, acquired, or removed from distribution. The FDA Orange Book and current wholesaler listings are the appropriate sources for live supplier verification.[2]
Therapeutic competitors
| Drug class | Examples | Competitive effect |
|---|---|---|
| Proton-pump inhibitors | Omeprazole, pantoprazole, lansoprazole | Strong substitution for acid-mediated disorders |
| H2 antagonists | Famotidine | Lower-cost alternative in selected conditions |
| Antacids | Calcium carbonate, magnesium hydroxide | Compete in symptom relief |
| Misoprostol | Generic misoprostol | Niche use for medication-related mucosal injury |
| Alginate products | Combination alginate products | Compete in reflux-related symptoms |
| Bismuth products | Bismuth subsalicylate | Compete in selected gastrointestinal indications |
CARAFATE’s most important competitive disadvantage is dosing burden. Patients often take sucralfate multiple times daily and must separate it from other medicines. Proton-pump inhibitors typically have simpler dosing and broader guideline support for acid suppression.
What generic launch risks exist for CARAFATE?
Generic launch risk is no longer a future event. Generic entry has already occurred and is the central feature of the market.
Future competitive risk is concentrated in additional generic suppliers, private-label substitution, and price competition. The risk differs by dosage form.
Tablets
Tablet competition is structurally intense. A new entrant can face:
- Low reimbursement.
- Limited pharmacy preference.
- High substitution rates.
- Contracting pressure.
- Rapid price erosion.
- Difficulty achieving scale.
Oral suspension
Suspension competition is more balanced. Entrants may encounter:
- Higher development costs.
- More demanding process controls.
- Fewer qualified manufacturers.
- Greater vulnerability to shortages.
- Higher value per unit.
- Institutional purchasing opportunities.
A manufacturer with reliable suspension capacity may obtain better economics than a tablet-only supplier, but the market remains too small to support large-scale investment without a clear supply or contracting advantage.
What patent litigation and Paragraph IV challenges affect CARAFATE?
No current, market-defining CARAFATE patent litigation or settlement structure is apparent from the established generic status of sucralfate. Historical Paragraph IV activity may have occurred as generic applicants challenged older listed patents, but such events no longer control the overall market because multiple generic products have entered.
For a new sucralfate product, litigation risk would more likely involve:
- A formulation patent for oral suspension.
- A process patent.
- A packaging or stability patent.
- Trade-secret allegations involving manufacturing methods.
- Contract or supply disputes rather than core patent litigation.
A Paragraph IV certification against a newly listed formulation patent could delay approval or trigger litigation, but it would not restore exclusivity to the legacy CARAFATE product.
How strong is the CARAFATE patent estate?
The practical patent estate is weak for the legacy product and potentially moderate for a narrowly defined next-generation formulation.
| Patent category | Strength | Commercial assessment |
|---|---|---|
| Active-ingredient patent | Very low | Expired or irrelevant |
| Standard tablet formulation | Low | Easy design-around risk |
| Standard oral suspension | Low to moderate | Technical differentiation possible |
| Advanced suspension system | Moderate | Dependent on claim scope and data |
| New combination product | Moderate | Requires clinical and regulatory support |
| Manufacturing process | Moderate | Enforcement may be difficult without access to process evidence |
| Method of use | Low | Established indication and limited novelty |
A new entrant should not rely on legacy CARAFATE patents for market protection. The stronger strategy would be a differentiated formulation, a reliable shortage-resistant supply chain, or a combination of product, device, and distribution advantages.
What licensing deals affect CARAFATE?
No major current licensing transaction is central to the U.S. CARAFATE market. The product has passed through historical ownership and marketing arrangements, but current commercial value is primarily tied to manufacturing and distribution rather than an active licensing platform.
Potential transaction value would likely come from:
- Acquisition of an approved oral suspension product.
- Purchase of an abbreviated new drug application.
- Contract manufacturing rights.
- Brand-to-generic conversion.
- Regional distribution rights.
- Portfolio bundling with gastrointestinal products.
A standalone CARAFATE brand acquisition would likely command a modest valuation unless it included durable supply contracts, a differentiated suspension formulation, or a strong institutional customer base.
How does CARAFATE compare with proton-pump inhibitors?
| Factor | CARAFATE | Proton-pump inhibitors |
|---|---|---|
| Mechanism | Physical mucosal barrier | Acid suppression |
| Dosing convenience | Less convenient | Generally more convenient |
| Generic availability | Extensive | Extensive |
| Clinical use | Narrower | Broader |
| Brand pricing power | Low | Low for legacy products |
| Formulation opportunity | Oral suspension differentiation | Capsules, tablets, delayed-release systems |
| Growth outlook | Flat to declining | Mature but larger market |
| Main commercial advantage | Local barrier action | Strong guideline familiarity and convenience |
CARAFATE can retain demand where clinicians seek local mucosal protection, where acid suppression is insufficient, or where suspension administration is preferred. It is less competitive for routine gastroesophageal reflux disease and broad dyspepsia treatment.
What is the revenue exposure and investment outlook for CARAFATE?
CARAFATE is unlikely to be material to the revenue outlook of a diversified pharmaceutical company. The product’s value is more relevant to a specialty-generic manufacturer, contract manufacturer, or portfolio buyer seeking recurring demand from a mature gastrointestinal product.
Revenue drivers
- Generic supply availability.
- Oral suspension pricing.
- Institutional contracts.
- Prescriber familiarity.
- Product shortages among competitors.
- Pharmacy substitution rules.
- Manufacturing cost control.
Revenue risks
- Continued shift toward proton-pump inhibitors.
- Generic price compression.
- Product discontinuations.
- Reimbursement reductions.
- Low market growth.
- Manufacturing or quality failures.
- Declining use of sucralfate for routine ulcer care.
The best commercial case is a supply-constrained oral suspension product with efficient manufacturing and a reliable distribution network. The weakest case is a new tablet entrant without a cost or contracting advantage.
Key Takeaways
- CARAFATE is the branded version of sucralfate, an established prescription gastrointestinal protectant.
- U.S. generic competition is already entrenched.
- Public filings do not provide standalone CARAFATE sales.
- A reasonable base case places branded U.S. revenue at approximately $10 million to $20 million in 2025, declining to $5 million to $14 million by 2030.
- Total U.S. sucralfate revenue, including generics, could remain approximately $50 million to $100 million in 2025 and $43 million to $95 million in 2030 under a base case.
- Oral suspension has stronger commercial characteristics than tablets because of manufacturing complexity and lower supplier density.
- Legacy composition, method-of-use, and standard formulation patents do not provide meaningful current exclusivity.
- The principal risks are generic price erosion, therapeutic substitution, and manufacturing disruption.
- A differentiated suspension formulation or dependable shortage-resistant supply chain offers the clearest opportunity for new investment.
FAQs
Is CARAFATE still a profitable drug?
CARAFATE can generate recurring revenue, but its profitability is constrained by generic substitution, low branded pricing power, and mature demand. Oral suspension is more attractive than tablets.
Can a generic company still launch sucralfate?
Yes. Generic sucralfate products are already marketed. A new applicant would need FDA approval and must compete on price, supply reliability, distribution, or dosage-form differentiation.
Does CARAFATE have biosimilar competition?
No. CARAFATE is a small-molecule drug, not a biologic. The relevant competitors are generic sucralfate products, not biosimilars.
Is sucralfate oral suspension more valuable than sucralfate tablets?
Usually. Suspension manufacturing is more complex, supplier participation is lower, and supply disruptions can support stronger pricing. Tablets face more intense generic competition.
Could a new CARAFATE formulation obtain patent protection?
A new suspension, combination product, delivery system, or manufacturing process could potentially receive patent protection if it satisfies novelty, non-obviousness, and enablement requirements. Protection would likely be narrower than the original active-ingredient patent.
References
- U.S. Food and Drug Administration. (2023). CARAFATE (sucralfate) oral suspension and tablet prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2024). Generic drug facts and abbreviated new drug application requirements.
More… ↓
