Drug Sales Trends for ALPHAGAN P
Payment Methods and Pharmacy Types for ALPHAGAN P (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
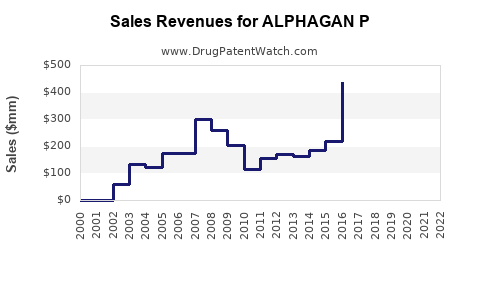
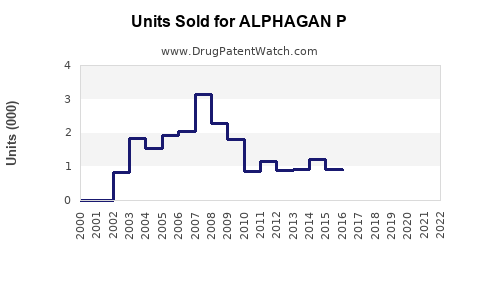
Annual Sales Revenues and Units Sold for ALPHAGAN P
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ALPHAGAN P | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ALPHAGAN P | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ALPHAGAN P | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ALPHAGAN P | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ALPHAGAN P | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ALPHAGAN P | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Alphagan P Market Analysis and Sales Projections
Alphagan P is a brimonidine tartrate ophthalmic solution marketed for lowering intraocular pressure in patients with open-angle glaucoma or ocular hypertension. The product has largely lost its U.S. franchise value because brimonidine generics are widely available, core formulation protections have expired or become commercially ineffective, and payers generally favor lower-cost alternatives. Current commercial opportunity is concentrated in differentiated low-concentration formulations, preservative-tolerant patients, and markets where generic substitution is limited.
Standalone Alphagan P revenue is not separately disclosed by AbbVie. The projections below are therefore modeled estimates rather than reported company sales.
What is Alphagan P and how does it compete?
Alphagan P contains brimonidine tartrate, an alpha-2 adrenergic agonist. It reduces aqueous humor production and increases uveoscleral outflow. The product is used two to three times daily depending on the concentration and prescribing instructions.
| Product | Active ingredient | Concentration | Primary use | Commercial status |
|---|---|---|---|---|
| Alphagan P | Brimonidine tartrate | 0.1% | Glaucoma and ocular hypertension | Branded product with generic competition |
| Alphagan P | Brimonidine tartrate | 0.15% | Glaucoma and ocular hypertension | Branded product with generic competition |
| Generic brimonidine | Brimonidine tartrate | 0.1%, 0.15%, 0.2% | Glaucoma and ocular hypertension | Broad generic availability |
| Timolol ophthalmic | Timolol maleate | 0.25%, 0.5% | Glaucoma and ocular hypertension | Mature generic market |
| Latanoprost | Prostaglandin analog | 0.005% | Glaucoma and ocular hypertension | Large generic market |
| Dorzolamide/timolol | Fixed combination | Multiple | Glaucoma and ocular hypertension | Generic and branded competition |
| Netarsudil | Rho kinase inhibitor | 0.02% | Glaucoma and ocular hypertension | Branded, newer mechanism |
| Bimatoprost | Prostaglandin analog | 0.01%, 0.03% | Glaucoma and ocular hypertension | Branded and generic competition |
The main commercial distinction of Alphagan P is its Purite-preserved formulation. Purite is converted into naturally occurring components after instillation and was designed to improve ocular tolerability relative to older benzalkonium chloride-preserved products. The clinical benefit is most relevant for patients with ocular-surface disease or intolerance to conventional preservatives. FDA labeling identifies brimonidine tartrate ophthalmic solution as a treatment for elevated intraocular pressure in open-angle glaucoma and ocular hypertension.[1]
What is the FDA regulatory status of Alphagan P?
Alphagan P is an FDA-approved ophthalmic prescription product. The 0.15% formulation received FDA approval before the 0.1% formulation, which was introduced to provide a lower brimonidine concentration while maintaining pressure-lowering activity.
FDA regulatory characteristics include:
- Prescription-only ophthalmic solution.
- Small-molecule drug rather than a biologic.
- No biosimilar pathway applies.
- Generic applicants generally use an abbreviated new drug application, or ANDA.
- Therapeutic equivalence depends on the approved generic product, concentration, dosage form, and FDA Orange Book designation.
- Common adverse effects include allergic conjunctivitis, conjunctival hyperemia, dry mouth, and fatigue.[1]
Generic brimonidine products have entered the market in multiple strengths. The availability of generic products materially limits Alphagan P’s ability to preserve premium pricing.
What is the Orange Book status of Alphagan P?
The Orange Book historically listed patents and regulatory exclusivities associated with Alphagan P and related brimonidine formulations. The commercial relevance of those listings has declined as key protections expired and generic competition expanded.
| Regulatory issue | Alphagan P impact |
|---|---|
| Active ingredient patent | Expired or commercially exhausted |
| Formulation protection | Limited remaining blocking value in the U.S. |
| Method-of-use protection | Narrow value because glaucoma treatment is established and generic labels cover common indications |
| Orange Book listing | Historical listings may remain relevant to litigation records, but they do not prevent broad generic substitution |
| Pediatric exclusivity | Not a current commercial barrier |
| New chemical entity exclusivity | Expired |
| Biosimilar exposure | None; brimonidine is a small molecule |
| ANDA competition | High |
A current Orange Book review should be performed against the exact NDA and strength because FDA listings can change through patent delisting, expiration, or product discontinuation updates.[2] The practical conclusion is unchanged: Alphagan P is a post-exclusivity brand facing generic substitution.
When did Alphagan P lose exclusivity?
Alphagan P lost effective market exclusivity after the expiration of its principal drug and formulation protections and the launch of generic brimonidine products. The exact timing differs by strength, formulation, patent challenge, and generic approval.
A simplified exclusivity timeline is:
| Period | Commercial event | Market consequence |
|---|---|---|
| Initial launch period | Allergan commercializes brimonidine products | Branded pricing and ophthalmology promotion |
| Early formulation expansion | Lower-concentration Alphagan P formulation introduced | Differentiation based on tolerability and concentration |
| Patent challenge period | Generic manufacturers pursue ANDA approvals and possible Paragraph IV certifications | Litigation and launch uncertainty |
| Post-expiration period | Generic brimonidine products enter or expand | Rapid price erosion and payer substitution |
| Current market | Brand remains available but competes against low-cost products | Declining brand volume and limited pricing power |
Which companies are challenging Alphagan P with generics?
The U.S. brimonidine market has included multiple generic ophthalmic manufacturers and suppliers. Depending on concentration and product availability, competitors have included large generic companies such as Teva, Sandoz, Apotex, Dr. Reddy’s Laboratories, Rising Pharmaceuticals, and other ANDA holders.
Generic competition is stronger for 0.2% brimonidine than for the branded Alphagan P concentrations because 0.2% products have been available for many years. Competition for 0.1% and 0.15% products also limits brand pricing because physicians and pharmacies can substitute among therapeutically similar brimonidine formulations.
What is the Paragraph IV risk?
Paragraph IV risk was most significant before the relevant Alphagan P patent protections expired. An ANDA applicant could certify that a listed patent was invalid, unenforceable, or not infringed. Such a certification could trigger Hatch-Waxman litigation and a 30-month stay of FDA approval in qualifying circumstances.[3]
That risk is now primarily historical for Alphagan P. Any remaining litigation would more likely involve:
- A specific formulation patent.
- A manufacturing process patent.
- A narrow method-of-use claim.
- Product-specific patent listing disputes.
- Regulatory exclusivity or labeling issues.
A broad reversion to branded exclusivity is unlikely absent a new formulation or delivery technology.
What patents protect Alphagan P?
The historical Alphagan P estate focused on the following technical areas:
- Brimonidine ophthalmic formulations.
- Lower-concentration brimonidine solutions.
- Purite or oxidative preservative systems.
- Ocular tolerability and preservative performance.
- Methods for reducing intraocular pressure.
- Packaging, stability, and manufacturing characteristics.
The strongest historical differentiation was formulation-based rather than mechanism-based. Brimonidine itself is an established active ingredient, and the glaucoma indication is conventional. As a result, composition and preservative claims were more commercially important than broad method-of-use claims.
Current patent strength is best characterized as low for the legacy product and moderate for a new brimonidine formulation supported by fresh clinical or device claims. A new product could obtain protection around:
- A novel preservative system.
- A sustained-release insert or implant.
- A lower-frequency delivery regimen.
- A combination with another glaucoma drug.
- A formulation that improves ocular-surface tolerability.
- A device or container-closure system.
What formulations are protected by Alphagan P?
The commercial differentiation of Alphagan P is tied to its low-concentration formulations and Purite preservation system. These features can support product preference in patients who experience irritation from conventional preserved eye drops.
| Formulation attribute | Value to Alphagan P | Generic erosion risk |
|---|---|---|
| Brimonidine tartrate active ingredient | Provides pressure-lowering effect | Very high |
| 0.1% concentration | Lower drug concentration and differentiated tolerability profile | High |
| 0.15% concentration | Branded formulation differentiation | High |
| Purite preservative | Supports ocular-surface positioning | Moderate to high |
| Multi-dose bottle | Convenient and inexpensive | High |
| Ophthalmic drop delivery | Standard route | Very high |
A formulation patent may remain legally relevant after commercial exclusivity has weakened. Generic manufacturers can avoid infringement through alternative concentrations, preservatives, containers, or manufacturing processes. The practical value of any remaining claim therefore depends on claim scope, validity, enforceability, and whether the claim covers a commercially important product.
How large is the Alphagan P market?
The relevant market has three layers:
- The global prescription glaucoma market.
- The brimonidine segment.
- The branded Alphagan P segment.
The global glaucoma market includes prostaglandin analogs, beta blockers, carbonic anhydrase inhibitors, alpha-2 agonists, rho kinase inhibitors, and fixed combinations. Prostaglandin analogs generally lead first-line treatment because of once-daily dosing and strong pressure-lowering performance. Brimonidine is commonly used as adjunctive therapy or as an alternative when other classes are unsuitable.
Estimated U.S. market structure
| Segment | Estimated annual U.S. value, 2024 base case | Growth profile |
|---|---|---|
| Total prescription glaucoma drops | $3.0 billion-$4.5 billion | Low-single-digit growth |
| Brimonidine-containing products | $150 million-$275 million | Flat to declining |
| Branded Alphagan P | $25 million-$75 million | Mid- to high-single-digit decline |
| Generic brimonidine | $125 million-$225 million | Stable volume, declining price |
These are analytical estimates based on the maturity of the glaucoma market, generic availability, historical branded-generic substitution, and the absence of disclosed standalone Alphagan P sales. They should not be interpreted as reported AbbVie product revenue.
What are Alphagan P sales projections?
Base-case projection
The base case assumes continuing U.S. generic substitution, stable glaucoma prevalence, limited brand promotion, and no major product shortage.
| Year | Estimated Alphagan P U.S. sales | Year-over-year change |
|---|---|---|
| 2024 | $45 million-$65 million | Base year |
| 2025 | $41 million-$60 million | -5% to -8% |
| 2026 | $37 million-$55 million | -6% to -8% |
| 2027 | $34 million-$51 million | -5% to -8% |
| 2028 | $31 million-$48 million | -5% to -7% |
| 2029 | $29 million-$45 million | -4% to -7% |
The implied 2024-2029 compound annual decline is approximately 5% to 7%.
Scenario analysis
| Scenario | 2029 U.S. Alphagan P sales | Assumptions |
|---|---|---|
| Downside | $15 million-$25 million | Increased generic substitution, weaker formulary coverage, reduced brand availability |
| Base case | $29 million-$45 million | Gradual brand erosion and stable patient demand |
| Upside | $55 million-$85 million | Generic supply disruption, improved brand contracting, or new tolerability-focused promotion |
The upside case is temporary unless supported by a new clinical, delivery, or reimbursement advantage. A sustained return to historical branded pricing is unlikely in a mature generic market.
How does Alphagan P compare with competing glaucoma drugs?
| Drug class | Main commercial advantage | Main weakness versus Alphagan P |
|---|---|---|
| Latanoprost and other prostaglandins | Once-daily dosing and strong first-line positioning | Ocular hyperemia and class-specific tolerability issues |
| Timolol | Low price and long clinical history | Cardiovascular and pulmonary contraindications |
| Dorzolamide/timolol | Fixed-combination convenience | More frequent dosing and tolerability concerns |
| Brimonidine | Useful adjunctive pressure lowering and alternative mechanism | Three-times-daily dosing, allergy risk, generic price erosion |
| Netarsudil | Newer mechanism and differentiated clinical positioning | High branded price and hyperemia |
| Bimatoprost | Strong pressure lowering | Higher hyperemia and eyelash-related effects in some patients |
Alphagan P’s strongest competitive position is in patients who require add-on therapy and cannot tolerate beta blockers or certain prostaglandin regimens. Its weakest position is routine first-line treatment where generic latanoprost or timolol is preferred.
What generic launch risks exist for Alphagan P?
Generic entry risk is already realized rather than prospective. The principal remaining risks are commercial:
- Additional ANDA approvals for 0.1% or 0.15% products.
- Pharmacy-level substitution.
- Formulary exclusion or higher patient copay tiers.
- Generic price reductions.
- Wholesaler delisting.
- Manufacturing interruptions that affect either brand or generic supply.
- Prescriber migration toward once-daily prostaglandin analogs.
- Reduced physician promotion by the brand owner.
A shortage affecting generic suppliers could temporarily lift Alphagan P demand. That effect would likely be episodic and would not establish durable pricing power.
What licensing deals and litigation affect Alphagan P?
Alphagan P originated in Allergan’s ophthalmology portfolio. AbbVie completed its acquisition of Allergan in 2020, transferring Allergan’s ophthalmic products, including Alphagan P, into AbbVie’s commercial portfolio.[4]
No current major licensing transaction or active high-value patent dispute is broadly associated with Alphagan P’s commercial outlook. Historical Hatch-Waxman disputes and generic-entry proceedings remain relevant to the product’s exclusivity history, but the present investment issue is generic erosion rather than litigation-driven launch uncertainty.
How strong is the Alphagan P patent estate?
| Factor | Assessment |
|---|---|
| Active-ingredient protection | Weak or expired |
| Broad glaucoma method claims | Weak |
| Legacy formulation claims | Limited residual value |
| Preservative-based differentiation | Historically important; current blocking power limited |
| Manufacturing patents | Potentially relevant but unlikely to protect the entire market |
| New product extension opportunity | Moderate if supported by a novel formulation or delivery system |
| Litigation leverage | Low for the legacy product |
| Generic entry barrier | Low |
The legacy estate has low strategic strength. A lifecycle-management program could create stronger protection, but it would need a meaningful clinical or administration advantage rather than a minor concentration change.
What is the commercial outlook for Alphagan P?
Alphagan P is likely to remain a niche branded glaucoma product with declining U.S. sales. Demand will persist because brimonidine is clinically useful, but most of that demand will be captured by generic manufacturers. The brand can retain value through:
- Ocular-surface tolerability positioning.
- Patients with documented intolerance to generic preservatives.
- Physician preference for the branded formulation.
- International markets with slower generic penetration.
- Contracting arrangements with insurers or specialty distributors.
- Combination-product development.
The core product does not have the profile of a high-growth pharmaceutical asset. Its economic value is closer to a mature specialty brand with residual cash flow than to a protected innovation asset.
Key Takeaways
- Alphagan P is a brimonidine tartrate ophthalmic solution for glaucoma and ocular hypertension.
- AbbVie does not separately disclose Alphagan P revenue.
- Estimated U.S. branded sales are approximately $45 million-$65 million in 2024.
- Base-case sales decline to approximately $29 million-$45 million by 2029.
- Generic brimonidine creates the primary commercial threat.
- Biosimilar risk does not apply because brimonidine is a small-molecule drug.
- Legacy formulation and method-of-use protections have limited current blocking value.
- The most valuable remaining differentiation is Purite preservation and perceived ocular tolerability.
- Long-term upside depends on a new delivery system, combination product, or clinically differentiated formulation.
- Alphagan P is a declining mature brand, not a near-term exclusivity-growth asset.
FAQs
Is Alphagan P still under patent protection?
Any remaining patent listings must be reviewed in the current FDA Orange Book for the relevant strength and NDA. Commercially meaningful exclusivity has largely ended because generic brimonidine products are widely available.
Is generic brimonidine as effective as Alphagan P?
FDA-approved generic brimonidine products must meet applicable quality, bioequivalence, and performance requirements. Physicians may still select Alphagan P for individual patients based on tolerability, preservative preference, or clinical response.
Does Alphagan P have biosimilar competition?
No. Biosimilars apply to biological products. Alphagan P contains the small molecule brimonidine tartrate and competes through the generic drug pathway.
Can Alphagan P sales increase during a generic brimonidine shortage?
Yes. A temporary generic supply disruption could shift prescriptions toward Alphagan P. The effect would likely reverse when generic supply normalizes.
What would make Alphagan P commercially attractive again?
A sustained recovery would require a differentiated product, such as once-daily delivery, improved ocular-surface tolerability, a long-acting formulation, a fixed-dose combination, or reimbursement that materially reduces the brand-versus-generic price gap.
References
- U.S. Food and Drug Administration. (2024). Alphagan P prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (n.d.). Abbreviated new drug application approvals and Paragraph IV certifications.
- AbbVie Inc. (2020). Annual report for fiscal year 2020.
More… ↓
