Drug Sales Trends for ADVAIR DISKUS
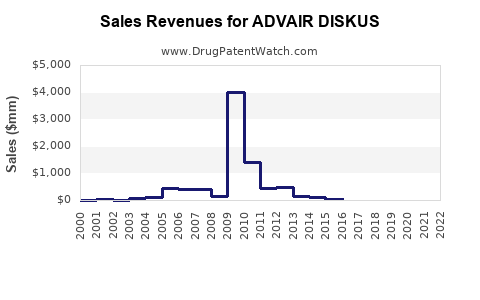
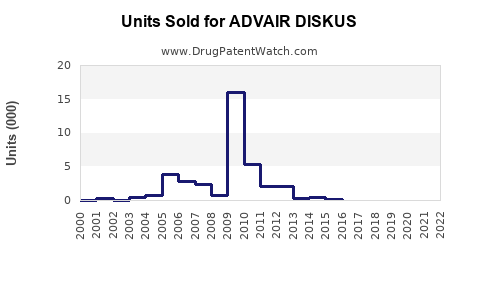
Annual Sales Revenues and Units Sold for ADVAIR DISKUS
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ADVAIR DISKUS | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ADVAIR DISKUS | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ADVAIR DISKUS | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ADVAIR DISKUS | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ADVAIR DISKUS | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ADVAIR DISKUS | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| ADVAIR DISKUS | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Advair Diskus Market Analysis and Sales Projections
Advair Diskus is a mature inhaled respiratory product facing structural revenue erosion from generic fluticasone propionate/salmeterol products, therapeutic substitution to Trelegy Ellipta and Breztri Aerosphere, and payer pressure. The product remains commercially relevant because of its established clinical record, broad prescriber familiarity, and global installed base, but its long-term growth profile is negative.
A base-case model indicates that Advair Diskus and directly substitutable products will continue to lose value through 2030. The branded product is likely to remain commercially viable in selected markets, while most incremental volume will shift to lower-priced generic or authorized-generic products.
What is Advair Diskus and how does it compete?
Advair Diskus combines fluticasone propionate, an inhaled corticosteroid, with salmeterol, a long-acting beta-2 agonist. It is approved for asthma and chronic obstructive pulmonary disease in multiple strengths and is administered through the Diskus dry-powder inhaler.
GlaxoSmithKline, now GSK plc, developed and commercialized Advair. The product was first approved in the United States in 2000 and became one of the largest respiratory medicines globally. Its principal commercial attributes are:
| Attribute | Advair Diskus |
|---|---|
| Active ingredients | Fluticasone propionate and salmeterol |
| Drug class | Inhaled corticosteroid/long-acting beta agonist |
| Primary indications | Asthma and COPD |
| Delivery system | Multi-dose dry-powder Diskus inhaler |
| Originator | GSK |
| U.S. approval | 2000 |
| Main competitors | Wixela Inhub, generic fluticasone/salmeterol, Symbicort, Breo Ellipta, Trelegy Ellipta, Breztri Aerosphere |
| Commercial lifecycle | Mature and declining |
| Principal market risk | Generic substitution and migration to once-daily triple therapy |
Advair’s principal competitive weakness is dosing frequency. Advair Diskus is generally administered twice daily, while Trelegy Ellipta is administered once daily and adds a long-acting muscarinic antagonist for triple therapy.
How large is the Advair Diskus market?
The global Advair market is substantially smaller than its historical peak. GSK reported Advair sales of approximately £3.7 billion in 2015, before intensified generic competition and rapid uptake of newer respiratory products. Sales declined sharply after 2016 as U.S. and international price pressure increased and patients moved to newer inhaled therapies (GSK, 2016; GSK, 2020).
The market now has three distinct segments:
- Branded Advair Diskus.
- Authorized generic or generic fluticasone/salmeterol products.
- Therapeutic substitutes, particularly once-daily inhaled triple therapies.
The directly substitutable market remains important in asthma and COPD, but product revenue is increasingly disconnected from prescription volume because generic prices are materially lower than branded prices.
U.S. market position
The United States remains the most commercially important market for Advair-related products. The U.S. market has experienced:
- Loss of originator exclusivity.
- Approval of substitutable fluticasone/salmeterol products.
- Formulary tier compression.
- Rebates and mandatory generic substitution.
- Migration toward newer inhalers with differentiated dosing or triple therapy.
Wixela Inhub, developed by Mylan and approved in 2019, was the first substitutable generic version of Advair Diskus approved through the abbreviated new drug application pathway. The FDA determined that Wixela Inhub was therapeutically equivalent to Advair Diskus for the approved strengths and indications (FDA, 2019).
The product is delivered through a different inhaler device, which creates a practical distinction between chemical equivalence and device familiarity. Training requirements, inhalation technique, formulary position, and prescriber preference continue to affect actual substitution.
What are the Advair Diskus sales projections through 2030?
A reasonable base-case projection is that branded Advair-related revenue will decline at a mid-to-high single-digit annual rate, while total fluticasone/salmeterol volume declines more slowly because generic products preserve some demand.
The following model is an analytical projection rather than reported company guidance. It uses historical GSK sales trends, the maturity of the product, generic substitution, and competition from newer inhaled therapies.
| Year | Branded Advair revenue index | Direct fluticasone/salmeterol market index | Main market driver |
|---|---|---|---|
| 2023 | 100 | 100 | Mature branded and generic market |
| 2024 | 92-96 | 96-99 | Continued generic conversion |
| 2025 | 85-91 | 93-97 | Payer pressure and Trelegy migration |
| 2026 | 78-86 | 90-95 | Greater use of low-cost substitutes |
| 2027 | 71-81 | 87-93 | Declining branded share |
| 2028 | 64-76 | 84-91 | Stable legacy demand |
| 2029 | 58-71 | 81-89 | Generic price erosion |
| 2030 | 52-67 | 78-87 | Residual maintenance therapy |
Under the base case, branded Advair revenue would fall by approximately 33% to 48% from 2023 levels by 2030. The direct molecule market would decline less sharply, by approximately 13% to 22%, because generic products maintain patient access.
Bull-case scenario
A bull case would require stronger persistence in the established Advair population, slower switching to triple therapy, and stable reimbursement for the Diskus platform. Under that scenario, branded revenue could decline by roughly 5% to 7% annually.
The bull case is more plausible in markets where:
- Advair has a strong formulary position.
- Generic penetration remains limited.
- Physicians continue prescribing the Diskus device.
- Patients are stable on dual therapy and do not require escalation.
Bear-case scenario
The bear case includes aggressive generic substitution, further price concessions, and rapid migration from inhaled corticosteroid/long-acting beta agonist therapy to triple therapy in COPD. Branded revenue could decline by 12% to 18% annually in this scenario.
The bear case is more likely where payers impose automatic substitution or where GSK prioritizes newer respiratory products over Advair commercial support.
When did Advair Diskus lose market exclusivity?
Advair’s core U.S. composition and product protection expired before the current generic market developed. The primary commercial exclusivity period ended in the 2010s, but actual substitutable generic entry was delayed by the technical complexity of demonstrating equivalence for a combination dry-powder inhaler.
The key distinction is between legal patent expiry and practical generic entry:
| Event | Approximate timing | Commercial effect |
|---|---|---|
| U.S. Advair approval | 2000 | Originator launch |
| Core patent and regulatory protection begin to expire | 2010s | Generic development becomes viable |
| U.S. substitutable generic entry | 2019 | Direct price competition begins |
| Broader payer conversion | 2020 onward | Branded share declines |
| Mature generic market | 2024 onward | Volume persists but revenue falls |
Inhaled products often have a longer effective commercial tail than conventional oral medicines because manufacturers must demonstrate equivalence for the active ingredients, dose delivery, particle characteristics, and device performance.
What patents protect Advair Diskus?
The historical Advair estate included patents covering the fluticasone propionate/salmeterol combination, inhaled pharmaceutical compositions, dosage formulations, and inhaler or dry-powder delivery technologies. The relevant protection was spread across product, formulation, and device claims rather than a single patent.
The central U.S. commercial protections have expired or no longer prevent approved substitutable products from entering the market. The remaining patent position is therefore more relevant to specific device designs, manufacturing processes, or jurisdictions than to blocking generic fluticasone/salmeterol sales in the United States.
Formulation and device protection
Advair’s commercial complexity has historically supported protection around:
- Particle-size distribution.
- Micronized fluticasone propionate.
- Salmeterol xinafoate formulation.
- Lactose carrier systems.
- Powder blending and dose uniformity.
- Multi-dose inhaler construction.
- Dose-counter and airflow mechanisms.
These features can create technical barriers even after the principal drug patents expire. They do not necessarily create a durable blocking position if a competitor uses a different inhaler or independently demonstrates pharmaceutical equivalence.
Geographic coverage
Patent outcomes differ by country. U.S. generic entry began later than patent expiry because of regulatory and technical barriers. European markets have also experienced generic or follow-on competition, but timing and substitution rates differ by national reimbursement systems.
GSK’s remaining commercial protection is strongest where:
- Device-specific patents remain enforceable.
- Generic substitution is limited by local law.
- Reimbursement favors the originator.
- Regulatory requirements for inhaled combinations are demanding.
The weakest protection is in price-sensitive markets with automatic substitution and multiple low-cost suppliers.
What is the Orange Book status of Advair Diskus?
Advair Diskus has been listed in the FDA Orange Book, which identifies approved drug products and relevant patent and exclusivity information. The commercial significance of the listing has diminished because the principal barriers to generic entry have already been overcome.
Wixela Inhub obtained an FDA therapeutic-equivalence rating to Advair Diskus. That rating enabled pharmacy-level substitution where state law and payer policy permit it. The existence of an approved substitutable product is more important to current market economics than the historical patent listings themselves.
The current commercial assessment is:
| Orange Book issue | Assessment |
|---|---|
| Reference listed drug | Advair Diskus |
| Generic pathway | ANDA |
| First major substitutable U.S. product | Wixela Inhub |
| Patent litigation risk | Lower than during pre-generic period |
| Generic substitution risk | High |
| New branded product risk | Moderate to high |
| Regulatory barrier | Device and equivalence complexity remains relevant |
Which companies are challenging Advair Diskus?
The principal competitive pressure comes from manufacturers of generic or follow-on inhaled products and from branded respiratory companies with newer therapies.
| Company | Product or strategy | Competitive impact |
|---|---|---|
| Viatris and Kindeva | Wixela Inhub | Direct substitutable competition |
| GSK | Advair, Breo, Trelegy | Originator defense and lifecycle management |
| AstraZeneca | Symbicort and other respiratory products | Dual-therapy competition |
| Boehringer Ingelheim | Spiriva and combination products | COPD substitution |
| AstraZeneca | Breztri and related therapies | Triple-therapy competition |
| Innoviva and partners | Long-acting respiratory products | Alternative maintenance therapy |
| Regional generic manufacturers | Fluticasone/salmeterol products | Price erosion outside the U.S. |
The strongest competitive threat is no longer a single Paragraph IV challenger. It is a combined effect from generic substitution and therapeutic migration.
What Paragraph IV challenges affected Advair Diskus?
Advair-related generic entry involved the standard abbreviated new drug application framework, including patent certifications under Hatch-Waxman. A Paragraph IV certification asserts that a listed patent is invalid, unenforceable, or not infringed.
The major commercial outcome was not a prolonged market-blocking settlement but the eventual approval and launch of a substitutable fluticasone/salmeterol product. The launch demonstrates that GSK’s remaining patent and regulatory barriers did not prevent U.S. competition.
For current investment analysis, the relevant question is not whether another Paragraph IV case will delay the first generic. The relevant questions are:
- How many additional suppliers will enter?
- Will they receive therapeutic-equivalence ratings?
- How quickly will payers mandate substitution?
- Will device differences limit pharmacy substitution?
- How much price erosion will follow multiple entrants?
How strong is the Advair patent estate?
The Advair patent estate is weak as a barrier to U.S. generic entry but retains moderate technical value in manufacturing and device-related know-how.
| Dimension | Strength | Rationale |
|---|---|---|
| Core composition protection | Low | Principal commercial protection has expired |
| Formulation protection | Low to moderate | Some technical claims may remain relevant by jurisdiction |
| Device protection | Moderate | Device design and manufacturing can be differentiated |
| Regulatory complexity | Moderate | Inhaled combination equivalence is technically demanding |
| U.S. blocking power | Low | Substitutable generic products are approved |
| International protection | Variable | Depends on country-specific patent and substitution rules |
| Manufacturing know-how | Moderate | Powder blending and dose uniformity remain difficult |
Advair’s remaining moat is operational rather than primarily legal. Scale, regulatory experience, supply reliability, and payer contracting matter more than the expired core patent position.
What manufacturing barriers affect Advair competitors?
Dry-powder inhalers require control of particle engineering, powder blending, moisture exposure, dose consistency, and device resistance. A competitor must demonstrate that the product delivers the intended dose throughout the labeled life of the inhaler.
The principal manufacturing barriers are:
- Consistent micronization of both active ingredients.
- Uniform distribution across individual doses.
- Stable interaction between active particles and lactose carrier.
- Device performance across inhalation-flow ranges.
- Protection from humidity.
- Consistent delivered-dose testing.
- Reliable high-volume inhaler assembly.
These barriers raise development cost and can delay entry. They do not preserve originator pricing indefinitely once multiple approved competitors achieve commercial scale.
How does Advair compare with Trelegy, Breo, and Symbicort?
| Product | Ingredients | Dosing profile | Commercial position |
|---|---|---|---|
| Advair Diskus | Fluticasone propionate/salmeterol | Typically twice daily | Mature dual therapy |
| Breo Ellipta | Fluticasone furoate/vilanterol | Once daily | Newer dual therapy |
| Symbicort | Budesonide/formoterol | Typically twice daily | Major dual-therapy competitor |
| Trelegy Ellipta | Fluticasone furoate/umeclidinium/vilanterol | Once daily | High-growth triple therapy |
| Breztri Aerosphere | Budesonide/glycopyrrolate/formoterol | Typically twice daily | COPD triple therapy |
Trelegy is the most important GSK product in the Advair migration pathway. It offers once-daily dosing and triple therapy, although it is not a direct generic substitute for Advair. The commercial transition from Advair to Trelegy allows GSK to retain some patients within its respiratory franchise while accepting lower Advair revenue.
Advair remains relevant for patients controlled on dual therapy, patients who do not require a long-acting muscarinic antagonist, and payers seeking lower-cost maintenance treatment.
What revenue exposure does Advair create for GSK?
Advair is no longer the central growth engine of GSK’s respiratory franchise. The company’s respiratory revenue has shifted toward Trelegy and other newer products. Advair still creates exposure in four areas:
- Branded revenue erosion.
- Lower net price from rebates and generic competition.
- Cannibalization by GSK’s own newer inhalers.
- Manufacturing and supply obligations for a mature product.
GSK can reduce the strategic impact of Advair’s decline by migrating patients to Trelegy, defending selected formularies, and preserving production scale. That strategy limits total franchise disruption but does not restore Advair’s historical revenue.
What generic launch scenarios exist for Advair Diskus?
The U.S. market has already passed the first-generic stage. Future scenarios depend on additional suppliers, payer behavior, and device differentiation.
Scenario 1: Limited generic expansion
One or two major suppliers retain meaningful share. Branded Advair remains available through selected formularies, and price erosion is gradual. This scenario supports a slower decline in originator revenue.
Scenario 2: Broad generic conversion
Multiple suppliers obtain approvals or expand distribution. Payers place generic products on preferred tiers, and pharmacy substitution increases. Branded revenue declines rapidly, while total molecule volume remains relatively stable.
Scenario 3: Therapeutic displacement
Patients move from dual therapy to Trelegy, Breztri, or other triple therapies. In this scenario, both branded Advair and the direct fluticasone/salmeterol market contract.
The most likely outcome is a combination of the second and third scenarios.
What litigation and settlement risks affect Advair?
The principal U.S. litigation risk has shifted from pre-launch patent disputes to commercial disputes involving:
- Infringement claims over inhaler architecture.
- Trade dress and device-copying allegations.
- ANDA approval timing.
- Manufacturing and supply contracts.
- Product liability and inhaler performance.
- Pricing and rebate practices.
Because substitutable products are already on the market, a new patent case would have limited ability to restore Advair’s historical exclusivity. Litigation could still affect a particular generic supplier or device configuration.
Publicly visible settlement activity is less important to current valuation than actual market-share movement and payer contracting. Early-entry settlements would have mattered before the 2019 generic launch; they have less relevance to the mature market.
What is the FDA regulatory status of Advair Diskus?
Advair Diskus remains an FDA-approved prescription inhaler for its labeled asthma and COPD uses. Its regulatory status is stable, but the commercial environment is mature.
FDA considerations include:
- Continued compliance with manufacturing standards.
- Device performance and dose delivery.
- Product labeling.
- Pharmacovigilance.
- Generic therapeutic equivalence.
- Combination-product manufacturing controls.
The FDA approval of Wixela Inhub reduced the regulatory uncertainty surrounding substitutable fluticasone/salmeterol products. Future regulatory developments are more likely to affect individual competitors than the basic viability of Advair Diskus.
Key Takeaways
- Advair Diskus is a mature GSK respiratory product with declining branded revenue.
- The first major substitutable U.S. generic, Wixela Inhub, launched in 2019.
- Core U.S. exclusivity no longer provides a meaningful barrier to generic competition.
- The direct fluticasone/salmeterol market should decline more slowly than branded Advair because low-cost products preserve volume.
- Branded Advair revenue could fall by roughly 33% to 48% from 2023 levels by 2030 under a base-case model.
- Trelegy is the most important GSK product benefiting from Advair patient migration.
- Remaining competitive advantages are based on manufacturing, device familiarity, supply reliability, and payer access rather than core patent exclusivity.
- The main commercial risks are generic conversion, price erosion, and therapeutic substitution by once-daily triple therapy.
- The principal investment question is the pace of franchise migration from Advair to Trelegy, not the recovery of Advair itself.
Frequently Asked Questions
Is Advair Diskus still commercially important?
Yes. Advair remains important as a high-volume maintenance inhaler, but its revenue contribution is declining because generic products and newer therapies have reduced branded demand.
Is Wixela Inhub the same as Advair Diskus?
Wixela Inhub contains the same active ingredients and has FDA therapeutic-equivalence status to Advair Diskus. It uses a different inhaler device, so patient training and device preference remain relevant.
Can a new generic company still enter the Advair market?
Yes, subject to FDA approval, manufacturing capacity, regulatory requirements, and commercial access. The economic opportunity is smaller than during the first-generic period because existing suppliers and payer discounts have already reduced prices.
Does Trelegy replace Advair for all patients?
No. Trelegy adds a long-acting muscarinic antagonist and is not appropriate or necessary for every patient using dual therapy. It is particularly important in COPD treatment escalation and in patients requiring triple therapy.
What is the main long-term value of the Advair franchise?
The remaining value lies in residual branded demand, generic or authorized-generic economics, manufacturing scale, and the ability to transition established patients to GSK’s newer respiratory products.
References
-
AstraZeneca. (2024). Annual report and form 20-F 2023. AstraZeneca PLC.
-
GSK. (2016). Annual report 2015. GlaxoSmithKline plc.
-
GSK. (2020). Annual report 2019. GlaxoSmithKline plc.
-
GSK. (2024). Annual report 2023. GSK plc.
-
U.S. Food and Drug Administration. (2019). FDA approves first generic of Advair Diskus. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. U.S. Department of Health and Human Services.
More… ↓
