Share This Page
Drug Sales Trends for ADIPEX-P
✉ Email this page to a colleague
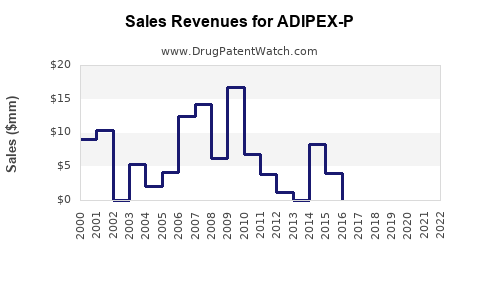
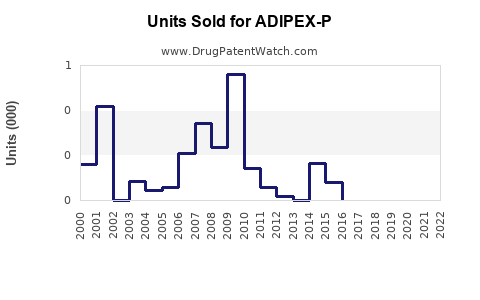
Annual Sales Revenues and Units Sold for ADIPEX-P
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ADIPEX-P | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ADIPEX-P | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ADIPEX-P | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Executive summary
Adipex-P is a mature, low-cost brand of phentermine hydrochloride, a Schedule IV sympathomimetic approved for short-term obesity treatment. Its commercial market is driven by prescriptions for phentermine products, but generic substitution limits the brand’s pricing power and revenue potential. Adipex-P has no meaningful remaining innovator exclusivity, no durable patent moat, and faces competition from generic phentermine, phentermine/topiramate, GLP-1 therapies, and newer obesity drugs.
A reasonable U.S. base-case estimate is that the total phentermine market will remain broadly stable through 2028, with annual prescription volume near 9 million to 12 million prescriptions. Adipex-P brand sales are likely to remain a small portion of that market. Under modeled assumptions, U.S. Adipex-P net sales could range from approximately $10 million to $30 million annually, with downside risk if generic substitution increases or prescribers shift toward GLP-1 products.
Adipex-P Market Analysis, Patent Status, Competition, and Sales Projections
Adipex-P is a branded phentermine product with limited growth potential and high exposure to generic substitution. The product’s commercial value is linked to phentermine demand rather than proprietary intellectual property.
| Metric | Assessment |
|---|---|
| Active ingredient | Phentermine hydrochloride |
| Dosage forms | 37.5 mg tablets and capsules; lower-strength tablets also marketed |
| FDA status | Approved prescription drug |
| Therapeutic category | Sympathomimetic anorectic |
| Controlled-substance status | Schedule IV |
| Primary indication | Short-term adjunct to caloric restriction and exercise for obesity |
| Patent position | No meaningful remaining exclusivity identified |
| Market structure | Generic-dominated |
| Main U.S. competitors | Generic phentermine, Lomaira, Qsymia, Wegovy, Zepbound, Saxenda |
| Main commercial risk | Generic substitution and migration to newer anti-obesity medicines |
What is Adipex-P and how is it used?
Adipex-P contains phentermine hydrochloride, a sympathomimetic amine with pharmacologic activity similar to the prototype anorectic agents. The FDA-approved labeling limits use to short-term treatment, generally interpreted as a few weeks, in patients with an initial body mass index of at least 30 kg/m² or at least 27 kg/m² with risk factors such as hypertension, diabetes, or hyperlipidemia.[1]
The most commonly prescribed strength is 37.5 mg. Physicians also use lower-dose phentermine products, particularly when attempting to reduce adverse effects or tailor dosing.
Adipex-P is not approved as a chronic obesity therapy in the same manner as semaglutide or tirzepatide. Its low cost, broad clinician familiarity, oral administration, and availability through cash-pay channels support continued use despite its older label and narrower indication.
How large is the U.S. phentermine market?
Phentermine remains one of the largest prescription obesity-drug markets by prescription volume, although its revenue per prescription is low.
Public prescription datasets have historically placed phentermine among the most frequently dispensed anti-obesity drugs in the United States. Depending on the reporting source, market year, and whether all generic strengths and branded products are included, annual U.S. volume is reasonably modeled at approximately 9 million to 12 million prescriptions.[2]
The market has two distinct segments:
- A high-volume, low-price generic segment.
- A smaller branded and cash-pay segment, including Adipex-P and Lomaira.
The market’s prescription volume does not translate directly into manufacturer revenue. Generic phentermine is widely available at low prices, and many patients pay cash because obesity medicines often have limited commercial insurance coverage. Retail cash prices can vary substantially by pharmacy, strength, quantity, and discount program.
Estimated U.S. phentermine market structure
| Segment | Estimated share of prescriptions | Commercial characteristics |
|---|---|---|
| Generic phentermine | 90% to 97% | Low price, broad availability, high substitution |
| Adipex-P | 1% to 5% | Brand recognition, limited pricing power |
| Lomaira and other branded presentations | 1% to 4% | Low-dose positioning and niche prescribing |
| Other phentermine-containing products | Less than 1% | Limited commercial contribution |
These percentages are analytical estimates rather than reported manufacturer market shares. Adipex-P sales are not publicly disclosed as a standalone product line.
What patents protect Adipex-P?
Adipex-P does not appear to have an active patent estate capable of protecting its core commercial market.
Phentermine hydrochloride has been marketed for decades. Any foundational composition, formulation, or use patents associated with the original product have expired. The active ingredient is available from multiple generic manufacturers, and FDA-approved generic products compete directly with Adipex-P.
The key commercial protections are therefore non-patent factors:
- Brand recognition.
- Physician familiarity.
- Availability in common dosage strengths.
- Pharmacy distribution.
- Manufacturer supply reliability.
- Patient preference for a branded product.
- Cash-pay marketing and prescribing channels.
Orange Book status and regulatory exclusivity
| Protection category | Adipex-P assessment |
|---|---|
| Active ingredient patent | No meaningful active protection identified |
| Formulation patent | No material current protection identified |
| Method-of-use patent | No material current protection identified |
| New chemical entity exclusivity | Expired |
| Orphan-drug exclusivity | Not applicable |
| Pediatric exclusivity | No current protection identified |
| Regulatory exclusivity | No current exclusivity identified |
| Orange Book commercial effect | Generic competition remains permitted |
FDA Orange Book protection is most relevant when listed patents block or delay abbreviated new drug applications. Adipex-P’s market position does not depend on an active Orange Book patent barrier.[3]
When does Adipex-P lose exclusivity?
Adipex-P has already lost meaningful market exclusivity.
The product’s competitive position is consistent with a mature off-patent medicine. Generic phentermine products are approved under the abbreviated new drug application pathway and can compete based on bioequivalence rather than repeating the full clinical development program required for a new chemical entity.
There is no credible basis for projecting a future patent cliff for Adipex-P because the principal loss of exclusivity occurred many years ago. The relevant business issue is not when exclusivity ends, but how quickly generic substitution and newer obesity therapies reduce branded demand.
Which companies compete with Adipex-P?
Generic phentermine manufacturers
Generic phentermine is manufactured or distributed by numerous U.S. companies. The market includes manufacturers such as Hikma Pharmaceuticals, Amneal Pharmaceuticals, Elite Pharmaceuticals, KVK-Tech, Lannett, Zydus, and other FDA-approved suppliers, subject to product availability and changes in ownership or distribution arrangements.
Generic competition is the primary threat because products are therapeutically substitutable and usually priced below the brand.
Branded phentermine products
Lomaira is a lower-dose phentermine product marketed for obesity treatment. It competes through dose flexibility and positioning rather than a fundamentally different mechanism.
Phentermine/topiramate
Qsymia combines phentermine with extended-release topiramate. It is approved for chronic weight management and has a broader label than Adipex-P. Qsymia has faced generic and patent-related competitive pressure, but its combination formulation and chronic-use positioning distinguish it from immediate-release phentermine.
GLP-1 and dual incretin therapies
The largest strategic threat comes from chronic therapies with greater average weight loss and broader commercial attention:
| Product | Active ingredient | Manufacturer | Relevance to Adipex-P |
|---|---|---|---|
| Wegovy | Semaglutide | Novo Nordisk | High efficacy, injectable, chronic treatment |
| Zepbound | Tirzepatide | Eli Lilly | High efficacy, injectable, chronic treatment |
| Saxenda | Liraglutide | Novo Nordisk | Established GLP-1 obesity product |
| Contrave | Naltrexone/bupropion | Currax | Oral alternative with chronic-use labeling |
| Qsymia | Phentermine/topiramate | Vivus, now associated with Corium commercialization | Direct pharmacologic adjacency |
Wegovy and Zepbound have higher acquisition costs, more complex access requirements, and injection-related barriers. Adipex-P retains a cost advantage, especially for uninsured patients and patients seeking short-term pharmacologic assistance.
What is the FDA regulatory status of Adipex-P?
Adipex-P is FDA-approved as a short-term adjunct to lifestyle intervention for exogenous obesity.[1] Its labeling includes contraindications for patients with a history of cardiovascular disease, uncontrolled hypertension, hyperthyroidism, glaucoma, agitated states, or a history of drug abuse, among other restrictions.
Phentermine is a Schedule IV controlled substance under the federal Controlled Substances Act. State prescribing rules may impose additional requirements, including limits on duration, refill procedures, telehealth prescribing, and monitoring.
The regulatory profile creates both support and constraint:
- The long clinical history supports physician familiarity.
- The controlled-substance classification restricts distribution and prescribing.
- The short-term label limits direct positioning against chronic obesity therapies.
- Safety concerns can reduce use in patients with cardiovascular or psychiatric risk.
- No new FDA exclusivity is available for the existing product.
What are the main formulation and manufacturing barriers?
Adipex-P has low manufacturing complexity compared with injectable biologics and modified-release obesity products. Phentermine hydrochloride is a small-molecule active ingredient that can be formulated into conventional tablets and capsules.
Manufacturing barriers are therefore operational rather than technological:
- Controlled-substance handling and recordkeeping.
- Active pharmaceutical ingredient supply.
- FDA quality-system compliance.
- Consistent tablet dissolution and content uniformity.
- Packaging and distribution controls.
- Product availability during generic supply disruptions.
There is no comparable manufacturing barrier to the aseptic production, device assembly, and cold-chain distribution required for GLP-1 injectables. That cost advantage supports continued supply of low-priced phentermine, but it also makes entry by additional generic manufacturers easier.
What patent litigation or Paragraph IV risk affects Adipex-P?
Adipex-P has limited current Paragraph IV litigation exposure because its core product is already off patent.
Paragraph IV litigation generally arises when a generic applicant challenges an unexpired Orange Book patent. Since Adipex-P’s principal market protections have expired, future litigation is more likely to involve:
- A newer phentermine formulation.
- A combination product.
- A delivery system.
- A manufacturing process.
- A competing branded product with separate patent claims.
Generic phentermine applicants do not need to overcome a meaningful Adipex-P patent barrier. There is no central, commercially important patent settlement controlling generic entry into the basic phentermine market.
How strong is the Adipex-P patent estate?
| Patent-estate factor | Rating | Analysis |
|---|---|---|
| Core compound protection | Very weak | Historical patents expired |
| Formulation protection | Very weak | Conventional dosage forms are widely available |
| Method-of-use protection | Weak | Existing label is mature and generic competition is established |
| Manufacturing protection | Weak | Multiple suppliers can manufacture the product |
| Regulatory exclusivity | None identified | No current exclusivity barrier |
| Brand protection | Moderate | Trademark and recognition provide limited differentiation |
| Overall patent strength | Very weak | Commercial value depends on brand and distribution |
Adipex-P may retain trademark value, but trademark protection does not prevent approval or sale of generic phentermine. It can prevent confusingly similar branding, not therapeutic substitution.
What are Adipex-P sales projections through 2028?
Because Adipex-P sales are not separately reported, projections require a market-share and net-price model. The following base case assumes:
- U.S. phentermine prescriptions remain near 10 million annually.
- Adipex-P captures 2% to 3% of branded and generic-equivalent prescription volume.
- Realized manufacturer net sales per prescription remain approximately $5 to $12 after discounts, rebates, wholesaler deductions, and channel effects.
- GLP-1 migration gradually reduces total phentermine volume.
- No material supply interruption occurs.
U.S. Adipex-P sales projection
| Year | Total phentermine prescriptions | Estimated Adipex-P share | Estimated Adipex-P prescriptions | Estimated net sales |
|---|---|---|---|---|
| 2024 | 9.5M to 11.5M | 2.0% to 3.0% | 190K to 345K | $1M to $4M |
| 2025 | 9.3M to 11.3M | 2.0% to 3.0% | 186K to 339K | $1M to $4M |
| 2026 | 9.0M to 11.0M | 1.8% to 2.8% | 162K to 308K | $1M to $4M |
| 2027 | 8.7M to 10.8M | 1.7% to 2.7% | 148K to 292K | $1M to $4M |
| 2028 | 8.4M to 10.5M | 1.5% to 2.5% | 126K to 263K | $1M to $3M |
These figures represent estimated manufacturer net sales, not retail sales. If Adipex-P is sold through a higher-priced cash-pay channel or has a materially higher brand share than modeled, annual sales could exceed the base range.
Scenario analysis
| Scenario | 2028 phentermine volume | Adipex-P share | 2028 estimated net sales | Primary driver |
|---|---|---|---|---|
| Downside | 7.5M to 9.0M | 1.0% to 1.5% | $0.5M to $2M | Rapid GLP-1 migration and generic substitution |
| Base case | 8.4M to 10.5M | 1.5% to 2.5% | $1M to $3M | Stable low-cost use with gradual erosion |
| Upside | 10.5M to 12.0M | 3.0% to 4.0% | $4M to $10M | Cash-pay brand preference and GLP-1 access barriers |
A higher retail sales estimate is possible if sales are measured at pharmacy checkout rather than manufacturer net revenue. The difference can be substantial because cash prices, discount cards, wholesaler margins, and pharmacy margins are not equivalent to branded product revenue.
What generic entry risks exist for Adipex-P?
The generic-entry risk is effectively realized rather than prospective. Generic phentermine is already established. Future downside is more likely to come from share erosion than a discrete launch event.
Key risks include:
- Pharmacies automatically substituting generic phentermine.
- Manufacturers reducing Adipex-P promotional support.
- Patients choosing lower-cost generic products.
- Telehealth providers prescribing generic phentermine.
- Payers excluding branded phentermine.
- Broader adoption of semaglutide and tirzepatide.
- Increased scrutiny of long-term or repeated phentermine use.
- Supply disruptions that shift patients toward competing products.
Adipex-P’s main defense is price relative to newer therapies, but generic phentermine has the same price advantage without the brand premium.
How does Adipex-P compare with Wegovy, Zepbound, and Qsymia?
| Attribute | Adipex-P | Qsymia | Wegovy | Zepbound |
|---|---|---|---|---|
| Route | Oral | Oral | Injection | Injection |
| Typical use | Short term | Chronic | Chronic | Chronic |
| Active ingredient class | Sympathomimetic | Combination | GLP-1 agonist | GIP/GLP-1 agonist |
| Relative cost | Low | Moderate to high | High | High |
| Weight-loss efficacy | Lower | Moderate | High | High |
| Generic competition | Extensive | Emerging or developing | No conventional generic equivalent currently | No conventional generic equivalent currently |
| Main access advantage | Cash affordability | Chronic oral option | Strong clinical efficacy | Strong clinical efficacy |
| Main commercial weakness | Short-term label and safety limits | Cost and tolerability | Cost and access | Cost and access |
Adipex-P is most competitive where patients lack insurance coverage, cannot obtain GLP-1 medicines, or prefer an oral low-cost option. It is less competitive in chronic obesity-management programs that prioritize durable weight reduction and long-term treatment.
What licensing deals affect Adipex-P?
No major recent licensing transaction appears to define Adipex-P’s current commercial outlook. The product is a mature branded medicine rather than a platform asset with meaningful partnering value.
Potential transaction value would likely relate to:
- A portfolio acquisition involving multiple generic and branded products.
- Distribution rights in a specific market.
- A controlled-substance commercial platform.
- Manufacturing or supply arrangements.
- A broader obesity-treatment portfolio.
A standalone Adipex-P licensing deal would likely have limited strategic value unless the buyer controls a differentiated distribution channel or combines the product with digital weight-management services.
Key Takeaways
- Adipex-P is a mature branded phentermine product with no meaningful remaining patent moat.
- Generic phentermine controls most prescription volume and limits brand pricing power.
- The total U.S. phentermine market can reasonably remain near 9 million to 12 million prescriptions annually in the near term, with gradual erosion from GLP-1 therapies.
- Estimated Adipex-P manufacturer net sales are likely in the low-single-digit millions annually under a base-case model.
- The product’s main commercial advantages are low cost, oral dosing, physician familiarity, and availability.
- Its main risks are generic substitution, the short-term FDA label, controlled-substance restrictions, and migration to Wegovy and Zepbound.
- Paragraph IV litigation and patent-settlement risk are limited because the core product is already off patent.
- The principal investment question is distribution economics, not intellectual property protection.
FAQs
Is Adipex-P still under patent protection?
No meaningful active patent protection is expected to prevent generic phentermine competition. The product’s core compound and conventional dosage-form protections expired long ago.
Is Adipex-P included in the FDA Orange Book?
Adipex-P is an FDA-approved prescription product, but its commercial position does not depend on an active Orange Book patent listing that blocks generic phentermine.
Can generic phentermine replace Adipex-P?
Yes. FDA-approved generic phentermine products are intended to be therapeutically equivalent to the corresponding branded dosage forms, subject to product-specific strength, formulation, and substitution rules.
Will Wegovy and Zepbound eliminate the Adipex-P market?
No. They are likely to reduce long-term growth and take share from some patients, but Adipex-P retains a cost and access advantage for uninsured or cash-pay patients.
What is the most likely Adipex-P revenue trend through 2028?
The most likely trend is flat to declining revenue, with a base-case U.S. manufacturer net-sales range of approximately $1 million to $3 million annually by 2028. Retail sales may be higher depending on channel margins and cash-pay pricing.
References
- U.S. Food and Drug Administration. (n.d.). Adipex-P (phentermine hydrochloride) prescribing information. FDA.
- ClinCalc. (n.d.). The top 200 drugs of 2023. ClinCalc DrugStats.
- U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
- U.S. Drug Enforcement Administration. (n.d.). Drug scheduling. U.S. Department of Justice.
- U.S. Food and Drug Administration. (n.d.). Wegovy (semaglutide) prescribing information. FDA.
- U.S. Food and Drug Administration. (n.d.). Zepbound (tirzepatide) prescribing information. FDA.
More… ↓
