Share This Page
Drug Sales Trends for VESICARE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for VESICARE (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
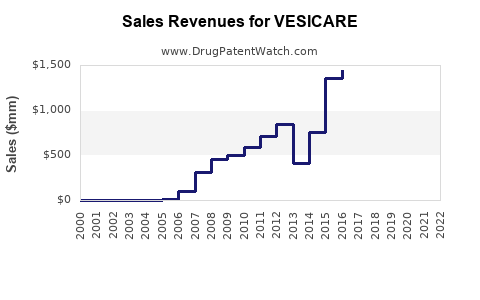
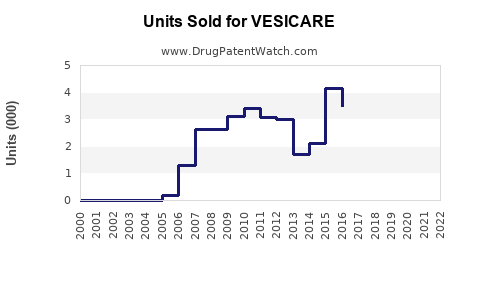
Annual Sales Revenues and Units Sold for VESICARE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| VESICARE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| VESICARE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| VESICARE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| VESICARE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| VESICARE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| VESICARE | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| VESICARE | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
VESICARE Market Analysis, Sales Projections, Patent Expiration, and Generic Competition
VESICARE, the branded formulation of solifenacin succinate, has moved from a high-value branded overactive bladder therapy to a mature generic market. Astellas retains the brand, but U.S. revenue exposure is limited because core composition and regulatory exclusivity protections have expired or no longer prevent generic substitution. Future commercial value is concentrated in VESICARE LS oral suspension, residual branded prescriptions, international markets with slower generic penetration, and solifenacin combination or lifecycle products.
Under a base-case market model, global sales attributable to branded VESICARE are likely to remain below $100 million annually by 2026, while the broader solifenacin market, including generics, should remain a low-growth market with estimated global annual sales of approximately $500 million to $900 million through 2030. These figures are analyst estimates based on product maturity, generic availability, therapeutic substitution, and the size of the overactive bladder drug market.
What is VESICARE and how does it work?
VESICARE contains solifenacin succinate, an antimuscarinic drug used to treat overactive bladder symptoms, including urinary urgency, urinary frequency, and urge urinary incontinence.
| Product | Active ingredient | Dosage form | U.S. regulatory status |
|---|---|---|---|
| VESICARE | Solifenacin succinate | 5 mg and 10 mg tablets | FDA approved |
| VESICARE LS | Solifenacin succinate | Oral suspension, 1 mg/mL | FDA approved in 2020 |
| Generic solifenacin | Solifenacin succinate | Tablets and oral solution/suspension | FDA-approved generic competition |
Solifenacin selectively inhibits muscarinic receptors in the bladder. Its main commercial competitors include oxybutynin, tolterodine, darifenacin, trospium, fesoterodine, and the beta-3 adrenergic agonists Myrbetriq, Gemtesa, and vibegron products.
The market has shifted toward beta-3 agonists in some patients because of concerns about anticholinergic adverse effects, including dry mouth, constipation, cognitive effects, and urinary retention. Solifenacin remains commercially relevant because it is widely available, familiar to prescribers, and generally less expensive than branded alternatives.
How large is the VESICARE and solifenacin market?
The relevant market has three layers:
- Branded VESICARE tablets.
- VESICARE LS and other branded solifenacin formulations.
- Generic solifenacin products sold through retail, mail-order, institutional, and international channels.
The branded product has lost most of its U.S. economic value because generic tablets are available. The broader solifenacin molecule retains significant volume, particularly in price-sensitive markets.
Estimated global market structure
| Segment | Estimated 2024 annual sales | 2030 base-case estimate | Market direction |
|---|---|---|---|
| Branded VESICARE tablets | $30 million-$70 million | $10 million-$30 million | Declining |
| VESICARE LS and branded lifecycle products | $10 million-$30 million | $15 million-$40 million | Stable to modest growth |
| Generic solifenacin worldwide | $450 million-$750 million | $500 million-$850 million | Low growth |
| Total solifenacin market | $500 million-$850 million | $525 million-$920 million | Flat to modest growth |
These estimates exclude revenue from competing molecules such as mirabegron, vibegron, oxybutynin, and tolterodine. They also exclude products in which solifenacin is combined with another active ingredient unless the combination is separately reported.
Astellas does not generally report VESICARE as a standalone revenue line in its consolidated financial disclosures. This limits the precision of current brand-sales estimates. Astellas reports broader product categories and major products, while mature products such as VESICARE have substantially lower disclosure priority than newer products.
What are the VESICARE sales projections through 2030?
The base-case outlook is for continued erosion in branded VESICARE tablets and relatively stable molecule-level demand.
Base-case projection
| Year | Branded VESICARE sales | Total solifenacin market | Key market driver |
|---|---|---|---|
| 2024 | $40 million-$100 million | $500 million-$850 million | Generic substitution |
| 2025 | $30 million-$80 million | $510 million-$865 million | Continued price erosion |
| 2026 | $25 million-$65 million | $515 million-$880 million | Stable patient volume |
| 2027 | $20 million-$55 million | $520 million-$895 million | International generic uptake |
| 2028 | $15 million-$45 million | $520 million-$905 million | Mature demand |
| 2029 | $12 million-$38 million | $525 million-$915 million | Therapeutic substitution |
| 2030 | $10 million-$30 million | $525 million-$920 million | Branded niche retention |
The principal difference between branded VESICARE sales and the total solifenacin market is price. Generic products may preserve or expand prescription volume while reducing revenue per prescription.
Bull-case scenario
The bull case assumes stronger demand for oral suspension, slower generic substitution outside the United States, and continued use of solifenacin in older patients and in combination therapy. Under this scenario, total solifenacin sales could approach $1 billion globally by 2030, while branded VESICARE-related sales could remain near $75 million.
Bear-case scenario
The bear case assumes faster conversion to generics, increased prescribing of mirabegron and vibegron, and broader restrictions on anticholinergic use in older adults. Under this scenario, branded VESICARE sales could fall below $10 million by 2030, while the total solifenacin market could decline toward $400 million-$550 million.
When did VESICARE lose U.S. exclusivity?
VESICARE lost practical U.S. exclusivity when FDA-approved generic solifenacin products entered the market after expiration of the principal patent and associated regulatory protections.
The key commercial milestones are:
| Milestone | Date |
|---|---|
| U.S. approval of VESICARE tablets | 2004 |
| U.S. approval of VESICARE 5 mg and 10 mg tablets | 2004 |
| Generic solifenacin approvals and market entry | 2019-2020 period |
| U.S. approval of VESICARE LS | 2020 |
| Current status | Mature branded product with generic competition |
The original VESICARE tablet franchise is therefore no longer protected by meaningful market exclusivity in the United States. VESICARE LS has a different commercial profile because the oral suspension is a distinct dosage form and was approved later.
What patents protect VESICARE?
The principal U.S. patent associated with solifenacin is U.S. Patent No. 6,017,927, which covers solifenacin-related compounds and their pharmaceutical use. The patent was assigned to Yamanouchi Pharmaceutical, the predecessor organization associated with Astellas. The relevant composition protection has expired, allowing generic tablet competition.
Patent protection for later formulations and dosage forms must be assessed separately from the original compound patent.
Core patent estate
| Patent category | Commercial subject matter | Current risk profile |
|---|---|---|
| Compound patent | Solifenacin and related compounds | Expired |
| Pharmaceutical composition patents | Oral tablet formulations | Expired or commercially ineffective |
| Method-of-use patents | Treatment of overactive bladder | Limited value after generic entry |
| Oral suspension patents | VESICARE LS formulation and delivery | Potentially relevant |
| Manufacturing patents | Formulation, particle size, process controls | Depends on claim scope and enforceability |
The most important remaining intellectual-property question is whether formulation or use patents can prevent generic oral suspension substitution. Those rights generally do not restore the broad exclusivity once held by the tablet product.
What is the Orange Book status of VESICARE?
FDA Orange Book listings determine which patents a generic applicant must address in an abbreviated new drug application. The original VESICARE tablet listings no longer create a meaningful barrier to ordinary generic solifenacin tablets because the main patent protection has expired.
VESICARE LS may have separate listed patents because it is an oral suspension rather than a conventional tablet. A generic applicant may use a Paragraph IV certification to challenge listed patents or a Paragraph III certification to wait for patent expiration. The commercial effect depends on:
- Whether the patent is listed for the relevant dosage form.
- Whether the generic product has the same route and dosage form.
- Whether the applicant seeks approval for all indications.
- Whether Astellas or another patent holder files suit within the statutory period.
- Whether the patent claims cover the product itself or only a method of use.
Orange Book patents are not equivalent to guaranteed enforceable exclusivity. A listed patent can be challenged, designed around, or rendered commercially less relevant by a narrow product label.
Are there Paragraph IV challenges to VESICARE?
Generic solifenacin applicants could use Paragraph IV certifications against any unexpired listed patents covering VESICARE LS or specific formulation claims. The original tablet franchise has already passed the central Paragraph IV risk period because generic products are commercially available.
The key distinction is between:
- Paragraph IV activity against the mature tablet product, which has limited remaining economic significance.
- Paragraph IV activity against VESICARE LS, which could affect the timing of generic oral suspension entry.
- Patent litigation concerning labeling or method-of-use claims, which may not block approval of a product with a narrower label.
Publicly visible litigation activity surrounding VESICARE is materially less significant than the litigation associated with high-revenue products such as oncology drugs, biologics, or specialty immunology products. The principal competitive event is generic entry rather than a major pending patent dispute.
What formulation patents protect VESICARE LS?
VESICARE LS is an oral suspension designed for patients who have difficulty swallowing tablets. Its formulation may create additional patent and regulatory barriers because suspension products require control of stability, dose uniformity, particle dispersion, preservative systems, and administration characteristics.
A formulation patent can be commercially useful when it covers:
- A specific concentration of solifenacin.
- A stable aqueous suspension.
- Particle-size limitations.
- Excipients or preservative combinations.
- Storage or container-closure requirements.
- A method for administering the suspension to a defined patient group.
Formulation patents usually have a narrower scope than compound patents. Their value depends on whether a generic applicant can use a different excipient system, concentration, manufacturing process, or device while maintaining pharmaceutical equivalence.
Which companies compete with VESICARE?
VESICARE competes in a fragmented overactive bladder market.
| Product or class | Company examples | Competitive effect |
|---|---|---|
| Myrbetriq, mirabegron | Astellas | Major branded alternative |
| Gemtesa, vibegron | Urovant Sciences, Sumitomo Pharma | Beta-3 agonist growth competitor |
| Oxybutynin | Multiple generic manufacturers | Low-cost antimuscarinic substitute |
| Tolterodine | Viatris and other generic manufacturers | Mature generic substitute |
| Fesoterodine | Generic manufacturers and branded legacy products | Antimuscarinic competition |
| Trospium | Multiple generic manufacturers | Alternative antimuscarinic |
| Darifenacin | Generic manufacturers | Niche antimuscarinic option |
Astellas has exposure to both VESICARE and Myrbetriq, but the products face different lifecycle positions. VESICARE has a lower price and broader generic availability. Myrbetriq has retained greater branded value because it is a beta-3 agonist and entered the market later.
How does VESICARE compare with Myrbetriq and Gemtesa?
| Attribute | VESICARE | Myrbetriq | Gemtesa |
|---|---|---|---|
| Molecule | Solifenacin | Mirabegron | Vibegron |
| Class | Antimuscarinic | Beta-3 agonist | Beta-3 agonist |
| Generic competition | Established for tablets | Limited or developing by market | Limited |
| Price position | Low after generic entry | Premium branded | Premium branded |
| Main limitation | Anticholinergic adverse effects | Blood-pressure and cardiovascular considerations | Cost and access |
| Commercial lifecycle | Mature | Mature branded growth product | Newer branded competitor |
| Generic substitution risk | High | Lower in near term | Lower in near term |
VESICARE is more defensible on price than on patent protection. Beta-3 agonists are more defensible on branding and differentiation but face higher payer costs.
What generic entry risks exist for VESICARE?
The generic-entry risk is high for tablets and moderate for oral suspension.
Tablet risks
Generic solifenacin tablets are already established. Further price erosion is likely as additional manufacturers enter or expand distribution. Retail pharmacy substitution makes the brand vulnerable even where physicians continue to prescribe VESICARE by name.
Oral suspension risks
VESICARE LS may retain a longer period of commercial differentiation because oral suspension products require more complex formulation and regulatory work. The market is smaller than the tablet market, which can reduce generic incentive. The main risks are:
- A generic oral suspension with a therapeutically equivalent label.
- Pharmacy substitution or payer-directed switching.
- Compounded alternatives where permitted.
- Physicians switching patients to tablets when clinically appropriate.
- Use of alternative drugs with liquid or easier-to-administer formulations.
What is the FDA regulatory status of VESICARE?
VESICARE tablets are FDA-approved prescription drugs for overactive bladder. VESICARE LS was approved as an oral suspension for pediatric patients in the relevant approved indication. The products are regulated as small-molecule drugs, not biologics.
There is no biosimilar pathway for VESICARE. The competitive pathway is an abbreviated new drug application for generic solifenacin, not a 351(k) biosimilar application.
FDA regulatory value is therefore tied to:
- Therapeutic equivalence.
- Dosage-form approval.
- Product-specific labeling.
- Pediatric indications.
- Pharmaceutical equivalence and bioequivalence.
- Any remaining listed patent or regulatory exclusivity.
What licensing deals affect VESICARE?
VESICARE originated from Yamanouchi Pharmaceutical, which later combined with Fujisawa Pharmaceutical to form Astellas Pharma. Astellas is the principal commercial rights holder associated with the product in major markets.
No current licensing transaction is generally recognized as a major independent value driver for the mature VESICARE franchise. Commercial analysis should focus on Astellas' retained rights, regional commercialization arrangements, and generic manufacturers rather than on a large active licensing market.
How strong is the VESICARE patent estate?
The patent estate is weak for the original tablet product and stronger, but narrower, for later formulations.
| Patent-estate element | Assessment |
|---|---|
| Original compound protection | Expired |
| Tablet formulation protection | Low commercial strength |
| Method-of-use protection | Limited against approved generic labels |
| VESICARE LS formulation protection | Moderate, depending on active claims |
| Manufacturing protection | Potentially useful but design-around risk is high |
| Litigation leverage | Low for tablets; higher for specific suspension claims |
| Overall franchise protection | Weak to moderate |
The franchise has greater commercial durability through regulatory execution, physician familiarity, and distribution than through broad patent exclusivity.
What is the geographic market outlook for VESICARE?
The United States is the most advanced generic market for solifenacin. Europe and Japan also have substantial generic competition, although substitution rates, reimbursement policies, and brand loyalty differ by country.
Emerging markets may preserve higher branded volumes where:
- Generic penetration is fragmented.
- Physicians continue to prescribe established brands.
- Reimbursement systems do not mandate lowest-cost substitution.
- Local manufacturing and registration requirements slow market entry.
Japan remains strategically relevant because Astellas has deep domestic commercial infrastructure and a large aging population. European revenue is more exposed to tendering, reference pricing, and generic substitution.
What is the revenue exposure for Astellas?
VESICARE is unlikely to be a material driver of Astellas' consolidated revenue compared with newer specialty and oncology products. The product may still generate cash flow through mature-market prescriptions, licensing, international distribution, and VESICARE LS, but its strategic value is limited.
The principal financial risks are:
- Continued U.S. price compression.
- Loss of residual branded prescriptions.
- Substitution by beta-3 agonists.
- Generic oral suspension entry.
- Declining anticholinergic use in elderly patients.
- Payer restrictions on branded products.
The principal upside is limited to lifecycle retention, pediatric use, oral-suspension differentiation, and slower generic adoption in selected non-U.S. markets.
Key Takeaways
- VESICARE is a mature solifenacin product with established generic tablet competition.
- Branded VESICARE sales are likely below $100 million annually on a global basis.
- The broader solifenacin market could remain approximately $500 million-$900 million through 2030.
- U.S. tablet exclusivity has ended; generic substitution is the central commercial issue.
- VESICARE LS has more relevant formulation and dosage-form protection than the original tablets.
- No biosimilar risk exists because solifenacin is a small-molecule drug.
- Myrbetriq and Gemtesa represent the strongest branded therapeutic competitors.
- Astellas' residual value is concentrated in VESICARE LS, international sales, and mature-product cash flow.
- Generic oral suspension entry is the main remaining product-specific risk.
- The overall VESICARE patent estate is weak for tablets and moderate for selected formulations.
FAQs
Is VESICARE still patent protected?
The original compound and tablet protections no longer prevent generic solifenacin tablet competition. Later formulation patents may remain relevant for VESICARE LS.
Is solifenacin generic available in the United States?
Yes. Generic solifenacin tablets are available, and generic manufacturers have materially reduced the price and market share of branded VESICARE.
Does VESICARE have biosimilar competition?
No. VESICARE contains a small-molecule active ingredient, so competition proceeds through the FDA generic-drug pathway rather than the biosimilar pathway.
Will VESICARE sales increase after 2025?
A broad increase is unlikely. Branded tablet sales should continue to decline, while total solifenacin volume may remain stable because generic pricing supports continued use.
What could extend the commercial life of VESICARE?
The main opportunities are VESICARE LS, pediatric prescribing, international markets with slower substitution, and formulations that address adherence or swallowing limitations.
References
-
Astellas Pharma Inc. (2024). Annual report and financial results materials. Astellas Pharma Inc.
-
U.S. Food and Drug Administration. (2004). VESICARE prescribing information. FDA.
-
U.S. Food and Drug Administration. (2020). VESICARE LS prescribing information. FDA.
-
U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations, Orange Book. FDA.
-
U.S. Patent and Trademark Office. (2000). U.S. Patent No. 6,017,927: Quinuclidine compounds. USPTO.
-
American Urological Association. (2024). Diagnosis and treatment of overactive bladder, non-neurogenic lower urinary tract dysfunction in adults. AUA.
-
U.S. Food and Drug Administration. (2019-2020). Abbreviated new drug application approvals for solifenacin succinate. FDA.
More… ↓