Share This Page
Drug Sales Trends for ULORIC
✉ Email this page to a colleague
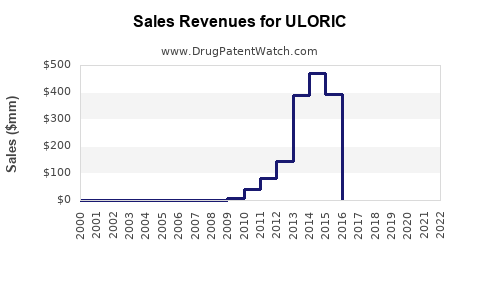
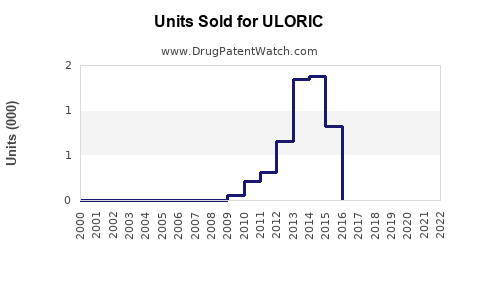
Annual Sales Revenues and Units Sold for ULORIC
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ULORIC | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ULORIC | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ULORIC | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ULORIC | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ULORIC | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ULORIC | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Uloric Market Analysis, Sales Forecast, Patent Position, and Generic Competition
Uloric, the brand name for febuxostat, is no longer a significant branded-revenue product in the United States. Generic febuxostat has replaced Uloric in most markets, while cardiovascular safety restrictions limit prescribing growth. The global febuxostat market remains commercially viable because of chronic gout treatment, rising hyperuricemia prevalence, and demand from patients who cannot tolerate or do not respond adequately to allopurinol.
The base-case forecast places global febuxostat sales at approximately $450 million to $650 million in 2025, rising to $550 million to $850 million by 2030. U.S. branded Uloric revenue is projected to remain immaterial, with most value accruing to generic manufacturers and regional branded suppliers.
What is Uloric and how is febuxostat used?
Uloric is an oral xanthine oxidase inhibitor containing febuxostat. It is used to lower serum uric acid in adults with gout and hyperuricemia. The drug received U.S. Food and Drug Administration approval in 2009 for chronic management of hyperuricemia associated with gout, generally at 40 mg or 80 mg once daily (FDA, 2009).
Febuxostat competes primarily with:
- Allopurinol, the standard first-line urate-lowering therapy.
- Probenecid and other uricosuric agents.
- Newer or regionally available urate-lowering treatments.
- Biologic or enzyme therapies for severe refractory disease, including pegloticase.
Febuxostat’s commercial position depends on its use in patients who fail, cannot tolerate, or have contraindications to allopurinol. It is not normally positioned as the default first-line therapy in the United States.
What is the current FDA regulatory status of Uloric?
The FDA requires a boxed warning for febuxostat because of an observed increase in cardiovascular death in the CARES trial. The FDA concluded that febuxostat should generally be reserved for patients who have inadequate response to allopurinol, cannot tolerate it, or are not appropriate candidates for it (FDA, 2019).
The current U.S. label includes:
| Regulatory element | Uloric/febuxostat status |
|---|---|
| Active ingredient | Febuxostat |
| Therapeutic class | Xanthine oxidase inhibitor |
| U.S. approval | 2009 |
| Main indication | Chronic hyperuricemia associated with gout |
| Typical strengths | 40 mg and 80 mg |
| Boxed warning | Cardiovascular death risk versus allopurinol |
| U.S. commercial status | Generic-dominated |
| First-line positioning | Generally restricted by safety and treatment guidelines |
| Main competitor | Allopurinol |
The FAST cardiovascular-outcomes study produced a more favorable result than CARES, finding no increased risk of death with febuxostat compared with allopurinol in the studied European population (Mackenzie et al., 2020). The FDA boxed warning remains in place, creating a continuing commercial constraint in the United States.
When did Uloric lose market exclusivity?
Uloric lost practical U.S. exclusivity after generic febuxostat approvals began in 2019. Generic competition substantially reduced the commercial value of the brand and shifted prescribing toward lower-cost products.
The relevant commercial timeline is:
| Period | Event | Market impact |
|---|---|---|
| 2009 | FDA approves Uloric | Launch of branded febuxostat in the United States |
| 2015-2018 | Brand growth and broader physician adoption | Increasing use in allopurinol-intolerant patients |
| 2018 | CARES safety findings become commercially important | Prescriber caution increases |
| 2019 | FDA adds boxed warning | Brand demand weakens |
| 2019 onward | Generic febuxostat enters the U.S. market | Uloric pricing power collapses |
| 2020 onward | Generic and regional branded products dominate | Uloric becomes a limited commercial asset |
The key commercial loss was not only patent expiry. The boxed warning arrived near the period of generic entry, reducing the brand’s ability to defend price and market share.
What are Uloric sales and historical revenue trends?
Takeda reported Uloric as a commercial product before generic erosion, but public reporting did not consistently disclose a standalone U.S. net-sales figure in the same detail as major Takeda products. Historical sales were materially higher before generic competition and the cardiovascular warning.
A practical revenue interpretation is:
- Pre-generic U.S. Uloric sales were likely in the hundreds of millions of dollars annually.
- Brand revenue declined sharply after generic febuxostat became available.
- Current U.S. Uloric revenue is expected to be negligible relative to the broader febuxostat market.
- Global febuxostat revenue remains meaningful because generic and local branded products continue to sell in Asia, Europe, Latin America, and other markets.
The principal economic shift was from a high-margin branded product to a volume-driven generic market. Manufacturer profitability now depends on supply efficiency, regulatory approvals, tender access, and geographic scale.
How large is the global febuxostat market?
The global market is driven by four factors:
- Growth in diagnosed gout and hyperuricemia.
- Increased use of chronic urate-lowering therapy.
- Patient switching from allopurinol because of intolerance, renal concerns, or inadequate urate control.
- Broader availability of generic febuxostat in emerging markets.
Allopurinol remains the dominant therapy by volume. Febuxostat is a secondary product with stronger positioning in selected patient segments. The largest commercial opportunities are likely in China, Japan, India, South Korea, Southeast Asia, and selected European markets.
A bottom-up estimate supports the following 2025 range:
| Market segment | Estimated 2025 sales |
|---|---|
| United States generic febuxostat | $50 million-$100 million |
| Europe | $100 million-$160 million |
| China and East Asia | $180 million-$280 million |
| India and other emerging markets | $100 million-$160 million |
| Global total | $450 million-$650 million |
These estimates represent febuxostat drug sales, not Uloric-branded sales. They include generic and regional branded products and exclude most allopurinol revenue.
What are the sales projections for Uloric and febuxostat?
Base-case forecast
| Year | Global febuxostat market | U.S. Uloric brand | U.S. total febuxostat |
|---|---|---|---|
| 2024 | $420 million-$600 million | Less than $10 million | $50 million-$90 million |
| 2025 | $450 million-$650 million | Less than $10 million | $55 million-$100 million |
| 2026 | $470 million-$680 million | Less than $10 million | $60 million-$105 million |
| 2027 | $490 million-$720 million | Less than $10 million | $65 million-$115 million |
| 2028 | $510 million-$760 million | Less than $10 million | $70 million-$125 million |
| 2029 | $530 million-$800 million | Less than $10 million | $75 million-$135 million |
| 2030 | $550 million-$850 million | Less than $10 million | $80 million-$145 million |
The base case implies global market growth of approximately 3% to 5% annually. Growth is expected to come mainly from patient volume, not price increases.
Upside case
The market could exceed $900 million by 2030 if:
- Physicians respond favorably to the FAST study.
- Cardiovascular concerns become less restrictive outside the United States.
- Diagnosis and treatment rates rise in China and India.
- Generic manufacturers expand access through public reimbursement and tender channels.
- Febuxostat gains share among chronic kidney disease patients who cannot use or tolerate allopurinol.
Downside case
The market could remain near $400 million to $550 million through 2030 if:
- Allopurinol retains overwhelming first-line dominance.
- Cardiovascular safety concerns continue to suppress adoption.
- Regulators or treatment guidelines further restrict use.
- Generic price erosion exceeds volume growth.
- New urate-lowering therapies improve access and replace febuxostat in high-risk patients.
What companies are competing in the febuxostat market?
Competition is fragmented because the U.S. market is generic and many countries have local branded versions.
Key participant groups include:
- Takeda, associated with the original Uloric brand.
- Large generic companies selling febuxostat tablets in the United States and Europe.
- Indian manufacturers with broad generic and export portfolios.
- Chinese pharmaceutical companies supplying domestic and regional markets.
- Japanese and European companies selling local branded or generic versions.
The competitive advantage is primarily commercial rather than technological. Manufacturers compete on:
- Regulatory approvals.
- Product availability.
- Hospital and pharmacy contracts.
- Tender pricing.
- Manufacturing cost.
- Bioequivalence data.
- Distribution in emerging markets.
What formulations and patents protect febuxostat?
The main commercial product is an immediate-release oral tablet, commonly available in 40 mg and 80 mg strengths. Formulation differentiation is limited compared with products that use injectables, extended-release delivery, or complex combination technologies.
The original Uloric estate included composition, formulation, and regulatory exclusivity protections. Those protections no longer provide a meaningful barrier to routine tablet competition in the United States. Remaining commercial opportunities are more likely to involve:
- Country-specific formulation patents.
- Manufacturing-process patents.
- Polymorph or crystalline-form claims.
- Combination products.
- Pediatric or renal-dosing extensions.
- New indications or differentiated dosing regimens.
The practical patent strength of the legacy Uloric estate is weak against ordinary generic tablet entry. Manufacturing know-how may still create cost advantages, but it is unlikely to prevent competition where generic regulatory pathways are available.
What generic entry risks affect Uloric?
Generic entry risk is already realized in the United States and other mature markets. The main remaining risks are erosion of any residual brand prescriptions, additional generic entrants, and price compression.
For generic manufacturers, the principal risks are different:
- FDA compliance and manufacturing observations.
- Supply interruptions.
- Low price ceilings after multiple approvals.
- Limited differentiation among tablet products.
- Reimbursement restrictions.
- Cardiovascular safety concerns that reduce total prescription volume.
A generic launch can gain volume quickly but still produce limited revenue if several suppliers enter the same market. The strongest commercial opportunity is in markets where local manufacturing, hospital procurement, or brand recognition restricts competition.
How does febuxostat compare with allopurinol?
| Factor | Febuxostat | Allopurinol |
|---|---|---|
| Market role | Alternative or second-line therapy | Standard first-line therapy |
| Main advantage | Effective urate lowering in selected patients | Low cost, long clinical history |
| Main limitation | Cardiovascular warning | Hypersensitivity and tolerability concerns |
| Generic competition | High | Very high |
| Commercial growth | Moderate, patient-segment driven | Mature and volume-based |
| U.S. prescribing | Restricted by safety positioning | Dominant |
| Differentiation potential | Moderate through patient selection | Limited |
Febuxostat can gain share when allopurinol is ineffective or poorly tolerated. It is unlikely to displace allopurinol across the broader gout market without a major change in cardiovascular interpretation or clinical guidelines.
What is the revenue exposure for manufacturers and investors?
Uloric itself has limited current revenue exposure. The relevant investment opportunity is the wider febuxostat market, where value is distributed across generic suppliers and regional brands.
Revenue exposure is highest in:
- Markets with low generic penetration.
- Countries where febuxostat is reimbursed for allopurinol-intolerant patients.
- Suppliers with integrated active pharmaceutical ingredient and finished-dose manufacturing.
- Companies holding multiple country registrations.
- Manufacturers with hospital and pharmacy distribution.
Revenue exposure is lowest for a standalone U.S. brand strategy. Price competition, the boxed warning, and the absence of meaningful product differentiation limit the return from rebuilding Uloric as a premium brand.
What patent litigation or settlement risk affects Uloric?
There is no major current U.S. litigation dynamic comparable to active branded oncology or specialty-drug patent disputes. The important legal event was the transition from branded Uloric to generic febuxostat following loss of market exclusivity.
Paragraph IV litigation risk is therefore limited for the legacy Uloric product. Future disputes would more likely concern:
- New formulations.
- Manufacturing processes.
- Polymorphs.
- Combination products.
- Regulatory exclusivity for new clinical uses.
Settlement agreements are not a major current driver of U.S. febuxostat economics.
Key Takeaways
- Uloric is commercially obsolete as a major U.S. branded product.
- Generic febuxostat is the relevant market, with estimated global 2025 sales of $450 million to $650 million.
- Global sales could reach $550 million to $850 million by 2030 under a base-case forecast.
- Allopurinol remains the dominant competitor and first-line therapy.
- The FDA boxed warning is the largest U.S. commercial constraint.
- FAST trial data support a more favorable risk interpretation but have not removed the U.S. boxed warning.
- Patent barriers to ordinary febuxostat tablets are weak in mature markets.
- The strongest growth opportunities are in Asia and other markets with rising gout diagnosis and expanding treatment access.
- Generic price erosion will limit revenue growth even as patient volume increases.
FAQs About Uloric Market Size and Forecasts
Is Uloric still sold in the United States?
Uloric may remain available in limited branded channels, but generic febuxostat dominates U.S. prescribing and commercial volume.
What is the projected 2030 market size for febuxostat?
The base-case estimate is $550 million to $850 million in global annual sales by 2030.
Does febuxostat have biosimilar risk?
No. Febuxostat is a small-molecule drug, so it faces conventional generic competition rather than biosimilar competition.
Can Uloric regain premium pricing?
A broad premium-price recovery is unlikely without a new indication, differentiated formulation, or regulatory change affecting the cardiovascular warning.
Which region offers the strongest growth opportunity for febuxostat?
China, India, Japan, South Korea, and Southeast Asia offer the strongest volume opportunities because of growing gout prevalence, expanding diagnosis, and broader access to chronic urate-lowering therapy.
References
-
U.S. Food and Drug Administration. (2009). FDA approves Uloric for gout. FDA.
-
U.S. Food and Drug Administration. (2019). FDA adds boxed warning for increased risk of death with gout medicine Uloric (febuxostat). FDA.
-
Mackenzie, I. S., Ford, I., Nuki, G., Hall, F. C., Bhala, N., Banya, W., et al. (2020). Long-term cardiovascular safety of febuxostat compared with allopurinol in patients with gout: The FAST trial. The Lancet, 396(10264), 1745-1757.
-
U.S. Food and Drug Administration. (2024). Uloric prescribing information. FDA.
-
Takeda Pharmaceutical Company Limited. (2019). Annual report 2019. Takeda.
More… ↓
