Share This Page
Drug Sales Trends for LANOXIN
✉ Email this page to a colleague
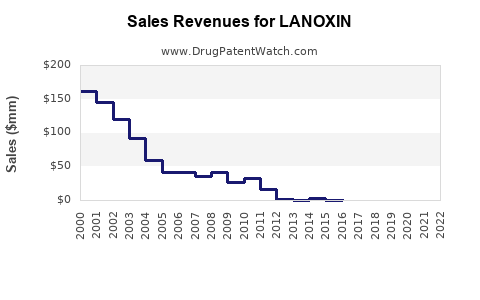
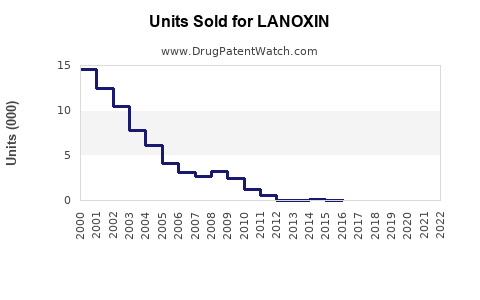
Annual Sales Revenues and Units Sold for LANOXIN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| LANOXIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| LANOXIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| LANOXIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| LANOXIN | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| LANOXIN | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| LANOXIN | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Lanoxin Market Analysis and Sales Projections: Digoxin Demand, Generic Competition and Patent Exposure
Lanoxin is the branded form of digoxin, a low-cost cardiac glycoside used primarily for selected patients with heart failure and for ventricular-rate control in atrial fibrillation. Its commercial market is mature, genericized and structurally declining. No material U.S. patent barrier protects Lanoxin from generic competition, and no biosimilar pathway applies because digoxin is a small-molecule drug.
The commercial outlook is defined by three factors: continued clinical use in a narrow patient population, substitution by generic digoxin, and low prices that limit revenue growth. A reasonable base-case estimate is for flat-to-low-single-digit annual decline in the global digoxin market through 2029, with branded Lanoxin revenue declining faster than the category.
What is Lanoxin and how is it used?
Lanoxin contains digoxin, a cardiac glycoside that increases cardiac contractility and slows atrioventricular-node conduction. U.S. labeling covers treatment of mild-to-moderate heart failure in adults and control of resting ventricular rate in patients with chronic atrial fibrillation [1].
Lanoxin is available in several dosage forms:
| Dosage form | Common strengths or presentation | Primary commercial use |
|---|---|---|
| Oral tablets | 62.5 mcg, 125 mcg, 250 mcg | Chronic outpatient treatment |
| Oral solution | 0.05 mg/mL | Patients requiring liquid dosing |
| Injection | 0.1 mg/2 mL and 0.25 mg/2 mL presentations, depending on market | Hospital and acute-care use |
Digoxin has a narrow therapeutic index. Renal function, age, body weight, electrolyte abnormalities and interactions with drugs such as amiodarone, verapamil and certain macrolide antibiotics affect exposure and toxicity risk [1].
The product is no longer a mass-market cardiovascular therapy. It is generally used when clinicians seek symptom control, rate control or an adjunctive option in patients for whom other therapies are inadequate, unsuitable or poorly tolerated.
How large is the Lanoxin and digoxin market?
No major manufacturer publicly reports Lanoxin revenue as a separate product line. Public company filings generally aggregate mature products, hospital products or regional portfolios. A reliable brand-specific sales figure therefore requires commercial prescription and channel data that are not publicly disclosed.
The market can be divided into three economic segments:
- Branded Lanoxin and other branded digoxin products.
- Generic oral digoxin tablets and oral solution.
- Hospital-administered injectable digoxin.
The generic segment accounts for most prescription volume in the United States and other developed markets. Brand revenue is supported by residual prescribing, institutional familiarity, product availability and occasional supply constraints affecting generics.
Estimated market structure
| Segment | Estimated share of global digoxin volume | Revenue outlook through 2029 |
|---|---|---|
| Generic oral tablets | 70%-85% | Stable to declining |
| Generic oral solution | 5%-10% | Stable, with niche demand |
| Injectable digoxin | 5%-15% | Stable in hospitals, subject to shortages |
| Branded Lanoxin and other brands | Less than 10% | Declines faster than generic market |
These ranges are analyst estimates rather than reported company figures. The product’s low unit price, mature clinical status and fragmented international distribution make total-market revenue difficult to measure from public filings.
What are the Lanoxin sales projections through 2029?
The base case assumes continued generic substitution, modest reduction in digoxin use in atrial fibrillation, stable use in selected heart-failure patients, and no major supply disruption.
Global digoxin market projection
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 estimated market revenue | $250 million | $350 million | $475 million |
| 2025 | $240 million | $345 million | $480 million |
| 2026 | $225 million | $338 million | $485 million |
| 2027 | $210 million | $331 million | $485 million |
| 2028 | $195 million | $324 million | $485 million |
| 2029 | $180 million | $318 million | $480 million |
| 2024-2029 CAGR | -6.3% | -1.9% | 0.2% |
The model includes branded and generic digoxin across oral and injectable products. The broad range reflects limited public visibility into international sales, hospital purchasing and branded net prices.
Lanoxin brand revenue projection
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 estimated brand revenue | $25 million | $45 million | $75 million |
| 2025 | $22 million | $42 million | $72 million |
| 2026 | $19 million | $39 million | $70 million |
| 2027 | $16 million | $36 million | $68 million |
| 2028 | $14 million | $33 million | $66 million |
| 2029 | $12 million | $30 million | $64 million |
| 2024-2029 CAGR | -11.7% | -7.7% | -3.1% |
The base case implies approximately $210 million of cumulative Lanoxin revenue from 2025 through 2029. This is a commercial modeling range, not a reported manufacturer forecast.
The main upside case is not a substantial increase in patient demand. It is temporary branded pricing power caused by generic shortages, restricted competition or hospital procurement disruptions. The main downside case is accelerated conversion to generic digoxin and continued movement toward alternative therapies.
When does Lanoxin lose exclusivity?
Lanoxin has already lost practical market exclusivity in the United States. Digoxin has been available from multiple generic manufacturers for many years, and the product is not dependent on a pending patent expiry to determine generic entry.
| Exclusivity element | Lanoxin status |
|---|---|
| New chemical entity exclusivity | Expired |
| Orphan-drug exclusivity | None identified |
| Pediatric exclusivity | No current material protection identified |
| U.S. Orange Book patent barrier | No active blocking patent identified in the reviewed records |
| Generic availability | Yes |
| Biosimilar exposure | Not applicable |
The original Lanoxin approvals date to the legacy drug era. The commercial question is therefore not when exclusivity ends, but how much branded demand remains after years of generic substitution.
What patents protect Lanoxin?
No active U.S. patent estate appears to provide meaningful protection for the core Lanoxin product. The relevant protection categories are:
Active ingredient patents
The active ingredient, digoxin, is an old small molecule. Any original composition-of-matter protection has expired. No new chemical entity protection remains commercially relevant.
Formulation patents
Lanoxin tablets and oral solution use conventional dosage forms. No widely recognized active Orange Book formulation patent presently blocks generic digoxin tablets, oral solution or injectable products in the United States [2].
Manufacturers may hold manufacturing know-how involving particle size, dissolution control, content uniformity, stability or packaging. Those rights can affect production economics but generally do not create the type of regulatory exclusivity associated with an active Orange Book patent.
Method-of-use patents
The principal Lanoxin indications are longstanding uses. No currently material method-of-use patent appears to prevent generic approval for the established heart-failure or atrial-fibrillation indications.
Potential method-of-use disputes would face practical limits because generic labeling, physician prescribing practices and the age of the indications reduce the value of narrow use claims.
What is the Orange Book status of Lanoxin?
The FDA Orange Book identifies approved drug products and relevant patent and exclusivity information. Lanoxin is an approved reference product for digoxin products, but the existence of reference-product status does not imply current market exclusivity [2].
Generic digoxin approvals can rely on the abbreviated new drug application pathway when the applicant demonstrates pharmaceutical equivalence and bioequivalence. The main regulatory hurdle is technical performance, not patent clearance.
Orange Book commercial implications
- Generic applicants can enter without waiting for a future Lanoxin patent expiry if no blocking patent is listed.
- Paragraph IV certifications are not the central entry mechanism for Lanoxin because the product does not have a meaningful current patent thicket.
- Any litigation risk is more likely to involve manufacturing, labeling, supply or commercial-contract issues than an innovative patent estate.
- Brand retention depends on prescribing inertia, supply reliability and reimbursement rather than exclusivity.
Which companies are challenging Lanoxin?
Generic competition is already established rather than pending. Depending on market and time period, digoxin products have been supplied by multiple generic and specialty pharmaceutical companies. The competitive set can include large generic manufacturers, hospital suppliers and regional drug companies.
The market is fragmented because digoxin is inexpensive and has limited growth potential. Competitors compete primarily on:
- Reliable supply of low-dose tablets.
- Consistent content uniformity.
- Injectable availability for hospitals.
- Contract pricing.
- Distribution coverage.
- Ability to maintain production despite low margins.
No single generic entrant is likely to transform the market. The larger risk to Lanoxin is cumulative substitution across many generic suppliers.
What generic entry risks exist for Lanoxin?
Generic entry risk is high because entry has already occurred and the principal products are simple oral and injectable dosage forms.
Risk by product type
| Product | Generic entry risk | Main barrier |
|---|---|---|
| Digoxin tablets | Very high | Low technical complexity and established generic pathway |
| Oral solution | High | Dosing accuracy, stability and packaging |
| Injectable digoxin | High but operationally variable | Sterility, manufacturing capacity and hospital supply |
| Brand Lanoxin | Very high substitution risk | No meaningful patent barrier |
A narrow therapeutic index increases the importance of bioequivalence and manufacturing consistency. It does not restore brand exclusivity. FDA guidance and product-specific regulatory requirements can raise development costs, but the market remains accessible to experienced generic manufacturers.
What FDA regulatory issues affect Lanoxin sales?
FDA labeling continues to emphasize individualized dosing, renal function and toxicity monitoring [1]. Those requirements influence prescribing but do not materially expand the commercial market.
Clinical guidelines have reduced the role of digoxin relative to other therapies. In heart failure with reduced ejection fraction, contemporary treatment typically prioritizes angiotensin receptor-neprilysin inhibitors or other renin-angiotensin-system therapies, beta blockers, mineralocorticoid receptor antagonists and sodium-glucose cotransporter-2 inhibitors where appropriate [3].
For atrial fibrillation, beta blockers, nondihydropyridine calcium-channel blockers and rhythm-control strategies compete with digoxin. Digoxin remains relevant in selected patients, including some patients with heart failure or limited tolerance for alternatives [4].
The regulatory profile is stable:
| Regulatory factor | Commercial effect |
|---|---|
| Approved indications | Supports continued niche demand |
| Narrow therapeutic index | Increases monitoring and prescribing caution |
| Generic approval pathway | Enables sustained price competition |
| No biologic status | Eliminates biosimilar complexity |
| Established safety profile | Limits clinical differentiation |
| Older product status | Reduces innovation-based pricing power |
Does Lanoxin face biosimilar risk?
No. Biosimilars apply to biologic products, while Lanoxin contains the small-molecule active ingredient digoxin. The relevant competition is generic substitution through abbreviated new drug applications, not biosimilar approval.
This distinction matters for commercial forecasting. Lanoxin does not receive the higher barriers associated with biologic manufacturing, interchangeability or reference-product exclusivity. Generic manufacturers can compete through conventional pharmaceutical development and supply operations.
What patent litigation affects Lanoxin?
No major active U.S. patent litigation is central to the Lanoxin commercial outlook based on the absence of a material current patent estate. The product’s legal risk is more likely to arise from:
- Product liability claims involving toxicity.
- Manufacturing or quality-control actions.
- Supply and shortage disputes.
- Contract and distribution arrangements.
- State substitution and reimbursement rules.
A Paragraph IV challenge would have limited strategic value unless a later-listed patent covered a specific formulation, dosage form or method. The core Lanoxin product is too old for an original patent challenge to determine market entry.
How does Lanoxin compare with competing heart-failure and atrial-fibrillation drugs?
Lanoxin competes against therapies that have stronger guideline positioning and larger commercial markets.
| Drug class | Examples | Relative position versus Lanoxin |
|---|---|---|
| Beta blockers | Metoprolol, carvedilol, bisoprolol | Broader use in heart failure and rate control |
| SGLT2 inhibitors | Dapagliflozin, empagliflozin | Stronger growth and modern guideline support |
| ARNI and RAAS therapies | Sacubitril/valsartan, ACE inhibitors, ARBs | Core heart-failure treatment |
| Mineralocorticoid antagonists | Spironolactone, eplerenone | Established adjunctive heart-failure role |
| Nondihydropyridine calcium-channel blockers | Diltiazem, verapamil | Important rate-control competitors in selected patients |
| Digoxin | Lanoxin and generic digoxin | Low-cost, narrow-use option |
Lanoxin’s price advantage does not offset its limited clinical differentiation. Its principal competitive strength is affordability and familiarity, not innovation.
What licensing deals affect Lanoxin?
No major recent licensing transaction appears to drive Lanoxin’s commercial value. Mature digoxin products are more commonly transferred through product portfolios, distribution agreements or regional marketing arrangements than through high-value innovation licenses.
The most important commercial counterparties are likely to be:
- Generic manufacturers.
- Hospital wholesalers.
- Pharmacy benefit managers.
- Specialty and institutional distributors.
- Regional marketing authorization holders.
A product-rights transaction could still create value if it improves supply reliability or expands distribution in a market with limited generic availability. Such value would be operational rather than patent-driven.
What is the geographic coverage of Lanoxin?
Lanoxin and digoxin products are marketed in multiple regions, but brand availability and ownership vary by country. Generic substitution is strongest in the United States, Western Europe and other mature markets. Brand persistence can be higher in jurisdictions where:
- The brand has strong physician recognition.
- Generic substitution is less automatic.
- Local supply is concentrated.
- Public procurement favors established products.
- Reimbursement differences reduce the effect of low-cost generics.
International revenue is therefore sensitive to local regulatory approvals, reimbursement policies, tender outcomes and distribution agreements. U.S. patent analysis does not determine the product’s global commercial position.
What manufacturing and intellectual-property barriers affect Lanoxin?
Manufacturing barriers are moderate despite weak patent protection. Digoxin requires tight control of potency and content uniformity because dosing differences can affect safety. Manufacturers also need validated processes for low-dose tablets, stable liquid formulations and sterile injectable products.
The principal barriers are operational:
- Sourcing consistent digoxin active pharmaceutical ingredient.
- Achieving uniform distribution at microgram strengths.
- Maintaining validated dissolution and stability.
- Meeting sterile manufacturing requirements for injection.
- Avoiding supply interruptions in a low-margin market.
- Maintaining regulatory compliance across multiple facilities.
These factors can temporarily support brand or incumbent pricing, but they do not create durable exclusivity. A well-capitalized generic supplier with established regulatory infrastructure can overcome them.
What is the investment outlook for Lanoxin?
Lanoxin is a cash-flow preservation asset rather than a growth asset. Its value is concentrated in existing demand, low development expenditure and potential pricing resilience during supply disruptions.
The investment case is strongest where the owner has:
- Low manufacturing costs.
- Durable distribution contracts.
- Reliable injectable supply.
- Exposure to markets with weak generic substitution.
- A broad cardiovascular portfolio that absorbs commercial overhead.
The investment case is weak where value depends on:
- Patent-based pricing.
- New indications.
- Significant volume growth.
- Premium pricing over generic digoxin.
- Large-scale physician conversion.
Revenue exposure is likely to remain modest compared with modern cardiovascular products. The brand’s main risk is erosion, not a single catastrophic patent expiry.
Key Takeaways
- Lanoxin is the branded form of digoxin, an established small-molecule cardiovascular drug.
- Generic competition is already extensive, and no material U.S. patent barrier protects the core product.
- Biosimilar risk does not apply.
- The global digoxin market is likely to decline modestly through 2029, with a base-case CAGR of approximately -1.9%.
- Branded Lanoxin revenue is likely to decline faster, with a modeled base-case CAGR of approximately -7.7%.
- The 2024 global Lanoxin brand revenue estimate is modeled at $25 million to $75 million, with a $45 million base case.
- Supply reliability, hospital demand and regional brand loyalty matter more than patent litigation.
- Lanoxin is a mature cash-flow product with limited growth potential and high generic-substitution risk.
FAQs
Is Lanoxin still sold in the United States?
Yes. Lanoxin and generic digoxin products may be available through U.S. channels, although product availability can vary by dosage form, manufacturer and supply conditions.
Can a generic manufacturer launch digoxin without challenging a Lanoxin patent?
Yes. Generic digoxin has been available for years, and no current core patent barrier is generally understood to prevent entry.
Is Lanoxin more effective than generic digoxin?
Approved generic digoxin products must meet FDA requirements for pharmaceutical equivalence and bioequivalence. Brand preference may persist because of familiarity or supply reliability, not because Lanoxin has a known clinical advantage over equivalent generic digoxin.
What causes Lanoxin toxicity?
Toxicity risk increases with excessive exposure, impaired kidney function, older age, low potassium or magnesium levels, and interactions with certain cardiovascular and anti-infective drugs. Product labeling recommends individualized dosing and monitoring [1].
Could Lanoxin sales increase during a generic shortage?
Yes. A shortage or production interruption affecting generic digoxin could temporarily increase branded demand or pricing. Such an increase would likely be episodic rather than a durable reversal of the long-term decline.
References
-
U.S. Food and Drug Administration. (2023). Lanoxin (digoxin) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
Heidenreich, P. A., Bozkurt, B., Aguilar, D., Allen, L. A., Byun, J. J., Colvin, M. M., Deswal, A., Drazner, M. H., Dunlay, S. M., Evers, L. R., Fang, J. C., Fonarow, G. C., Hayek, S. S., Hernandez, A. F., Khazanie, P., Kittleson, M. M., Lee, C. S., Link, M. S., Milano, C. A., ... Yancy, C. W. (2022). 2022 AHA/ACC/HFSA guideline for the management of heart failure. Circulation, 145(18), e895-e1032.
-
Hindricks, G., Potpara, T., Dagres, N., Arbelo, E., Bax, J. J., Blomström-Lundqvist, C., Boriani, G., Castella, M., Dan, G. A., Dilaveris, P. E., Fauchier, L., Filippatos, G., Kalman, J. M., La Meir, M., Lane, D. A., Lebeau, J. P., Lettino, M., Lip, G. Y. H., Pinto, F. J., ... Watkins, C. L. (2021). 2020 ESC guidelines for the diagnosis and management of atrial fibrillation. European Heart Journal, 42(5), 373-498.
More… ↓
