Share This Page
Drug Sales Trends for norethindrone
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for norethindrone (2021)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
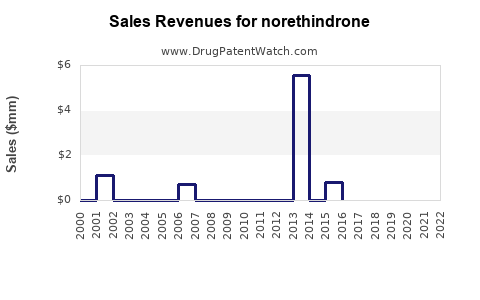
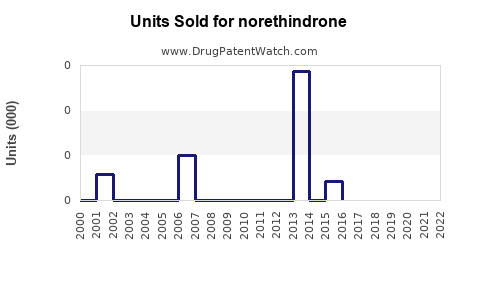
Annual Sales Revenues and Units Sold for norethindrone
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| NORETHINDRONE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| NORETHINDRONE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| NORETHINDRONE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Norethindrone Market Analysis and Sales Projections, 2025-2030
Norethindrone is a mature, low-cost generic progestin market with stable clinical demand and limited patent protection. Revenue is concentrated in generic norethindrone and norethindrone acetate tablets used for contraception, abnormal uterine bleeding, endometriosis, and secondary amenorrhea. No single manufacturer has publicly reported global norethindrone sales, so the projections below are modeled estimates rather than audited company revenue.
The U.S. market is likely to remain broadly stable through 2030. Volume growth from contraceptive demand and continued use in gynecologic disorders should offset price erosion. The primary commercial risk is generic substitution and reimbursement pressure, not loss of patent exclusivity.
| Metric | 2024 estimated base | 2030 base-case projection |
|---|---|---|
| U.S. market value, manufacturer net sales | $85 million-$125 million | $80 million-$120 million |
| Global market value, manufacturer net sales | $170 million-$275 million | $165 million-$285 million |
| U.S. prescription volume | 8 million-12 million prescriptions | 8.5 million-12.5 million |
| Average annual U.S. price erosion | Not publicly reported | 2%-5% |
| Branded-product exposure | Low | Low |
| Biosimilar risk | None | None |
| Patent-based exclusivity | None of material commercial significance | None of material commercial significance |
What is norethindrone and which products generate demand?
Norethindrone is a synthetic progestin marketed in multiple oral dosage forms and strengths. Norethindrone acetate is the acetate salt used in several gynecologic indications and is pharmacologically converted to norethindrone after administration.
The main commercial segments are:
| Segment | Common strength or product type | Primary use | Commercial profile |
|---|---|---|---|
| Norethindrone contraceptive | 0.35 mg tablet | Progestin-only oral contraception | High-volume, low-price generic |
| Norethindrone acetate | 5 mg tablet | Abnormal uterine bleeding, endometriosis, amenorrhea | Lower volume, higher price per prescription |
| Higher-strength gynecologic products | 5 mg to 10 mg regimens | Cycle control and endometriosis | Prescription-driven and specialist-influenced |
| Combination products | Ethinyl estradiol plus norethindrone or norethindrone acetate | Combined oral contraception and hormone therapy | Separate competitive market |
| Compounded or specialty formulations | Variable | Selected gynecologic uses | Small and fragmented |
Norethindrone is distinct from norgestrel, levonorgestrel, drospirenone, desogestrel, and medroxyprogesterone acetate. The FDA-approved over-the-counter progestin-only contraceptive Opill contains norgestrel, not norethindrone. That product may expand consumer awareness of progestin-only contraception but does not directly increase norethindrone sales.
How large is the norethindrone market?
The market is fragmented across generic manufacturers, wholesalers, retail pharmacies, mail-order pharmacies, and health-system purchasing contracts. Public company filings generally combine norethindrone sales with broader generic portfolios, preventing a clean product-level revenue calculation.
A practical market estimate separates the market into two pools:
Norethindrone contraceptive market
The 0.35 mg progestin-only tablet is prescribed to patients who cannot use estrogen-containing contraceptives or who prefer a progestin-only option. Demand is affected by contraceptive access, insurance coverage, physician prescribing, pregnancy-prevention preferences, and availability of long-acting reversible contraception.
This segment likely accounts for the largest prescription volume but not necessarily the largest gross margin. Generic prices are constrained by multiple approved suppliers and pharmacy benefit manager purchasing.
Norethindrone acetate gynecology market
Norethindrone acetate is used for abnormal uterine bleeding, endometriosis, and amenorrhea. It has lower unit volume than the contraceptive segment but can generate higher revenue per prescription because of higher strengths, longer treatment courses, and specialist prescribing.
Demand is linked to diagnosis rates, use of hormonal therapy before surgery, endometriosis management, and the treatment of heavy menstrual bleeding. The segment also competes with oral contraceptives, progestin-releasing intrauterine systems, medroxyprogesterone acetate, GnRH antagonists, and surgical interventions.
What are the key market drivers for norethindrone?
The principal demand drivers are clinical utility, low cost, and broad generic availability.
| Driver | Effect on market |
|---|---|
| Progestin-only contraception | Supports recurring prescription demand |
| Abnormal uterine bleeding | Supports 5 mg norethindrone acetate use |
| Endometriosis | Supports specialist and longer-course treatment |
| Low generic price | Expands payer coverage but limits revenue growth |
| Contraceptive access | Can increase prescription volume |
| Alternative hormonal therapies | Limits volume growth |
| Long-acting contraception | Competes with daily oral products |
| Generic supply continuity | Determines short-term manufacturer share |
The FDA lists norethindrone and norethindrone acetate products in approved generic dosage forms, while DailyMed labeling confirms the principal approved indications and dosage strengths.[1,2] The CDC continues to recognize progestin-only pills as an established contraceptive option, subject to patient-specific medical considerations.[3]
What are the projected norethindrone sales through 2030?
The following forecast uses a modeled U.S. and global market base. It assumes stable prescription demand, continued generic competition, moderate price erosion, and no major safety withdrawal or supply disruption.
U.S. sales projection
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $80 million | $105 million | $130 million |
| 2025 | $77 million | $104 million | $132 million |
| 2026 | $74 million | $103 million | $134 million |
| 2027 | $72 million | $103 million | $137 million |
| 2028 | $70 million | $104 million | $140 million |
| 2029 | $68 million | $105 million | $143 million |
| 2030 | $66 million | $106 million | $146 million |
The base case assumes annual prescription growth of approximately 1% to 2%, offset by price erosion of approximately 2% to 3%. The bear case reflects accelerated generic price compression and substitution by long-acting contraception or alternative hormonal therapies. The bull case assumes higher gynecologic treatment volumes, improved access to contraception, and a relatively stable supplier base.
Global sales projection
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $160 million | $220 million | $290 million |
| 2025 | $157 million | $221 million | $295 million |
| 2026 | $154 million | $222 million | $300 million |
| 2027 | $151 million | $224 million | $305 million |
| 2028 | $149 million | $226 million | $310 million |
| 2029 | $147 million | $228 million | $315 million |
| 2030 | $145 million | $230 million | $320 million |
Global growth is more dependent on access to generic medicines, local pricing, tender contracts, and regulatory approval than on innovation. Markets with public procurement systems may show higher volume but lower realized prices.
Which companies compete in the norethindrone market?
The market includes generic manufacturers and distributors with broad women’s-health portfolios. U.S. suppliers have included companies such as:
- Amneal Pharmaceuticals
- Glenmark Pharmaceuticals
- Lupin
- Mayne Pharma
- Mylan, now part of Viatris
- Teva Pharmaceuticals
- Watson/Actavis, now associated with Teva’s broader generic operations
- Other ANDA holders and contract manufacturers
Supplier participation varies by strength, dosage form, national market, and manufacturing availability. A company may hold an FDA-approved abbreviated new drug application while having limited commercial distribution.
Competition occurs on:
- Wholesale acquisition price and contract price.
- Product availability and fill-rate performance.
- Authorized generic and private-label supply.
- Pharmacy benefit manager access.
- Manufacturing reliability.
- Regulatory compliance and inspection history.
A manufacturer with a low-cost product has limited ability to sustain premium pricing unless it has a supply advantage, a preferred contract, or a differentiated formulation.
What is the FDA regulatory status of norethindrone?
Norethindrone and norethindrone acetate are established prescription drug products with FDA-approved generic versions. Generic products are generally approved through the Abbreviated New Drug Application pathway, which relies on bioequivalence to the reference product rather than new clinical efficacy trials.[4]
The FDA’s regulatory framework creates several commercial consequences:
- New entrants must demonstrate pharmaceutical equivalence and bioequivalence.
- The product does not require a new chemical entity development program.
- Regulatory approval is less expensive than approval of a novel hormonal therapy.
- Multiple ANDA approvals can increase price competition.
- Manufacturing or compliance problems can temporarily shift market share to remaining suppliers.
The contraceptive and gynecologic indications are established. Regulatory differentiation is therefore more likely to come from dosage form, packaging, adherence support, supply reliability, or combination products than from new efficacy claims.
What patents protect norethindrone products?
The active pharmaceutical ingredient is long established, and original composition-of-matter protection has expired. Generic norethindrone and norethindrone acetate products do not have a commercially meaningful remaining compound patent estate.
| Protection category | Current commercial position |
|---|---|
| Norethindrone compound patent | Expired |
| Norethindrone acetate compound patent | Expired or no longer commercially relevant |
| Generic product patents | Limited and product-specific |
| Formulation patents | Possible for particular combinations or delivery systems |
| Method-of-use patents | Limited value because core indications are established |
| Pediatric exclusivity | Not a current market driver |
| Orphan-drug exclusivity | Not applicable to the core market |
| Biosimilar exclusivity | Not applicable |
The relevant patent question is not whether norethindrone remains protected as a molecule. It does not. The question is whether a specific branded combination, modified-release product, packaging system, or delivery technology has separate patent rights.
When does norethindrone lose exclusivity?
Norethindrone already lost meaningful market exclusivity decades ago. The U.S. market is post-exclusivity and genericized.
There is no single future loss-of-exclusivity date comparable to a patented branded drug because:
- The core active ingredient is old.
- Multiple generic suppliers are present.
- Product-level approvals are distributed among many ANDA holders.
- Any remaining patents are likely to relate to specific products rather than the molecule.
- Generic substitution is already established.
The Orange Book remains the principal FDA source for listed patents, exclusivity periods, and therapeutic-equivalence information for approved products.[5] A product-by-product Orange Book review is required to identify any active patent listing for a particular branded combination or formulation.
Are there Paragraph IV challenges involving norethindrone?
Paragraph IV litigation is not a central commercial issue for conventional generic norethindrone. Paragraph IV certifications typically arise when an ANDA applicant seeks approval for a product referencing a branded drug with listed patents. Because conventional norethindrone products are mature generics with limited patent protection, commercial entry generally depends more on ANDA approval, manufacturing readiness, and supply contracts than on patent litigation.
Potential Paragraph IV exposure is more relevant to:
- New fixed-dose combinations containing norethindrone or norethindrone acetate.
- Modified-release formulations.
- Branded hormone-therapy products.
- Delivery systems with separate formulation claims.
- Products with method-of-use patents listed in the Orange Book.
No broad, molecule-level Paragraph IV barrier should be assumed for standard norethindrone tablets.
What formulation patents protect norethindrone?
Conventional immediate-release norethindrone tablets have limited differentiation. Potential patent value may arise from:
- Modified-release tablets.
- Fixed-dose combinations with estrogen.
- Transdermal or vaginal delivery systems.
- Specific excipient combinations.
- Stability-enhancing formulations.
- Low-dose contraceptive packaging and adherence systems.
- New dosing regimens supported by clinical and patent claims.
These rights would protect a particular product, not the generic norethindrone market as a whole. Their commercial value depends on whether the formulation is clinically preferred, reimbursed, and difficult to design around.
What generic entry risks exist for norethindrone manufacturers?
Generic entry risk is already realized rather than pending. The main risks to an individual supplier are share loss, price competition, and supply substitution.
Commercial risks
- Additional ANDA approvals can reduce contract prices.
- Pharmacy benefit managers may shift volume rapidly.
- Retail pharmacies can substitute among therapeutically equivalent products.
- Large buyers may dual-source or multi-source supply.
- Shortages can cause temporary share gains but may also trigger expedited competitor entry.
- Regulatory observations can remove a supplier from preferred distribution.
Competitive alternatives
Norethindrone competes with:
- Levonorgestrel intrauterine systems.
- Etonogestrel implants.
- Depot medroxyprogesterone acetate.
- Combined oral contraceptives.
- Drospirenone-only pills.
- GnRH antagonists for selected gynecologic conditions.
- Surgical treatment for refractory abnormal uterine bleeding.
The strongest long-term volume threat is not another norethindrone tablet. It is increased use of long-acting contraceptive products and newer therapies for endometriosis and heavy menstrual bleeding.
How does norethindrone compare with competing progestins?
| Product | Main commercial advantage | Main limitation versus norethindrone |
|---|---|---|
| Norethindrone | Low cost, established use, broad generic supply | Daily dosing and low supplier differentiation |
| Drospirenone-only pill | Newer progestin-only contraceptive option | Higher cost and less mature generic competition |
| Levonorgestrel IUD | Long duration and high contraceptive effectiveness | Device insertion and higher upfront cost |
| Etonogestrel implant | Long duration and adherence advantage | Procedure-based placement and removal |
| Depot medroxyprogesterone acetate | Infrequent administration | Injection-related concerns and adverse-effect profile |
| Combined oral contraceptives | Broad product choice and cycle control | Estrogen restrictions for some patients |
| GnRH antagonists | Targeted endometriosis or fibroid treatment | Higher cost and more complex safety management |
Norethindrone retains a cost and access advantage. It is less differentiated on adherence, duration, and convenience.
What licensing deals affect norethindrone?
No major licensing transaction is required to commercialize standard generic norethindrone. Companies generally rely on their own ANDAs, contract manufacturing, or commercial supply agreements.
Licensing activity is more likely in:
- Combination hormonal products.
- Specialty delivery systems.
- Branded women’s-health portfolios.
- Regional distribution rights.
- Contract manufacturing and private-label supply.
- Consumer-health conversions or nonprescription contraceptive products.
A licensing deal involving norethindrone would have greater value if it transferred a differentiated formulation, regulatory approval, manufacturing capability, or established payer access. A license to the active ingredient alone would have limited strategic value.
What is the revenue exposure for generic manufacturers?
Norethindrone is usually a small component of a diversified generic manufacturer’s revenue. Its strategic value comes from portfolio breadth, recurring demand, and low development complexity rather than blockbuster economics.
For a manufacturer, a standard norethindrone product may generate:
- Low absolute revenue per SKU.
- Stable prescription turnover.
- Limited marketing expense.
- Low pricing power.
- High sensitivity to manufacturing cost.
- Potentially attractive margins during temporary supply shortages.
A portfolio containing multiple strengths, combination products, and gynecologic indications can produce better economics than a single 0.35 mg contraceptive SKU.
What is the outlook for norethindrone from 2025 to 2030?
The base-case outlook is flat to modestly positive in nominal sales and broadly stable in volume. The market should remain commercially viable for efficient generic suppliers but unattractive for companies seeking patent-protected pricing.
The most likely market pattern is:
- Stable contraceptive demand.
- Moderate growth in treatment of abnormal uterine bleeding and endometriosis.
- Continued erosion in generic prices.
- No material molecule-level patent event.
- Periodic share shifts caused by supply disruptions.
- Gradual substitution by long-acting contraception and newer specialty therapies.
Key Takeaways
- Norethindrone is a mature generic progestin with no material remaining compound exclusivity.
- The U.S. market is estimated at approximately $85 million to $125 million in annual manufacturer net sales.
- Base-case U.S. sales are projected at approximately $106 million in 2030.
- Global sales are estimated at approximately $170 million to $275 million, with a 2030 base case near $230 million.
- Norethindrone acetate for abnormal uterine bleeding and endometriosis provides higher value per prescription than the 0.35 mg contraceptive tablet.
- Generic substitution, payer contracting, and manufacturing reliability matter more than patent litigation.
- Biosimilar risk is irrelevant because norethindrone is a small-molecule drug.
- New formulation and combination-product patents may protect individual products but do not protect the conventional norethindrone market.
- The principal long-term competitive threat is substitution by long-acting contraceptives and newer gynecologic therapies.
FAQs
Is norethindrone a blockbuster drug?
No. Norethindrone is a mature generic medicine with fragmented sales and low pricing. It does not have the revenue profile of a branded blockbuster.
Is norethindrone acetate more commercially valuable than norethindrone 0.35 mg?
Usually, yes, on a per-prescription basis. Norethindrone acetate 5 mg is used in gynecologic treatment courses that can support higher prescription value, while 0.35 mg norethindrone is a high-volume, low-price contraceptive product.
Can a new company still enter the norethindrone market?
Yes. Entry is generally possible through an ANDA, subject to FDA approval, bioequivalence, manufacturing capacity, and commercial distribution. Patent barriers are unlikely to be the primary obstacle for standard tablets.
Does Opill compete directly with norethindrone?
Opill competes in the progestin-only contraceptive category but contains norgestrel rather than norethindrone. Its nonprescription availability may affect contraceptive behavior without creating direct pharmaceutical equivalence.
What would increase norethindrone sales most significantly?
The strongest potential growth factors are expanded contraceptive access, higher diagnosis and treatment of abnormal uterine bleeding, increased use in endometriosis management, and temporary supply shortages affecting competing suppliers.
References
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. https://www.accessdata.fda.gov/scripts/cder/daf/
-
National Library of Medicine. (2024). DailyMed: Norethindrone acetate tablet labeling. https://dailymed.nlm.nih.gov/dailymed/
-
Centers for Disease Control and Prevention. (2024). U.S. medical eligibility criteria for contraceptive use, 2024. Morbidity and Mortality Weekly Report, 73(4). https://www.cdc.gov/mmwr/
-
U.S. Food and Drug Administration. (2024). Generic drug facts. https://www.fda.gov/drugs/generic-drugs
-
U.S. Food and Drug Administration. (2025). Approved drug products with therapeutic equivalence evaluations, 45th edition. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book-data-files-enabled-downloads
More… ↓
