Share This Page
Drug Sales Trends for RISPERIDONE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for RISPERIDONE (2021)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
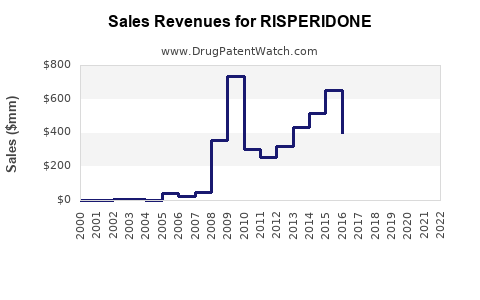
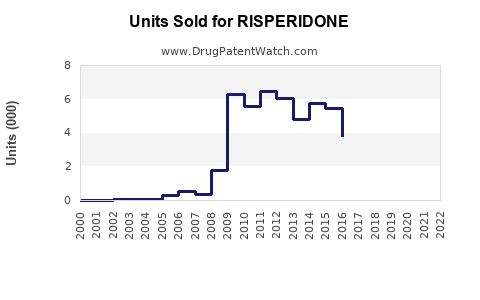
Annual Sales Revenues and Units Sold for RISPERIDONE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| RISPERIDONE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| RISPERIDONE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| RISPERIDONE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Risperidone Market Analysis, Sales Projections, Patent Status, and Generic Competition
Risperidone is a mature antipsychotic with a declining oral tablet market and a growing long-acting injectable segment. Generic risperidone controls most global volume, while differentiated injectable products such as Uzedy, Perseris, Rykindo, and Risperdal Consta capture higher revenue per patient. The commercial opportunity is concentrated in long-acting formulations, adherence-focused care, institutional psychiatry, and selected pediatric and behavioral-health indications.
Global risperidone product revenue is difficult to isolate because manufacturers report oral and injectable products separately, private companies do not disclose sales, and generic revenue is fragmented. A reasonable base-case estimate places global risperidone-related product sales at approximately $1.0 billion to $1.4 billion in 2024, with long-acting injectables representing roughly 55% to 70% of branded revenue but a much smaller share of treated patients.
What is the current risperidone market size?
Risperidone is marketed as an oral antipsychotic and as several injectable dosage forms. The principal commercial products are:
| Product | Active ingredient | Formulation | Primary company | U.S. status |
|---|---|---|---|---|
| Risperdal | Risperidone | Tablet, orally disintegrating tablet, oral solution | Janssen | Brand legacy product; generic competition |
| Risperdal Consta | Risperidone | Long-acting intramuscular injection | Janssen | Approved; mature injectable franchise |
| Perseris | Risperidone | Once-monthly subcutaneous injection | Indivior | Approved in 2018 |
| Rykindo | Risperidone | Long-acting intramuscular injection | Luye Pharma | Approved in 2022 |
| Uzedy | Risperidone | Once-monthly or once-every-two-months subcutaneous injection | Teva Pharmaceuticals and MedinCell | Approved in 2023 |
| Generic risperidone | Risperidone | Tablets, oral solution, orally disintegrating tablets | Multiple manufacturers | Broadly available |
The market is structurally divided:
- Low-cost oral generic treatment.
- High-value depot and extended-release injection treatment.
- Institutional, Medicaid, and government-funded behavioral-health channels.
- Specialist psychiatric care, where adherence and relapse prevention support injectable use.
The oral market is mature and price-competitive. Growth is concentrated in long-acting formulations that address missed doses, adherence monitoring, and recurring psychiatric hospitalization.
How much are risperidone products expected to sell?
The following projection is an analytical market estimate rather than a company-reported total. It assumes stable diagnosed schizophrenia prevalence, gradual migration from oral therapy to long-acting injections, continued generic price erosion, and no major safety-driven withdrawal.
| Year | Global risperidone-related sales estimate | Oral generic and branded sales | Long-acting injectable sales | Market condition |
|---|---|---|---|---|
| 2023 | $1.0B-$1.3B | $350M-$500M | $650M-$800M | Mature market; injectable competition expands |
| 2024 | $1.0B-$1.4B | $325M-$475M | $675M-$925M | Uzedy launch investment; Rykindo expansion |
| 2025 | $1.05B-$1.45B | $300M-$450M | $750M-$1.0B | Injectable share increases |
| 2026 | $1.1B-$1.55B | $275M-$425M | $825M-$1.1B | More conversion from oral therapy |
| 2027 | $1.15B-$1.65B | $250M-$400M | $900M-$1.25B | Depot products drive market growth |
| 2028 | $1.2B-$1.75B | $225M-$375M | $975M-$1.35B | Higher formulation mix offsets oral erosion |
The base case implies a 2023-2028 compound annual growth rate of approximately 3% to 6%. The forecast is driven by formulation mix rather than growth in total risperidone-treated patients.
Bull-case scenario
Under a faster conversion to long-acting therapy, improved reimbursement, and broader use of two-month dosing, global sales could reach $1.8 billion to $2.1 billion by 2028. The main beneficiaries would be Uzedy, Perseris, Rykindo, and any approved generic depot products.
Bear-case scenario
Under accelerated price competition, limited payer coverage, and slow provider adoption, sales could remain near $1.0 billion to $1.2 billion through 2028. Oral generic revenue would continue to decline, while injectable growth would be insufficient to offset price pressure.
Which risperidone products have the strongest commercial outlook?
Uzedy has the strongest growth profile among U.S. risperidone products because it combines subcutaneous administration with monthly and two-month dosing. The product uses MedinCell's BEPO extended-release technology and is marketed by Teva in the United States. FDA approved Uzedy in April 2023 for the treatment of schizophrenia in adults.[1]
Perseris has a differentiated once-monthly subcutaneous delivery system. Its commercial performance depends on reimbursement, injection-site administration, patient selection, and the ability to compete with Uzedy and established long-acting injectables. FDA approved Perseris in 2018 for the treatment of schizophrenia in adults.[2]
Risperdal Consta has the longest commercial history among risperidone injections. Its main disadvantages are intramuscular administration, a two-week dosing interval, and the need for oral supplementation during initiation. These factors create switching pressure toward newer monthly and two-month products.
Rykindo provides another long-acting intramuscular option. Its commercial opportunity is strongest in markets where depot antipsychotics have established reimbursement and where the product can compete on price or supply reliability.
| Product | Dosing interval | Administration | Principal commercial advantage | Principal risk |
|---|---|---|---|---|
| Risperdal Consta | Every two weeks | Intramuscular | Established clinical use and provider familiarity | Older delivery schedule and generic pressure |
| Perseris | Monthly | Subcutaneous | No oral supplementation requirement under labeled initiation approach | Limited market access and competitive differentiation |
| Rykindo | Monthly | Intramuscular | Additional depot option and potential price competition | Smaller commercial footprint |
| Uzedy | Monthly or every two months | Subcutaneous | Flexible dosing and newer delivery technology | High launch costs and payer competition |
When does risperidone lose exclusivity?
Risperidone's original U.S. composition-of-matter and primary regulatory exclusivity periods expired years ago. Oral generic competition is established. The principal commercial protection now lies in formulation patents, device or delivery technology, manufacturing know-how, trademarks, regulatory data, and provider adoption.
The historical exclusivity timeline is:
| Milestone | Approximate date |
|---|---|
| U.S. Risperdal approval | 1993 |
| First U.S. oral generic approvals | 2008 onward |
| Risperdal Consta U.S. approval | 2003 |
| Perseris U.S. approval | 2018 |
| Rykindo U.S. approval | 2022 |
| Uzedy U.S. approval | 2023 |
The relevant distinction is between the active ingredient and the product technology. Risperidone itself is a generic active pharmaceutical ingredient. Newer commercial products seek protection through extended-release matrices, dosing schedules, routes of administration, particle engineering, delivery systems, and manufacturing processes.
What patents protect risperidone products?
The strongest current patent positions generally relate to long-acting delivery technologies rather than risperidone's molecular structure.
Risperdal and oral risperidone
The original Risperdal patent estate no longer prevents ordinary generic tablets or oral solutions from entering the U.S. market. Generic manufacturers compete primarily on manufacturing cost, supply reliability, pharmacy access, and contracting.
Potential remaining barriers for specific oral products can include:
- Product-specific formulation claims.
- Orally disintegrating tablet composition claims.
- Polymorph or particle-size claims.
- Manufacturing-process claims.
- Method-of-use claims tied to particular populations or dosing regimens.
These claims generally have narrower commercial scope than the original active-ingredient patent.
Risperdal Consta
Risperdal Consta depends on long-acting microsphere technology, manufacturing controls, and depot release characteristics. The commercial barrier is not simply obtaining risperidone API. A competing product must demonstrate reproducible particle characteristics, release kinetics, sterility, stability, injection performance, and clinical comparability.
Perseris
Perseris is protected primarily through its depot delivery platform and product-specific formulation claims. The product's subcutaneous administration and monthly release profile create technical barriers that are distinct from ordinary oral generic development.
Uzedy
Uzedy's commercial protection is linked to MedinCell's BEPO technology, the subcutaneous extended-release formulation, dosing schedules, and associated patents and know-how. Teva and MedinCell have disclosed a development and commercialization relationship under which Teva commercializes the product in the United States.[3]
The patent estate may delay direct copies that use substantially similar delivery technology. It does not prevent all alternative risperidone injections. A competitor can seek freedom to operate through a different polymer system, route of administration, particle design, or release mechanism.
What is the FDA regulatory status of risperidone?
Risperidone is FDA-approved for schizophrenia in adults, acute treatment of manic or mixed episodes associated with bipolar I disorder, and irritability associated with autistic disorder in specified pediatric patients. The labeling differs by product and formulation.[4]
Long-acting products are regulated as drug products, not biologics. Biosimilar pathways therefore do not apply. The competitive pathway is based on an abbreviated new drug application for conventional generics or a 505(b)(2) new drug application for certain reformulations and delivery systems.
The regulatory complexity increases with injectable products because developers must address:
- Extended-release pharmacokinetics.
- Injection-site tolerability.
- Dose proportionality.
- Sterility and container closure.
- Release specifications.
- Manufacturing scale-up.
- Bridging between clinical and commercial batches.
- Administration by trained healthcare personnel.
Are there Paragraph IV challenges to risperidone products?
Paragraph IV risk is concentrated in long-acting injectable formulations rather than standard oral risperidone. Oral products have faced extensive generic competition, and the basic active ingredient is no longer a meaningful exclusivity barrier.
For newer injectable products, a Paragraph IV filing could challenge patents covering:
- Polymer composition.
- Microsphere or depot structure.
- Drug-loading percentage.
- Release duration.
- Injection volume.
- Dosing interval.
- Manufacturing processes.
- Method of initiating treatment without oral supplementation.
A Paragraph IV challenge would not automatically produce market entry. The patent holder could file an infringement action within 45 days, triggering a statutory stay of FDA approval for up to 30 months under the Hatch-Waxman framework, subject to statutory exceptions.[5]
The commercial timing of a generic injectable would depend on patent claims, FDA review, settlement terms, manufacturing readiness, and the ability to establish therapeutic equivalence or another acceptable approval basis.
What patent litigation affects risperidone?
The most important historical litigation involved Janssen's enforcement of Risperdal-related patents against generic manufacturers and disputes concerning pediatric use and marketing conduct. Those disputes are largely separate from the current growth opportunity in newer injectable formulations.
Current litigation risk should be evaluated product by product:
| Product category | Litigation exposure | Commercial implication |
|---|---|---|
| Oral generic risperidone | Low primary-patent risk; routine product and manufacturing disputes possible | Continued price erosion |
| Risperdal Consta | Legacy formulation and equivalence issues | Mature franchise with limited pricing power |
| Perseris | Formulation and delivery patents | Potential delay to direct injectable copies |
| Uzedy | Delivery platform, formulation, and dosing patents | Potentially meaningful protection during early commercial years |
| Rykindo | Product-specific formulation and regulatory disputes | Competitive entry depends on market and approval pathway |
No single risperidone patent blocks all competing long-acting injections. The key question is whether a challenger can design around the protected delivery system while meeting FDA requirements.
How does risperidone compare with paliperidone?
Paliperidone is the active metabolite of risperidone and is marketed by Janssen as Invega and Invega Sustenna, Trinza, and Hafyera. Paliperidone has a stronger established long-acting injectable franchise, particularly in the United States.
| Factor | Risperidone | Paliperidone |
|---|---|---|
| Oral generic availability | Extensive | Extensive |
| Major long-acting products | Consta, Perseris, Rykindo, Uzedy | Invega Sustenna, Trinza, Hafyera |
| Dosing intervals | Two weeks to two months | Monthly to six months, depending on product |
| Branded franchise strength | Fragmented | More concentrated and established |
| Generic injectable threat | Emerging | Increasing as patents expire |
| Commercial growth driver | New delivery technologies | Longer intervals and established provider use |
Risperidone has greater formulation fragmentation. Paliperidone has stronger incumbent brand recognition but faces substantial long-term exposure from generic and alternative long-acting products.
Which companies are challenging the risperidone market?
The competitive landscape includes originators, specialty pharmaceutical companies, technology licensors, and generic manufacturers.
Teva Pharmaceuticals
Teva commercializes Uzedy in the United States under its relationship with MedinCell. Teva's established psychiatric sales infrastructure and payer relationships support launch execution.
MedinCell
MedinCell supplies the BEPO technology underlying Uzedy and receives economics tied to product commercialization. Its strategic value is the delivery platform rather than risperidone ownership alone.
Indivior
Indivior commercializes Perseris and has experience in specialty medicines, depot formulations, and behavioral-health markets. Its challenge is expanding adoption against Teva's newer product and established Consta use.
Janssen
Janssen developed Risperdal and Risperdal Consta. The company's broader paliperidone franchise remains commercially relevant because it competes directly for patients who might otherwise receive risperidone injections.
Luye Pharma
Luye developed and commercializes Rykindo. Its competitive position is strongest where it can use pricing, supply, and regional market access to gain share.
Generic manufacturers
Generic companies compete in oral risperidone and may eventually target depot formulations. The leading barriers are formulation development, clinical evidence, manufacturing scale, and regulatory classification.
What revenue exposure does risperidone create for manufacturers?
Risperidone revenue exposure differs sharply by product type.
| Revenue source | Margin profile | Main exposure |
|---|---|---|
| Oral generic tablets | Low | Rapid price erosion and pharmacy substitution |
| Oral solution and ODT | Low to moderate | Limited differentiation and manufacturing competition |
| Legacy depot injection | Moderate to high | Provider switching and formulary pressure |
| Monthly subcutaneous injection | High potential | Payer access, injection economics, patent challenges |
| Two-month injectable | High potential | Adoption, reimbursement, and adherence claims |
For a branded injectable, annual revenue depends more on treated patient count and net price than on prescription volume alone. A product with 50,000 treated patients and annual net revenue of $10,000 to $15,000 per patient could generate $500 million to $750 million. Actual net revenue varies by discounts, government rebates, channel mix, dosing, and persistence.
A practical revenue model is:
Revenue = treated patients x injections per year x net price per injection x persistence rate
The most important variables are:
- Conversion from oral therapy.
- Continuation after the first injection.
- Medicaid and Medicare coverage.
- Administration fees.
- Hospital and community mental-health purchasing.
- Net price after rebates.
- Dosing interval.
- Rehospitalization reduction evidence.
What generic launch scenarios exist for risperidone?
Scenario 1: Oral generic continuation
This is the baseline scenario. Multiple manufacturers maintain oral supply, prices decline gradually, and branded oral Risperdal remains commercially marginal.
Scenario 2: First competing monthly injectable
A first direct competitor to a branded monthly product could enter with a meaningful discount, but approval and manufacturing complexity would limit the number of immediate entrants. Initial launch would likely target institutional systems and high-volume psychiatric clinics.
Scenario 3: Alternative depot technology
A developer could avoid direct patent conflict by using a different polymer, particle system, or administration route. This pathway may require a 505(b)(2) strategy or clinical bridging rather than a conventional ANDA.
Scenario 4: Authorized generic or settlement launch
A branded manufacturer could license or authorize a generic competitor. Such an agreement could preserve part of the injectable market while controlling the timing and economics of entry.
What manufacturing and intellectual-property barriers exist?
The primary manufacturing barriers are technical rather than chemical. Risperidone API is widely available, but long-acting products require specialized processes and controls.
Key barriers include:
- Controlled particle or microsphere size.
- Uniform drug loading.
- Predictable in vivo release.
- Sterile filling.
- Suspension stability.
- Low injection volume.
- Consistent syringeability.
- Long-term storage stability.
- Scale-up without changing pharmacokinetics.
- Validation of release testing.
A formulation can be clinically effective yet commercially impractical if it requires large injection volumes, frequent administration, refrigerated distribution, or complex reconstitution.
Geographic protection is also fragmented. U.S. patents may expire on different dates from European, Japanese, Chinese, and other national rights. Regulatory exclusivity, patent term adjustments, supplementary protection certificates, and local formulation claims can change launch timing by jurisdiction.
What is the likely geographic market outlook?
The United States is the most valuable market for branded long-acting risperidone products because of higher net prices, specialist infrastructure, and established reimbursement for depot antipsychotics. Europe has significant long-acting use but generally lower net pricing and stronger health-technology assessment constraints.
Japan and South Korea have established psychiatric treatment markets but differ in dosing practices and reimbursement. China and other emerging markets offer volume growth but lower prices and stronger local competition.
| Region | Outlook |
|---|---|
| United States | Highest branded injectable value; strongest launch economics |
| Western Europe | Meaningful volume; lower net prices and centralized reimbursement |
| Japan | Established antipsychotic market; local regulatory and pricing requirements |
| China | Volume opportunity; price pressure and domestic competition |
| Latin America | Generic-led market with selective injectable growth |
| Middle East and Africa | Smaller base; institutional and public-sector opportunities |
How strong is the risperidone patent estate?
The risperidone patent estate is weak for the active ingredient and oral products but stronger for selected injectable delivery systems. Patent strength should be assessed at the product level.
| Estate component | Relative strength |
|---|---|
| Risperidone molecule | Very low |
| Standard oral tablets | Low |
| Oral solution and ODT | Low to moderate |
| Risperidone microspheres | Moderate |
| Monthly subcutaneous delivery | Moderate to strong, depending on claim scope |
| Two-month dosing technology | Moderate to strong |
| Manufacturing know-how | Strong practical barrier but difficult to enforce independently |
| Method-of-use claims | Variable and often narrower |
The highest-value protection is likely to come from overlapping formulation, delivery, dosing, and process claims. A single patent expiration should not be treated as the end of all protection for a long-acting product.
Key Takeaways
- Risperidone is a mature oral generic market with limited pricing power.
- Commercial growth is concentrated in long-acting injectable products.
- Uzedy has the strongest near-term growth profile because of monthly and two-month dosing.
- Perseris, Rykindo, and Risperdal Consta remain relevant but face differentiated competitive pressure.
- The original risperidone molecule is no longer a meaningful exclusivity barrier.
- Formulation, depot, delivery-platform, and manufacturing patents determine injectable launch risk.
- Biosimilar competition is irrelevant because risperidone is a small-molecule drug.
- Base-case global risperidone-related sales could rise from approximately $1.0 billion-$1.4 billion in 2024 to $1.2 billion-$1.75 billion by 2028.
- Oral revenue is expected to decline while injectable revenue expands.
- The largest commercial risks are payer rejection, slow conversion from oral therapy, manufacturing complexity, and generic injectable entry.
FAQs
What is the most valuable risperidone formulation?
Long-acting injectable risperidone is the most valuable formulation on a per-patient basis. Oral generic risperidone has far greater volume but substantially lower revenue per treatment year.
Is Uzedy a generic version of Risperdal Consta?
No. Uzedy is a separately developed extended-release risperidone product using subcutaneous administration and MedinCell's BEPO delivery technology. It is not a conventional generic copy of Risperdal Consta.
Can a generic company launch risperidone injections before all patents expire?
Potentially. A company could challenge patents under Paragraph IV, design around asserted claims, license the technology, or launch after a settlement date. FDA approval and commercial launch timing are separate questions.
Does risperidone have biosimilar risk?
No. Biosimilars apply to biological products. Risperidone is a small-molecule drug and faces generic-drug and reformulation competition instead.
Which risperidone product has the longest dosing interval?
Uzedy is administered monthly or every two months, depending on the dose. Risperdal Consta is administered every two weeks, while Perseris and Rykindo use monthly schedules.
References
- U.S. Food and Drug Administration. (2023). FDA approves Uzedy for schizophrenia. https://www.fda.gov
- U.S. Food and Drug Administration. (2018). FDA approves Perseris for the treatment of schizophrenia in adults. https://www.fda.gov
- MedinCell. (2023). Teva and MedinCell announce FDA approval of UZEDY. https://www.medincell.com
- U.S. Food and Drug Administration. (2024). Risperidone prescribing information. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2024). Hatch-Waxman amendments and generic drug patent certification. https://www.fda.gov
More… ↓
