Share This Page
Drug Sales Trends for KARIVA
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for KARIVA (2021)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
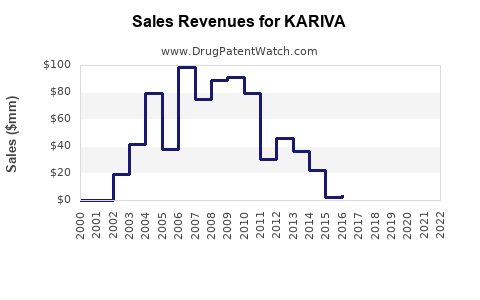
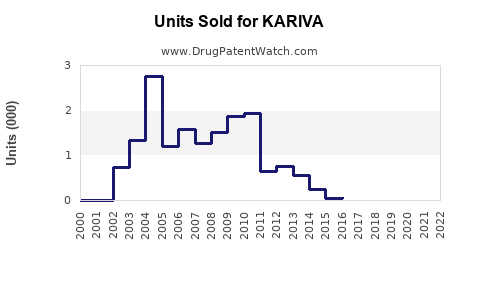
Annual Sales Revenues and Units Sold for KARIVA
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| KARIVA | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| KARIVA | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| KARIVA | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| KARIVA | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
KARIVA Market Analysis, Sales Outlook, Competition, and Patent Risk
Kariva is a legacy combined oral contraceptive containing desogestrel and ethinyl estradiol. Its commercial opportunity is primarily a low-margin generic and authorized-generic market rather than a branded-growth market. Kariva has no meaningful remaining regulatory exclusivity, faces multiple equivalent products, and has limited publicly disclosed product-level sales data. A reasonable U.S. manufacturer-revenue range is approximately $4 million to $75 million annually, with a base-case estimate near $20 million to $25 million under explicit volume and net-price assumptions.
What is Kariva and how is it positioned in the contraceptive market?
Kariva is a 28-day oral contraceptive formulation containing:
| Attribute | Kariva |
|---|---|
| Active ingredients | Desogestrel and ethinyl estradiol |
| Hormone schedule | 21 tablets with desogestrel 0.15 mg and ethinyl estradiol 0.02 mg, followed by low-dose ethinyl estradiol tablets and inactive tablets |
| Therapeutic category | Combined hormonal contraceptive |
| Route | Oral |
| U.S. regulatory status | Prescription drug |
| Reference product | Mircette-type formulation |
| Primary substitutes | Generic desogestrel/ethinyl estradiol products, Apri, Reclipsen, Azurette, Velivet and other combined oral contraceptives |
| Main commercial channel | Retail pharmacy and pharmacy benefit plans |
The product’s differentiation comes from its extended low-estrogen transition at the end of the cycle, not from a novel active ingredient. The formulation is clinically familiar but commercially exposed to substitution because physicians, pharmacists and payers can select lower-cost generic equivalents.
The FDA labeling identifies Kariva for the prevention of pregnancy in women who elect to use oral contraceptives. The labeling also includes class warnings for thromboembolic events, cardiovascular risk, smoking-related complications, hypertension and selected hepatic and reproductive conditions (FDA, 2023).
How large is the U.S. market for Kariva?
Kariva-specific prescription and revenue data are not generally disclosed by the manufacturer or the FDA. Public market sources typically aggregate contraceptive products by active ingredient, dosage form, manufacturer or therapeutic class.
The relevant market is the desogestrel/ethinyl estradiol segment rather than the entire U.S. contraceptive market. Competition includes:
- Desogestrel/ethinyl estradiol 0.15 mg/0.02 mg products.
- Desogestrel/ethinyl estradiol products paired with low-dose ethinyl estradiol tablets.
- Levonorgestrel/ethinyl estradiol products.
- Norgestimate/ethinyl estradiol products.
- Drospirenone/ethinyl estradiol products.
- Progestin-only pills, long-acting reversible contraceptives and emergency contraceptive products.
The market has high prescription volume but low unit economics. Retail prices can vary substantially by payer, pharmacy, manufacturer, rebate structure and whether the product is dispensed as a generic equivalent or under a branded label.
What is the estimated market size for Kariva?
A scenario-based estimate is more reliable than a single point estimate because product-level sales are not publicly reported.
| Scenario | Annual prescriptions | Net manufacturer revenue per prescription | Estimated annual revenue |
|---|---|---|---|
| Low | 500,000 | $8 | $4 million |
| Base | 1.5 million | $15 | $22.5 million |
| High | 3 million | $25 | $75 million |
These figures represent an analytical market model, not reported Kariva sales. They exclude manufacturer rebates, wholesaler deductions, pharmacy margins, government discounts and patient out-of-pocket payments. A branded product sold without preferred formulary placement would generally have a higher list price but may produce lower net revenue after rebates and reduced prescription volume.
What are the sales projections for Kariva?
Kariva is unlikely to produce strong organic growth without a commercial change such as a new manufacturer, improved payer access, a supply disruption affecting competitors or a targeted distribution strategy.
Base-case five-year projection
The following projection assumes a stable U.S. product market, continued generic substitution and modest prescription erosion.
| Year | Estimated prescriptions | Net revenue per prescription | Estimated net revenue |
|---|---|---|---|
| Year 1 | 1.50 million | $15.00 | $22.5 million |
| Year 2 | 1.43 million | $15.00 | $21.4 million |
| Year 3 | 1.36 million | $15.00 | $20.4 million |
| Year 4 | 1.29 million | $15.00 | $19.4 million |
| Year 5 | 1.23 million | $15.00 | $18.4 million |
This model assumes prescription erosion of approximately 5% annually and a flat net price. If generic competition drives a 3% annual net-price decline, Year 5 revenue would fall closer to $16 million.
Upside case
The upside case requires a product owner to secure:
- National retail pharmacy distribution.
- Favorable formulary placement.
- Consistent inventory availability.
- Competitive acquisition cost.
- A stable authorized-generic or branded-generic position.
- Prescriber awareness of the formulation’s low-estrogen transition schedule.
Under those conditions, annual prescriptions could reach 2.5 million to 3 million, producing approximately $40 million to $75 million in manufacturer revenue depending on net price.
Downside case
The downside case reflects continued substitution, limited distribution and payer pressure. Annual prescriptions could fall below 500,000, reducing annual manufacturer revenue to below $5 million at generic net prices.
The largest commercial risk is not abrupt patent loss. It is gradual volume displacement by interchangeable products and payer-driven product selection.
What is the Orange Book status of Kariva?
Kariva does not have a commercially meaningful remaining period of new-drug exclusivity. The product is based on an older combined oral contraceptive formulation, and equivalent products have been marketed for years.
The Orange Book framework distinguishes between:
- New-drug exclusivity.
- Listed patents.
- Approved drug applications.
- Therapeutic-equivalence ratings for generic products.
For Kariva, the commercial question is therapeutic equivalence and supply, not the preservation of an exclusivity period. The product’s value is therefore dependent on manufacturing cost, channel access, inventory reliability and payer contracting rather than a regulatory barrier.
No active patent-based exclusivity is identified as the principal commercial constraint for Kariva. Any current Orange Book patent listing would require review against the specific NDA and formulation records because product names, NDA ownership and marketed status can change over time (FDA, 2024a).
When does Kariva lose exclusivity?
Kariva’s meaningful exclusivity period has already expired. The active ingredients, desogestrel and ethinyl estradiol, are established contraceptive agents with long commercial histories.
The product has limited protection from:
- Active-ingredient patents.
- New chemical entity exclusivity.
- Commercial-scale formulation patents.
- Method-of-use patents with practical blocking power.
- Pediatric exclusivity.
- Orphan-drug exclusivity.
Any remaining intellectual-property value would more likely relate to manufacturing know-how, supply contracts, packaging, trademarks or product-specific regulatory documentation. Those rights do not prevent a manufacturer from selling an approved therapeutically equivalent product.
What patents and formulation rights protect Kariva?
Kariva’s commercial protection is weak compared with newer drugs that rely on active composition, delivery-system or formulation patents.
Active ingredient protection
Desogestrel and ethinyl estradiol are established molecules. Their composition-of-matter patent terms have expired. A competitor does not need to license the active ingredients merely to manufacture a therapeutically equivalent product.
Formulation protection
The low-dose estrogen transition schedule may have had historical formulation or method-of-use significance. That protection is unlikely to block current generic competition because equivalent or therapeutically comparable products have been available for an extended period.
Manufacturing protection
Manufacturing know-how can still affect:
- Tablet uniformity.
- Hormone content consistency.
- Stability across the 28-day pack.
- Packaging and labeling.
- Batch release testing.
- Supply reliability.
These factors can create operational advantages but are not equivalent to a blocking patent estate.
Are there Paragraph IV challenges to Kariva?
Paragraph IV litigation is unlikely to be a material current risk for Kariva. Paragraph IV certifications are most important when a generic applicant challenges an unexpired patent listed for a reference drug. Kariva is a mature product with broad generic availability and no apparent commercially meaningful patent barrier.
The more relevant legal risks are:
- Product liability claims involving combined hormonal contraceptive risks.
- Manufacturing or quality failures.
- Labeling disputes.
- Trademark and trade-dress disputes.
- Distribution or supply agreements.
- Regulatory action involving current good manufacturing practices.
A new entrant could still file an ANDA if it meets FDA requirements, but the application would compete primarily on cost, supply and channel access rather than by resolving a major patent dispute.
What is the FDA regulatory status of Kariva?
Kariva is an FDA-approved prescription combined oral contraceptive. Its labeling covers pregnancy prevention and includes contraindications and warnings applicable to estrogen-containing contraceptives.
Key regulatory considerations include:
| Regulatory issue | Commercial effect |
|---|---|
| Therapeutic equivalence | Determines substitution at the pharmacy |
| Label consistency | Limits promotional differentiation |
| Manufacturing compliance | Can affect product availability |
| Stability data | Important for shelf life and inventory |
| Packaging configuration | Matters because the product has a scheduled tablet sequence |
| Pharmacovigilance | Important for thromboembolic and cardiovascular events |
| Postmarket changes | May require FDA supplements or updated labeling |
For a mature generic product, FDA compliance and product continuity generally have greater revenue impact than clinical development.
Which companies compete with Kariva?
Competition occurs at both the product and therapeutic-class levels.
Direct or near-direct competitors
- Generic desogestrel/ethinyl estradiol products.
- Mircette-equivalent products.
- Azurette-type products.
- Apri and other desogestrel/ethinyl estradiol products.
- Reclipsen and related desogestrel/ethinyl estradiol products.
Indirect competitors
- Generic levonorgestrel/ethinyl estradiol products.
- Norgestimate/ethinyl estradiol products.
- Drospirenone/ethinyl estradiol products.
- Progestin-only oral contraceptives.
- Intrauterine systems.
- Subdermal implants.
- Injectable contraceptives.
- Transdermal patches and vaginal rings.
Long-acting contraceptives are important competitive substitutes because they reduce the need for monthly prescription refills. Oral contraceptives retain advantages in patient familiarity, reversibility, availability and low acquisition cost, but those benefits do not create durable product-level pricing power.
How strong is the patent estate for Kariva?
Kariva’s patent estate is weak from a market-exclusivity perspective.
| Protection category | Estimated strength |
|---|---|
| Active ingredient patents | None with practical commercial relevance |
| New chemical entity exclusivity | Expired |
| Formulation patents | Limited or expired blocking value |
| Method-of-use patents | Limited blocking value |
| Manufacturing know-how | Moderate operational value |
| Trademark | Potential brand-recognition value |
| Regulatory exclusivity | None of material current duration |
| Supply-chain advantage | Potentially meaningful but reversible |
The strongest defensible assets are likely operational: reliable manufacturing, qualified suppliers, pharmacy access and inventory management. These assets can support share but do not prevent generic entry.
What generic launch risks exist for Kariva?
Generic-launch risk is high in the sense that the product is exposed to continuing competition. The risk is not a single future launch event. It is persistent substitution by existing and new equivalent products.
A new manufacturer would face:
- Low switching costs for pharmacies and payers.
- Limited physician dependence on a specific brand.
- Price compression after additional entrants.
- Potential shortages if specialized packaging or hormone-supply inputs are constrained.
- Regulatory costs for abbreviated applications, manufacturing validation and postmarket compliance.
- Limited ability to differentiate through clinical claims.
A successful launch would require a lower cost of goods, dependable supply and a distribution partner with access to retail and managed-care channels.
What licensing deals could increase Kariva’s value?
Kariva is more suitable for a supply, commercialization or authorized-generic transaction than for a traditional innovation licensing deal.
Potential transaction structures include:
| Deal structure | Strategic rationale |
|---|---|
| Authorized generic agreement | Expands pharmacy access while preserving manufacturing control |
| Contract manufacturing | Converts unused production capacity into recurring revenue |
| Regional commercialization license | Uses an established contraceptive sales force |
| Private-label supply agreement | Increases volume through pharmacy or distributor brands |
| Portfolio acquisition | Combines Kariva with other oral contraceptive products |
| Co-promotion agreement | Adds access to reproductive-health prescribers |
Upfront payments would likely be limited unless the transaction includes a broader contraceptive portfolio, regulatory rights, manufacturing capacity or established payer contracts.
What geographic markets are relevant to Kariva?
The United States is the clearest market for Kariva because the product has an established FDA regulatory history and an existing prescription channel.
International expansion would require country-specific review of:
- Marketing authorization.
- Trademark availability.
- Local contraceptive labeling.
- Pharmacovigilance obligations.
- Reimbursement status.
- Import and manufacturing rules.
- Local reference-product requirements.
The product’s intellectual-property position would not normally prevent international generic competition. Commercial attractiveness would depend on population, oral contraceptive use, reimbursement and local price controls.
What is the commercial outlook for Kariva?
Kariva is a mature, low-barrier contraceptive product with limited standalone growth potential. Its value is strongest in a portfolio that already has:
- Oral contraceptive distribution.
- Retail pharmacy contracts.
- Generic manufacturing capacity.
- Regulatory infrastructure.
- Existing relationships with payers and wholesalers.
As a standalone brand, Kariva is unlikely to justify substantial premium pricing. As a reliable generic or authorized-generic product, it can generate recurring revenue if the owner maintains supply and achieves broad pharmacy coverage.
Key Takeaways
- Kariva is a mature desogestrel/ethinyl estradiol oral contraceptive.
- Its meaningful regulatory and patent exclusivity has expired.
- Product-level sales are not publicly reported in a reliable, standardized format.
- A scenario-based U.S. revenue range is approximately $4 million to $75 million annually.
- A base-case projection is approximately $22.5 million in Year 1, declining to about $18.4 million by Year 5.
- The main risks are generic substitution, payer price pressure, supply disruption and limited differentiation.
- The strongest commercial strategy is an authorized-generic, private-label, supply or portfolio transaction.
- Patent litigation and Paragraph IV activity are unlikely to be the central commercial issues.
FAQs About Kariva Sales, Patents, and Market Competition
Is Kariva still marketed in the United States?
Kariva has an established FDA regulatory history, but branded-market availability may vary by manufacturer and distributor. Generic and equivalent desogestrel/ethinyl estradiol products are the principal commercial competitors.
What is the generic name for Kariva?
Kariva contains desogestrel and ethinyl estradiol, with a low-dose ethinyl estradiol transition in the 28-day regimen.
Does Kariva have biosimilar competition?
No. Kariva is a chemically synthesized small-molecule oral contraceptive, so competition occurs through generic drug applications rather than biosimilar applications.
Can a manufacturer launch a generic version of Kariva without a patent license?
A manufacturer generally can pursue an FDA-approved generic pathway if no enforceable patent or other regulatory barrier blocks the proposed product. Kariva’s commercial history indicates that generic competition is already established.
Is Kariva more valuable as a brand or as a generic?
Kariva is more valuable as part of a generic or authorized-generic contraceptive portfolio. Its limited clinical differentiation and lack of meaningful exclusivity reduce the value of a standalone branded strategy.
References
-
U.S. Food and Drug Administration. (2023). Kariva: Desogestrel and ethinyl estradiol tablets, ethinyl estradiol tablets prescribing information. DailyMed.
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (2024b). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
Centers for Disease Control and Prevention. (2024). U.S. selected practice recommendations for contraceptive use. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024c). Abbreviated new drug application process. FDA.
More… ↓
