Share This Page
Drug Sales Trends for omeprazole
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for omeprazole (2020)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
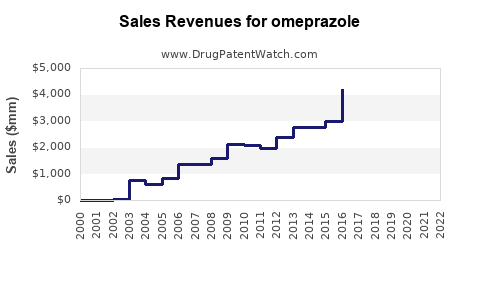
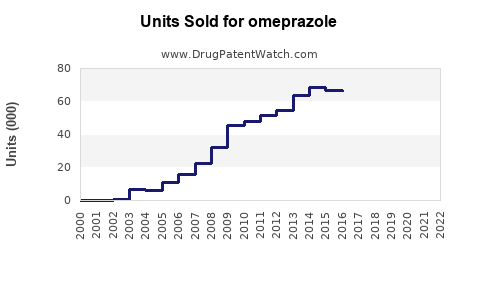
Annual Sales Revenues and Units Sold for omeprazole
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| OMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| OMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| OMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| OMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Omeprazole Market Analysis, Sales Forecast, Patent Status, and Competitive Outlook
Omeprazole is a mature, low-cost proton pump inhibitor (PPI) with broad global availability, extensive generic competition, and limited branded pricing power. The original Prilosec franchise lost U.S. market exclusivity more than two decades ago. Future value is concentrated in high-volume generic supply, over-the-counter (OTC) brands, combination products, and emerging-market distribution rather than innovative molecule-level pricing.
An analyst model places the global omeprazole market at approximately $1.0 billion to $1.5 billion in 2024 at manufacturer and retail-equivalent values, depending on whether private-label OTC sales and combination products are included. A base-case model projects low-single-digit annual growth through 2030, producing approximately $1.2 billion to $1.9 billion in aggregate market value. Unit demand should grow faster than revenue because pricing remains under pressure.
What is the current market size for omeprazole?
Omeprazole is one of the largest and most established PPIs by cumulative exposure. It is sold as a prescription drug and as an OTC product for frequent heartburn in several markets.
Public companies generally do not report omeprazole revenue as a standalone line item. Generic manufacturers report portfolio revenue, while OTC companies group omeprazole with broader gastrointestinal products. As a result, market sizing requires a bottom-up estimate based on prescription volume, OTC sales, geographic availability, and average selling prices.
| Market segment | 2024 estimated value | Growth outlook through 2030 | Commercial characteristics |
|---|---|---|---|
| U.S. prescription omeprazole | $100 million-$200 million | Declining to flat | Heavy generic substitution |
| U.S. OTC omeprazole | $250 million-$450 million | Low growth | Brand and private-label competition |
| Europe | $250 million-$400 million | Flat to low growth | National reimbursement and generic pricing |
| Asia-Pacific | $250 million-$450 million | 3%-6% annual growth | Volume-led expansion |
| Latin America, Middle East, and Africa | $150 million-$300 million | 3%-6% annual growth | Access and local manufacturing drive demand |
| Estimated global total | $1.0 billion-$1.5 billion | 1%-4% annual value growth | Volume growth offset by price erosion |
These figures are market estimates rather than reported omeprazole revenue. They exclude some hospital procurement, unbranded bulk-active pharmaceutical ingredient sales, and products in which omeprazole is not separately disclosed.
Which regions have the strongest omeprazole growth?
Asia-Pacific and other price-sensitive markets are likely to generate the highest unit growth. Demand is supported by:
- Expansion of private healthcare and retail pharmacy networks.
- Greater diagnosis and treatment of gastroesophageal reflux disease (GERD).
- Wider availability of generic delayed-release capsules and tablets.
- Local production of finished dosage forms and active pharmaceutical ingredient (API).
- Lower treatment costs compared with newer branded acid-suppression products.
North America and Western Europe remain important by value but are mature markets. Their growth is constrained by generic substitution, reimbursement controls, and the availability of competing PPIs.
What are the sales projections for omeprazole through 2030?
The following forecast uses 2024 as the base year and separates value growth from unit growth. It assumes continued generic price erosion, stable OTC demand, modest diagnosis growth, and expansion in developing markets.
| Scenario | 2024 market value | 2030 market value | Implied CAGR | Primary assumptions |
|---|---|---|---|---|
| Downside | $1.0 billion | $1.0 billion-$1.1 billion | 0%-2% | Faster price erosion and substitution by other PPIs |
| Base case | $1.25 billion | $1.45 billion-$1.65 billion | 2%-5% | Stable OTC sales and volume growth in emerging markets |
| Upside | $1.5 billion | $1.9 billion-$2.2 billion | 4%-7% | Stronger global diagnosis, OTC expansion, and combination-product growth |
How will omeprazole unit sales compare with revenue growth?
Unit demand should remain positive in most regions, but revenue growth will be weaker. A reasonable base-case assumption is:
| Metric | 2024-2030 base-case outlook |
|---|---|
| Global units | 2%-4% CAGR |
| Global market value | 2%-5% CAGR |
| Average realized price | Flat to down 1%-3% annually |
| OTC share of value | Stable to modestly increasing |
| Prescription generic share | Stable or increasing |
| Branded prescription share | Minimal |
The principal risk to revenue is not clinical obsolescence. It is commoditization. Manufacturers that compete only on standard 20-milligram delayed-release capsules or tablets face limited pricing power.
Who are the leading omeprazole manufacturers and competitors?
The supply base includes multinational generic companies, regional manufacturers, contract development and manufacturing organizations, and OTC brand owners. Major generic participants in the broader omeprazole market include Viatris, Teva Pharmaceutical Industries, Sandoz, Dr. Reddy’s Laboratories, Cipla, Sun Pharmaceutical Industries, Zydus Lifesciences, Torrent Pharmaceuticals, and numerous regional suppliers.
The original branded product, Prilosec, was developed by AstraZeneca. AstraZeneca also developed Nexium, the esomeprazole product that became the company’s principal successor PPI franchise. Omeprazole is the racemic compound, while esomeprazole is its S-isomer.
| Drug | Active ingredient | Typical commercial position | Relative differentiation |
|---|---|---|---|
| Prilosec and generic products | Omeprazole | Mature prescription and OTC product | Low |
| Nexium and generic products | Esomeprazole | Higher-value successor PPI | Moderate brand and formulation differentiation |
| Protonix and generic products | Pantoprazole | Strong prescription and hospital presence | Moderate |
| Prevacid and generic products | Lansoprazole | Established generic and OTC presence | Low to moderate |
| AcipHex and generic products | Rabeprazole | Smaller PPI segment | Moderate |
| Voquezna | Vonoprazan | Potassium-competitive acid blocker | Higher clinical and commercial differentiation |
Vonoprazan, marketed in the U.S. as Voquezna, is the most important newer mechanism in the acid-suppression market. It may capture patients requiring rapid or sustained acid control, but omeprazole remains advantaged by price, familiarity, global registration history, and broad generic access. FDA approved vonoprazan-containing products for erosive GERD, heartburn associated with non-erosive GERD, and Helicobacter pylori eradication regimens in 2023 and 2024. [1]
When did omeprazole lose exclusivity?
Omeprazole lost meaningful U.S. molecule-level exclusivity in the early 2000s. FDA approved Prilosec in 1989, and the original composition-of-matter patent expired around 2001. Generic competition followed through abbreviated new drug applications (ANDAs), although litigation and formulation patents affected the timing and scope of individual launches. [2]
| Milestone | Approximate date | Commercial effect |
|---|---|---|
| FDA approval of Prilosec | 1989 | Launch of prescription omeprazole |
| Original U.S. compound patent expiration | 2001 | End of primary molecule protection |
| Early generic litigation and launches | 2001-2003 | Rapid price and share pressure |
| OTC omeprazole approval and launch | 2003 | Expansion into self-care heartburn |
| Current market | 2024-2025 | Broad generic and private-label supply |
The OTC launch materially extended the commercial life of the active ingredient but did not restore prescription-style exclusivity. The market now operates as a branded and private-label consumer-health category alongside a low-margin generic prescription category.
What patents protect omeprazole products today?
The original active-ingredient patent estate is expired. Current commercial protection, where it exists, is more likely to involve formulation design, dosage form, manufacturing process, combination therapy, packaging, or brand assets.
What formulations are protected by omeprazole patents?
Omeprazole is acid-labile. Commercial products therefore require delayed release, usually through enteric coating, enteric-coated pellets, granules, capsules, tablets, or oral-suspension systems. Formulation work may address:
- Protection of omeprazole from gastric acid.
- Stability during storage.
- Particle size and pellet architecture.
- Alkaline or buffering agents.
- Multiparticulate capsules.
- Pediatric liquid or suspension delivery.
- Co-administration with antibiotics for H. pylori treatment.
These technical features can support patent claims, but they generally do not create a durable barrier against all generic alternatives. Generic companies can design around individual formulation claims or rely on different coating and excipient systems.
What is the Orange Book status of omeprazole?
FDA’s Orange Book includes multiple prescription omeprazole products, including delayed-release capsules and oral-suspension dosage forms. The existence of numerous approved ANDA products demonstrates that the core product is no longer protected by a blocking patent. [3]
Orange Book-listed patents can still affect particular branded or formulation-specific products. Commercial teams should distinguish between:
- The absence of a molecule-level barrier.
- Patents listed against a specific reference product.
- Patent disputes involving a particular generic applicant.
- OTC trade dress, labeling, or brand rights, which are separate from Orange Book patent rights.
A current Orange Book review is required for product-specific litigation or launch analysis because listings and regulatory statuses can change.
Are there Paragraph IV challenges involving omeprazole?
Paragraph IV litigation was commercially important during the first generic wave after Prilosec. Generic applicants challenged listed patents by asserting that patents were invalid, unenforceable, or not infringed under the Hatch-Waxman framework. [4]
The strategic importance of those disputes has largely passed. Omeprazole now has multiple approved generic suppliers, and the principal market risk is price competition rather than a new Paragraph IV event against the original product. Paragraph IV activity may still arise for reformulated products, combination products, or newer omeprazole delivery systems.
A generic applicant making a Paragraph IV certification can trigger patent litigation within the statutory period and may receive a 180-day first-filer exclusivity period if the legal and regulatory requirements are satisfied. That mechanism matters most for products with limited supplier competition. Standard omeprazole capsules are already highly competitive.
How strong is the omeprazole patent estate?
The molecule-level patent estate is weak because the original composition patent is expired. The remaining estate is best characterized as fragmented and product-specific.
| Patent layer | Current strength | Commercial relevance |
|---|---|---|
| Original compound patent | Expired | No meaningful barrier |
| Basic delayed-release formulation | Generally weak to moderate | Design-around risk is high |
| Specific multiparticulate systems | Moderate in narrow claims | Can protect a product configuration |
| Pediatric or liquid formulations | Moderate | Relevant in targeted markets |
| Combination regimens | Moderate to strong for specific claims | Depends on drug combination and jurisdiction |
| Manufacturing processes | Narrow to moderate | Can affect cost and supply, not necessarily market entry |
| Trademark and OTC brand rights | Strong for recognized brands | Protects marketing, not generic substitution |
The commercial value of a new omeprazole patent would depend on whether it protects a clinically meaningful benefit, such as improved stability, fewer doses, pediatric usability, or a differentiated combination regimen. A patent covering only a routine enteric-coating variation would face substantial invalidity and design-around risk.
What generic entry risks exist for omeprazole?
Generic entry risk is already realized rather than prospective. The relevant question is whether additional suppliers can further reduce price or disrupt supply.
Key risks include:
- Wholesale price erosion from new ANDA approvals.
- Loss of preferred formulary position.
- Retail substitution into private-label OTC products.
- API concentration in a limited number of manufacturing regions.
- Recalls caused by nitrosamine or other impurity concerns.
- Shortages affecting low-margin suppliers.
- Regulatory action against facilities that fail current good manufacturing practice requirements.
- Substitution by pantoprazole, esomeprazole, lansoprazole, or vonoprazan.
Manufacturing barriers are operational rather than patent-based. Omeprazole requires controlled formulation and coating processes because of its acid sensitivity. The technical barrier is manageable for established generic manufacturers, but quality failures, impurity controls, and supply-chain interruptions can remove individual suppliers from the market.
What FDA regulatory status does omeprazole have?
Omeprazole is an FDA-approved prescription and OTC active ingredient. Prescription products include delayed-release capsules, delayed-release tablets, and oral-suspension formulations. The OTC indication is short-term treatment of frequent heartburn, generally defined in labeling as heartburn occurring two or more days per week. [5]
FDA approval does not imply that every manufacturer has identical labeling, dosage forms, or indications. Prescription and OTC products remain subject to different labeling, packaging, and consumer-use requirements.
Omeprazole is also used in H. pylori eradication regimens with antibiotics. Combination products may have different regulatory and patent profiles from single-ingredient omeprazole.
What licensing deals affect omeprazole sales?
The main historic licensing value arose from the original AstraZeneca discovery, development, and commercialization program and from regional rights associated with Prilosec and related products. Current omeprazole revenue is distributed across generic supply agreements, private-label OTC contracts, pharmacy purchasing groups, and regional marketing arrangements.
No single active license is likely to control the global omeprazole market. Commercial leverage is instead held by:
- Manufacturers with reliable API access.
- Companies with approved ANDAs in major markets.
- OTC brands with strong pharmacy placement.
- Suppliers able to maintain low-cost, compliant production.
- Distributors with regional regulatory registrations.
Licensing opportunities are more attractive for differentiated delivery systems, combination therapies, and emerging-market registrations than for standard omeprazole capsules.
What litigation affects omeprazole?
Historic litigation centered on AstraZeneca’s Prilosec patents and generic challenges under Hatch-Waxman. Current litigation exposure is more likely to involve:
- Product liability.
- Manufacturing quality and recalls.
- Labeling and consumer-protection claims.
- Trademark disputes involving OTC packaging.
- Patents covering combination regimens or specialized formulations.
- Contract disputes between suppliers and private-label customers.
The absence of a meaningful molecule-level patent barrier reduces the probability that a single patent case will remove generic omeprazole from the market.
How does omeprazole compare with esomeprazole and pantoprazole?
Omeprazole has the lowest strategic differentiation among the major mature PPIs, but it retains the broadest cost and availability advantages.
| Factor | Omeprazole | Esomeprazole | Pantoprazole |
|---|---|---|---|
| Patent maturity | Fully mature | Mature, with later-originating product history | Mature |
| Generic competition | Very high | High | High |
| OTC presence | Strong | Strong | Limited in some markets |
| Price level | Low | Low to moderate | Low to moderate |
| Hospital use | Established | Established | Often strong |
| Growth potential | Emerging-market volume | Brand and formulation niches | Institutional and prescription niches |
| Patent strength | Weak at molecule level | Weak at molecule level | Weak at molecule level |
Omeprazole is most exposed to substitution by esomeprazole where prescribers or consumers perceive efficacy or dosing advantages. Its strongest defense is price and established clinical familiarity.
What is the revenue exposure for manufacturers?
For diversified generic companies, omeprazole is unlikely to be a major standalone revenue driver. It is typically part of a gastrointestinal portfolio. Revenue exposure is highest for:
- Small regional manufacturers with concentrated PPI portfolios.
- OTC companies dependent on heartburn products.
- Contract manufacturers supplying private-label pharmacies.
- API producers with limited customer diversification.
- Companies holding registrations in markets with few approved suppliers.
A large manufacturer can tolerate omeprazole price erosion if it has scale, integrated API production, and a broad product portfolio. Smaller suppliers may experience material margin compression when a new competitor receives approval.
Key Takeaways
- Omeprazole is a mature, globally established PPI with extensive generic and OTC competition.
- Estimated 2024 global market value is approximately $1.0 billion to $1.5 billion, depending on market definition.
- Base-case 2030 value is approximately $1.45 billion to $1.65 billion, with unit growth exceeding revenue growth.
- The original omeprazole compound patent expired around 2001.
- Current patent value is concentrated in narrow formulations, delivery systems, combinations, manufacturing processes, and brands.
- Paragraph IV risk is historically significant but commercially limited for standard omeprazole products today.
- Asia-Pacific and other emerging markets offer the strongest volume growth.
- Vonoprazan is the main newer competitive threat, while esomeprazole, pantoprazole, and lansoprazole remain established substitutes.
- The main commercial risks are price erosion, supply interruptions, quality enforcement, and OTC private-label competition.
- Attractive investment opportunities are more likely in differentiated formulations, combination therapies, reliable API supply, and regional distribution than in standard omeprazole products.
FAQs About Omeprazole Market Economics and Exclusivity
Is omeprazole still profitable for generic manufacturers?
Yes, but profitability depends on manufacturing scale, API integration, procurement contracts, and regional competition. Standard capsules generally generate low margins, while specialized formulations and private-label contracts can produce better economics.
Can a new company launch generic omeprazole without facing major patent barriers?
In most markets, the core molecule is no longer patent-blocked. A new entrant must still satisfy bioequivalence, formulation, manufacturing, labeling, and local registration requirements.
Does OTC omeprazole have stronger exclusivity than prescription omeprazole?
No. OTC brands can have stronger consumer recognition and retail placement, but the active ingredient remains available to private-label manufacturers. Brand, trade dress, and advertising rights do not provide molecule-level exclusivity.
Is omeprazole demand sensitive to generic price changes?
Demand is relatively price-insensitive at the category level because treatment volume is driven by diagnosis and recurring use. Manufacturer revenue is highly price-sensitive because pharmacies, payers, and distributors can switch among approved suppliers.
Could vonoprazan eliminate omeprazole demand?
No. Vonoprazan may gain share in selected GERD and H. pylori treatment segments, but omeprazole’s low cost, broad availability, extensive clinical history, and OTC access support continued high-volume use.
References
-
U.S. Food and Drug Administration. (2023-2024). FDA approves vonoprazan-containing products for acid-related disorders and Helicobacter pylori infection. https://www.fda.gov/
-
AstraZeneca. (2001-2003). Annual reports and disclosures regarding Prilosec patent litigation and generic competition. AstraZeneca investor relations.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (2024). Abbreviated new drug application approvals and patent certifications under the Hatch-Waxman Act. https://www.fda.gov/
-
U.S. Food and Drug Administration. (2024). Drug labels for omeprazole delayed-release prescription and over-the-counter products. DailyMed. https://dailymed.nlm.nih.gov/
More… ↓
