Share This Page
Drug Sales Trends for metoprolol
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for metoprolol (2020)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
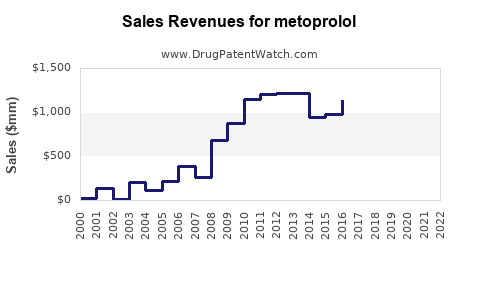
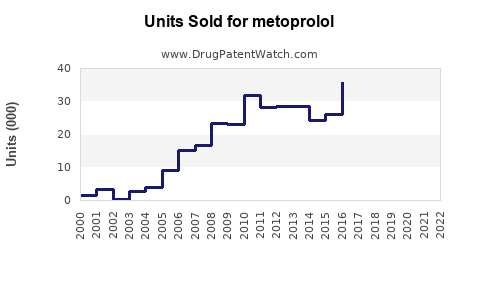
Annual Sales Revenues and Units Sold for metoprolol
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| METOPROLOL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| METOPROLOL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| METOPROLOL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| METOPROLOL | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| METOPROLOL | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| METOPROLOL | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Metoprolol Market Analysis, Sales Projections, Patent Status, and Competitive Outlook
Metoprolol is a mature, genericized beta-1 selective blocker with stable demand in hypertension, angina, heart failure, tachyarrhythmia, and post-myocardial-infarction care. The market is volume-driven rather than innovation-driven. Generic metoprolol tartrate and metoprolol succinate dominate prescriptions, while branded Toprol-XL and Lopressor have limited commercial relevance.
The global metoprolol market is likely to grow at a low single-digit rate through 2029, supported by cardiovascular disease prevalence, aging populations, and chronic treatment. Price erosion, therapeutic substitution, pharmacy concentration, and limited product differentiation will constrain revenue growth. A reasonable base-case estimate places global market value at approximately $0.8 billion to $1.1 billion in 2024, increasing to $0.9 billion to $1.3 billion by 2029.
What is the current metoprolol market position?
Metoprolol is sold primarily in two oral formulations:
| Product | Active ingredient | Main release profile | Principal uses |
|---|---|---|---|
| Lopressor | Metoprolol tartrate | Immediate release | Hypertension, angina, post-myocardial infarction |
| Toprol-XL | Metoprolol succinate | Extended release | Hypertension, angina, heart failure |
| Generic metoprolol tartrate | Metoprolol tartrate | Immediate release | Same as Lopressor |
| Generic metoprolol succinate ER | Metoprolol succinate | Extended release | Same as Toprol-XL |
Metoprolol succinate extended release has a stronger commercial position than immediate-release tartrate because once-daily dosing and heart-failure labeling support persistent use. Metoprolol tartrate remains widely prescribed because of its low cost, broad availability, and hospital familiarity.
The product competes in a large but highly commoditized cardiovascular market. Alternative beta blockers include carvedilol, bisoprolol, atenolol, nebivolol, and propranolol. ACE inhibitors, angiotensin receptor blockers, calcium-channel blockers, and guideline-directed heart-failure therapies compete for overlapping treatment decisions.
How large is the metoprolol market?
Published market estimates differ because some reports measure active pharmaceutical ingredient sales, others measure retail prescription value, and others combine metoprolol tartrate and succinate with broader beta-blocker categories. A practical commercial model is:
| Metric | 2024 estimate | 2029 base-case estimate |
|---|---|---|
| Global metoprolol market value | $0.8-$1.1 billion | $0.9-$1.3 billion |
| Base-case annual growth | - | 1%-3% |
| Generic share of volume | More than 95% in mature markets | More than 97% |
| Brand share of value | Low single digits | Low single digits or below |
| Primary growth driver | Prescription volume | Population aging and cardiovascular prevalence |
| Primary constraint | Generic price erosion | Substitution and procurement pressure |
These are analytical estimates rather than reported manufacturer sales. Public companies generally do not disclose metoprolol revenue separately because the drug is included within broader cardiovascular or established-products portfolios.
The United States remains one of the largest markets by prescription value, but emerging markets can contribute more volume. Europe has extensive generic penetration and aggressive reimbursement controls. Japan, China, India, Brazil, and other large markets have substantial demand but lower average selling prices.
What are the metoprolol sales projections through 2029?
Base-case projection
The base case assumes stable treatment guidelines, modest growth in cardiovascular disease prevalence, continued generic substitution, and annual net price erosion of approximately 2% to 4% in mature markets.
| Year | Estimated global market value | Estimated volume trend | Commercial interpretation |
|---|---|---|---|
| 2024 | $0.8-$1.1 billion | Baseline | Mature generic market |
| 2025 | $0.82-$1.13 billion | 1%-2% growth | Volume offsets price erosion |
| 2026 | $0.84-$1.17 billion | 1%-2% growth | Stable chronic use |
| 2027 | $0.86-$1.21 billion | 1%-3% growth | Emerging-market contribution |
| 2028 | $0.88-$1.25 billion | 1%-3% growth | Continued generic concentration |
| 2029 | $0.90-$1.30 billion | 1%-3% growth | Low-growth, high-volume category |
Scenario analysis
| Scenario | 2029 market value | Key assumptions |
|---|---|---|
| Downside | $0.7-$0.9 billion | Accelerated price erosion, lower reimbursement, greater substitution by carvedilol and bisoprolol |
| Base case | $0.9-$1.3 billion | Stable volume and low single-digit market growth |
| Upside | $1.3-$1.6 billion | Higher cardiovascular treatment rates, stronger emerging-market demand, limited price decline |
The market is unlikely to generate high growth from price increases. Revenue expansion depends on prescription volume, improved diagnosis and treatment of hypertension, and use in heart failure and arrhythmia management.
Which formulations are commercially strongest?
Metoprolol succinate extended release
Metoprolol succinate ER has the strongest strategic position because it supports once-daily dosing and is indicated for stable heart failure in the FDA-approved labeling. The formulation also has greater product complexity than immediate-release tablets, although the technology is well established.
Commercial advantages include:
- Once-daily administration.
- Established use in chronic cardiovascular therapy.
- Heart-failure positioning.
- Broad generic availability.
- Potential adherence advantages compared with multiple daily dosing.
The principal risk is generic substitution. The branded Toprol-XL franchise no longer controls the market through exclusivity.
Metoprolol tartrate immediate release
Metoprolol tartrate is a lower-cost, high-volume product. Hospitals and outpatient prescribers use it for blood-pressure control, rate control, angina, and post-infarction treatment. Its disadvantages include shorter duration of action and more frequent dosing.
Tartrate remains commercially durable because it is inexpensive, familiar to clinicians, and available from multiple suppliers. It is less differentiated than succinate ER and is more exposed to commodity pricing.
What is the FDA regulatory status of metoprolol?
The FDA has approved metoprolol products through conventional new-drug applications and abbreviated new-drug applications. Generic products are approved under the ANDA pathway and must demonstrate pharmaceutical equivalence and bioequivalence to the applicable reference product.
| Product | FDA regulatory position |
|---|---|
| Lopressor | Reference product for metoprolol tartrate |
| Toprol-XL | Reference product for metoprolol succinate extended release |
| Generic tartrate | ANDA-approved immediate-release products |
| Generic succinate ER | ANDA-approved extended-release products |
The FDA-approved indications differ by formulation. Toprol-XL labeling includes hypertension, angina pectoris, and stable, symptomatic heart failure of ischemic, hypertensive, or cardiomyopathic origin. Lopressor labeling includes hypertension, angina pectoris, and treatment of myocardial infarction in specified clinical settings. [1, 2]
Metoprolol is a small molecule. Biosimilar regulation does not apply. Competitive entry occurs through generic drug applications rather than the 351(k) biosimilar pathway.
What is the Orange Book status of metoprolol?
Metoprolol is a mature Orange Book product category with extensive generic competition. The principal commercial references are Lopressor and Toprol-XL. The relevant intellectual-property value is concentrated in formulation, release-control, and product-specific patents rather than in the basic metoprolol molecule.
The original composition-of-matter protection has expired. Any historical formulation or method-of-use patents associated with the branded products are not a practical barrier to routine generic supply in the United States.
A current Orange Book review should distinguish:
- Reference listed drugs.
- Approved generic equivalents.
- Any remaining listed patents.
- Pediatric exclusivity or other historical exclusivity entries.
- Product-specific labeling differences.
The commercial conclusion is clear: metoprolol does not have an active, high-value composition-of-matter exclusivity position. Generic manufacturers can compete on price, supply reliability, dosage strengths, and channel access.
When did metoprolol lose exclusivity?
Lopressor and Toprol-XL lost meaningful market exclusivity years ago. Generic metoprolol tartrate has been available for decades, and generic metoprolol succinate ER entered the U.S. market in the mid-2000s.
The exact timing varied by dosage form, formulation, patent challenge, regulatory approval, and market launch. That distinction matters because Toprol-XL extended-release technology historically created a more complex generic-entry pathway than immediate-release tartrate.
The current market is post-exclusivity. No commercially important U.S. exclusivity period is expected to protect the metoprolol molecule or the principal marketed formulations.
Are there Paragraph IV challenges involving metoprolol?
Paragraph IV litigation was commercially relevant during the initial generic-entry period for metoprolol succinate extended release. Innovator companies challenged generic filings involving the extended-release formulation and related patents, while generic applicants disputed patent validity, enforceability, or infringement.
Those disputes affected the timing of early generic entry, but they do not create a current barrier to broad generic competition. Current commercial risk is better measured by manufacturing capacity, FDA compliance, supply continuity, and contract pricing than by unresolved Orange Book patent litigation.
The likely generic-launch scenario for any new entrant is therefore:
- No need to overcome a meaningful compound patent.
- Possible formulation-specific regulatory work.
- Potential scrutiny of dissolution and release characteristics.
- Price competition after approval.
- Limited ability to sustain premium pricing.
What patent protection remains for metoprolol?
The core metoprolol estate has low residual strength. Relevant historical protection included:
- Compound patents covering metoprolol or related pharmaceutical compounds.
- Salt and formulation claims.
- Extended-release delivery systems.
- Tablet manufacturing and dissolution specifications.
- Method-of-use claims for cardiovascular conditions.
Most important patents have expired or no longer create a meaningful market barrier. Any surviving claims would need to be assessed by product, jurisdiction, claim scope, and Orange Book status. A formulation patent may have theoretical value but limited practical value if multiple generic products have already been approved and marketed.
Patent-strength assessment
| Patent category | Current strength | Commercial effect |
|---|---|---|
| Compound patent | Very low | Expired |
| Immediate-release formulation | Very low | Broad generic competition |
| Extended-release formulation | Low | Historical relevance, limited current barrier |
| Manufacturing process | Low to moderate | May affect supply, not market access |
| Method of use | Low | Possible labeling or litigation relevance |
| Device or delivery technology | Low | No major current branded platform |
What patent litigation affects metoprolol?
There is no widely recognized current litigation campaign that materially restricts U.S. metoprolol access. Historical disputes centered on generic versions of Toprol-XL and extended-release formulations.
The litigation exposure for a new entrant would be limited unless it:
- Uses a distinct release-control technology.
- Seeks an indication with active method-of-use claims.
- Relies on a formulation that overlaps with a surviving patent.
- Makes labeling claims that trigger a patent dispute.
For established generic suppliers, operational litigation risk is more likely to involve product liability, manufacturing quality, antitrust allegations, or supply contracts than core patent exclusion.
Which companies compete in the metoprolol market?
The market has many generic suppliers. Participation varies by country and product strength, but major generic and diversified pharmaceutical companies have included:
- Teva Pharmaceutical Industries.
- Sandoz.
- Viatris.
- Zydus Lifesciences.
- Dr. Reddy's Laboratories.
- Lupin.
- Sun Pharmaceutical Industries.
- Amneal Pharmaceuticals.
- Hikma Pharmaceuticals.
- Endo and legacy Par Pharmaceutical operations.
- Regional manufacturers in China, India, Europe, and Latin America.
AstraZeneca historically commercialized Toprol-XL, while Novartis historically marketed Lopressor in the United States. Brand ownership and commercialization arrangements have changed over time, and current revenue attribution should be checked against company filings.
Competition is determined by:
- FDA approval status.
- Manufacturing reliability.
- Wholesale acquisition cost.
- Pharmacy benefit manager contracts.
- Hospital purchasing arrangements.
- Ability to supply multiple strengths.
- Product quality history.
- Geographic registration.
Are licensing deals important for metoprolol?
Licensing has limited strategic importance for the basic metoprolol market. The drug is off-patent, inexpensive, and widely manufactured. Traditional licensing opportunities are more likely to involve:
- Regional commercialization rights.
- Authorized-generic arrangements.
- Contract manufacturing.
- Hospital or government supply contracts.
- Fixed-dose combinations.
- Specialty packaging or adherence programs.
The economic value of a licensing deal depends primarily on distribution access and manufacturing economics, not intellectual-property exclusivity. A licensee would have limited ability to defend a premium unless it controls a differentiated delivery system, a regulated combination product, or a supply-constrained market.
What generic entry risks exist for metoprolol?
Generic entry risk is structurally high because the market already has numerous approved suppliers. For a new manufacturer, the main risks are commercial rather than legal.
Key risks
- Wholesale price compression.
- Pharmacy substitution.
- Limited brand loyalty.
- FDA inspection or warning-letter exposure.
- Active-ingredient supply disruptions.
- Low margins at common strengths.
- Dependence on a small number of wholesalers.
- Difficulty obtaining preferred formulary placement.
- Competition from vertically integrated Indian and global manufacturers.
A new entrant can still create value through reliable supply, difficult-to-source strengths, shortage response, regional registration, and contract manufacturing. A standard tablet launch without a cost or supply advantage is unlikely to produce attractive returns.
How does metoprolol compare with competing beta blockers?
| Drug | Main commercial advantage | Main limitation |
|---|---|---|
| Metoprolol succinate ER | Once-daily dosing and heart-failure use | Generic price pressure |
| Metoprolol tartrate | Low cost and broad familiarity | Multiple daily dosing |
| Carvedilol | Strong heart-failure position and alpha-blockade | More adverse-effect and dosing considerations |
| Bisoprolol | Beta-1 selectivity and once-daily use | Smaller supply and brand infrastructure in some markets |
| Atenolol | Low cost and long market history | Less favorable contemporary positioning in some guidelines |
| Nebivolol | Beta-1 selectivity and nitric-oxide-mediated effects | Higher price in some markets |
| Propranolol | Broad neurologic and cardiovascular use | Nonselective beta blockade |
Guideline-directed heart-failure therapy has increased competition from carvedilol and metoprolol succinate. Newer therapies such as sacubitril/valsartan, SGLT2 inhibitors, mineralocorticoid receptor antagonists, and selective use of ivabradine also influence treatment economics, although they do not eliminate the role of beta blockers.
What geographic markets offer the strongest opportunity?
United States
The United States offers high prescription volume and established reimbursement but has intense generic competition. Opportunity is concentrated in supply reliability, hospital contracts, shortage periods, and specialty packaging.
Europe
Europe has broad generic use, centralized or semi-centralized procurement, and strong price controls. Volume is attractive, but margins are generally thin.
China and India
These markets offer substantial population-scale demand and manufacturing depth. Competition is intense, and local registration, pricing, and procurement policies are decisive.
Latin America
Brazil, Mexico, and other markets have persistent cardiovascular demand. Local regulatory requirements, private versus public reimbursement, and distribution partnerships affect entry economics.
Middle East and Africa
Demand is supported by hypertension and cardiovascular disease prevalence, but market access depends on tenders, import registration, local agents, and supply consistency.
What revenue exposure do pharmaceutical companies have?
Direct revenue exposure to metoprolol is generally modest for diversified pharmaceutical companies. The product is more important to generic manufacturers, contract manufacturers, wholesalers, and regional distributors than to large innovator companies.
Revenue sensitivity is driven by:
- Number of approved strengths.
- Share of the U.S. generic market.
- Average selling price.
- Hospital versus retail mix.
- Supply contracts.
- Manufacturing utilization.
- Product recalls or shortages.
An established generic supplier with 5% of a $1 billion global market would generate approximately $50 million in gross market sales before deductions, rebates, manufacturing costs, and distribution expenses. Net revenue would be lower. The same share in a highly price-competitive market can produce materially lower profitability than the headline market value suggests.
Key Takeaways
- Metoprolol is a mature, post-exclusivity generic cardiovascular market.
- Metoprolol succinate ER has stronger commercial positioning than immediate-release tartrate.
- Global market value is estimated at $0.8 billion to $1.1 billion in 2024.
- Base-case market value is projected to reach $0.9 billion to $1.3 billion by 2029.
- Volume growth should remain positive, but generic price erosion will limit revenue expansion.
- Biosimilar risk does not apply because metoprolol is a small molecule.
- The original compound and principal formulation exclusivities have expired.
- Current commercial barriers are manufacturing, supply, reimbursement, and distribution factors.
- New generic entry has high legal feasibility but uncertain economic attractiveness.
- Licensing value is concentrated in regional distribution, authorized generics, and supply agreements.
FAQs About Metoprolol Market Outlook
Is metoprolol still a profitable generic drug?
It can be profitable for efficient manufacturers with reliable supply and low production costs. Standard products face substantial price competition, so profitability depends on scale, procurement access, and manufacturing utilization.
Which metoprolol formulation has the highest commercial value?
Metoprolol succinate extended release generally has higher strategic value because of once-daily dosing and heart-failure use. Metoprolol tartrate has greater commodity-volume characteristics.
Can a company obtain new patents on metoprolol?
A company may patent a genuinely novel formulation, combination, manufacturing process, or delivery system. Such patents would not restore exclusivity over the existing metoprolol molecule.
Is metoprolol subject to FDA drug shortages?
Availability can vary by manufacturer, strength, and formulation. Shortage risk is typically linked to manufacturing interruptions, active-ingredient constraints, quality actions, or supplier concentration rather than patent restrictions.
Will cardiovascular disease trends increase metoprolol sales?
Aging populations, hypertension, coronary artery disease, and heart failure should support prescription volume. The effect on revenue will be moderated by generic substitution and continued price pressure.
References
-
U.S. Food and Drug Administration. (2023). Toprol-XL (metoprolol succinate) extended-release tablets prescribing information. FDA.
-
U.S. Food and Drug Administration. (2023). Lopressor (metoprolol tartrate) tablets prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. FDA.
-
DailyMed. (2024). Metoprolol succinate extended-release and metoprolol tartrate drug labeling. National Library of Medicine.
-
Heidenreich, P. A., Bozkurt, B., Aguilar, D., et al. (2022). 2022 AHA/ACC/HFSA guideline for the management of heart failure. Circulation, 145(18), e895-e1032.
-
Whelton, P. K., Carey, R. M., Aronow, W. S., et al. (2018). 2017 ACC/AHA guideline for the prevention, detection, evaluation, and management of high blood pressure in adults. Hypertension, 71(6), e13-e115.
More… ↓
