Share This Page
Drug Sales Trends for calcitriol
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for calcitriol (2020)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
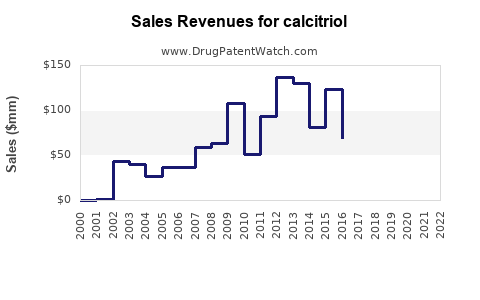
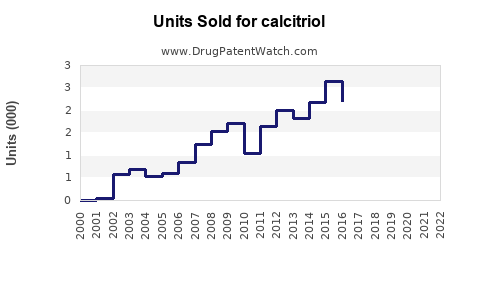
Annual Sales Revenues and Units Sold for calcitriol
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| CALCITRIOL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| CALCITRIOL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| CALCITRIOL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| CALCITRIOL | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Calcitriol Market Analysis, Sales Forecast, Patent Status, and Competitive Outlook
Calcitriol is a mature, largely generic vitamin D analog with limited branded revenue and sustained clinical demand in chronic kidney disease, hypocalcemia, hypoparathyroidism, and selected dermatology indications. The market is fragmented across oral capsules, oral solution, injectable products, and topical formulations. Growth is likely to remain modest, driven by patient volume and specialty formulations rather than price expansion.
Public sources do not report a consolidated global revenue figure for calcitriol because sales are split among generic manufacturers, hospital suppliers, regional brands, and topical products. A defensible forecast therefore requires a scenario model rather than a single market-consensus estimate.
What is the current market position of calcitriol?
Calcitriol is the active form of vitamin D3, also known as 1,25-dihydroxyvitamin D3. It acts directly on the vitamin D receptor and does not require renal activation. Its principal markets are:
| Market | Primary use | Commercial profile |
|---|---|---|
| Oral capsules and solution | Hypocalcemia, hypoparathyroidism, renal osteodystrophy | Mature generic market |
| Injectable calcitriol | Dialysis-related secondary hyperparathyroidism and hypocalcemia | Hospital and dialysis-channel product |
| Topical ointment | Plaque psoriasis in selected markets | Smaller specialty market |
| Compounded preparations | Endocrine and dermatology uses | Fragmented, limited transparency |
The oral and injectable segments account for most systemic use. Topical calcitriol is commercially smaller but can command higher unit prices when protected by distribution, formulation, or regional regulatory positioning.
The market has experienced long-term substitution from other vitamin D receptor activators, including paricalcitol and doxercalciferol, particularly in dialysis care. Clinical guidelines have also reduced routine use of active vitamin D in non-dialysis chronic kidney disease because of hypercalcemia risk and limited evidence of cardiovascular or kidney-outcome benefit [1].
How large is the calcitriol market?
No public filing provides a reliable worldwide sales total for all calcitriol products. Branded manufacturers generally do not disclose calcitriol revenue separately, while generic sales are distributed across hundreds of suppliers and national procurement systems.
For planning purposes, the market is best divided into three commercial pools:
- U.S. oral prescription products.
- U.S. injectable and institutional products.
- International and topical products.
An analyst base case places the combined global prescription and institutional calcitriol market in the low hundreds of millions of U.S. dollars annually, with a wide uncertainty range caused by differences in product inclusion, hospital purchasing, country coverage, and whether compounded products are counted. The market should not be compared directly with the much larger retail vitamin D supplement market, which includes nonprescription cholecalciferol and ergocalciferol.
Estimated market structure
| Segment | Relative share | Five-year direction |
|---|---|---|
| Oral systemic products | Largest | Low single-digit decline to flat |
| Injectable hospital products | Material | Flat to modest growth |
| Topical products | Small | Flat, with regional volatility |
| Compounded and ex-U.S. products | Difficult to quantify | Stable but fragmented |
The most important commercial distinction is between unit volume and revenue. Generic oral calcitriol has low per-unit pricing and limited pricing power. Injectable products and topical formulations can generate higher revenue per treated patient but face substitution and procurement pressure.
What are the sales projections for calcitriol?
The following scenario forecast uses a 2024 indexed market value of 100 rather than a fabricated dollar estimate. It reflects mature generic-market dynamics, declining use in some non-dialysis populations, stable dialysis demand, and modest pricing pressure.
| Year | Bear case | Base case | Upside case |
|---|---|---|---|
| 2024 | 100 | 100 | 100 |
| 2025 | 96 | 99 | 103 |
| 2026 | 92 | 98 | 106 |
| 2027 | 88 | 97 | 109 |
| 2028 | 84 | 96 | 112 |
| 2029 | 80 | 95 | 115 |
| 2030 | 77 | 94 | 118 |
| Implied 2024-2030 CAGR | -4.2% | -1.0% | 2.8% |
The base case assumes stable demand in dialysis and endocrine indications, offset by reduced use in non-dialysis chronic kidney disease. The upside case requires stronger adoption of topical products, supply disruptions affecting competitors, or increased use in markets where injectable calcitriol remains a standard hospital product. The bear case assumes accelerated substitution by paricalcitol, doxercalciferol, nutritional vitamin D, and newer mineral-bone-disorder therapies.
Revenue drivers through 2030
The largest positive drivers are:
- Growth in the global dialysis population.
- Continued use for hypoparathyroidism and severe hypocalcemia.
- Injectable supply shortages that shift contracts among manufacturers.
- Higher-value topical and specialty formulations.
- Growth in emerging markets with established use of active vitamin D analogs.
The main negative drivers are:
- Generic price erosion.
- Reduced routine use in non-dialysis chronic kidney disease.
- Competition from paricalcitol, doxercalciferol, and nutritional vitamin D.
- Hospital formulary substitution.
- Limited clinical differentiation among generic suppliers.
When does calcitriol lose exclusivity?
Calcitriol lost meaningful composition-of-matter exclusivity many years ago. It is a legacy small molecule, and U.S. oral and injectable products are generally available through abbreviated new drug applications or other generic pathways.
| Exclusivity category | Status |
|---|---|
| Active ingredient exclusivity | Expired |
| Core composition patent | Expired |
| Regulatory exclusivity for legacy products | Expired or no longer commercially relevant |
| Generic entry | Established |
| Biosimilar exclusivity | Not applicable |
Calcitriol has no biologic exclusivity period because it is a chemically synthesized small molecule. The commercial question is therefore not whether generic entry is legally permitted. It is whether a manufacturer can obtain sufficient scale, reliable supply, regulatory approval, and channel access.
What patents protect calcitriol products?
The active ingredient is not protected by a commercially meaningful unexpired basic patent in the United States. Any remaining patent value would ordinarily arise from a product-specific formulation, manufacturing process, delivery system, or method of use rather than from calcitriol itself.
Formulation patents
Potential formulation protection could cover:
- Stabilized aqueous injectable solutions.
- Low-dose oral liquid compositions.
- Ointments or emulsions for topical delivery.
- Packaging that improves light or oxidation stability.
- Combination products containing calcitriol and another active ingredient.
Most commercially important oral and injectable calcitriol products predate the modern generic market and do not have a meaningful blocking formulation estate. A formulation patent would need to contain enforceable claims that materially distinguish the product from standard generic capsules, solutions, or injections.
Method-of-use patents
Method-of-use protection is commercially limited because calcitriol has long-standing indications in hypocalcemia, hypoparathyroidism, renal osteodystrophy, and psoriasis. A new method-of-use patent could theoretically cover a patient subgroup, dosing schedule, combination therapy, or biomarker-defined population. Such a patent would face substantial validity and inducement risks if the claimed use overlaps with established prescribing practice.
What is the FDA regulatory status of calcitriol?
FDA-approved calcitriol products have historically included oral capsules, oral solution, injectable formulations, and topical products. Product availability differs by manufacturer and may change because of discontinuations, supply constraints, or changes in marketing status.
The principal regulatory pathways are:
| Product type | FDA pathway | Generic competition |
|---|---|---|
| Oral capsule | ANDA or legacy NDA | High |
| Oral solution | ANDA or legacy NDA | Moderate to high |
| Injectable solution | ANDA or legacy NDA | Moderate |
| Topical ointment | NDA or approved generic equivalent, depending on product | Lower than oral |
FDA approval does not guarantee continuous commercial availability. A listed product can remain approved while its manufacturer reduces distribution or stops active marketing. Drugs@FDA and the FDA Orange Book are the relevant sources for approval history, therapeutic equivalence, patent listings, and marketing status [2, 3].
What is the Orange Book status of calcitriol?
The Orange Book is relevant primarily to specific branded or reference-listed products, not to calcitriol as a molecule. Because core exclusivity has expired, Orange Book-listed patents do not generally create a broad barrier to generic entry.
For commercial diligence, the relevant checks are:
- Whether the reference-listed product remains actively marketed.
- Whether any patent remains listed for the specific dosage form.
- Whether an ANDA applicant has filed a Paragraph IV certification.
- Whether any 30-month stay or patent litigation remains active.
- Whether the relevant product has therapeutic equivalents.
The Orange Book does not capture every potential patent issue. It does not fully resolve manufacturing patents, process patents, foreign rights, trade secrets, or litigation involving patents that are not listed against an approved product.
Which companies compete in the calcitriol market?
Competition varies by jurisdiction and dosage form. The market has historically included large generic companies, hospital suppliers, specialty manufacturers, and regional pharmaceutical firms.
Competitive categories include:
- Large generic manufacturers supplying oral capsules.
- Injectable manufacturers serving hospitals and dialysis centers.
- Specialty dermatology companies supplying topical calcitriol.
- Contract manufacturers and regional distributors.
- Compounding pharmacies serving low-volume formulations.
The most important competitive advantage is supply reliability rather than molecular differentiation. A manufacturer with approved capacity, stable raw-material sourcing, and hospital-contract access can gain share even without patent protection.
Are companies challenging calcitriol patents through Paragraph IV filings?
Paragraph IV challenges are unlikely to create a major market event for legacy calcitriol products because generic entry is already established and the principal ingredient patents have expired. A Paragraph IV filing could arise against a newer formulation or topical product, but the commercial effect would depend on the specific reference product and remaining patent term.
A generic applicant would generally assess:
- Whether the reference product has active Orange Book-listed patents.
- Whether the formulation can be designed around those claims.
- Whether a Paragraph IV certification is commercially justified.
- Whether expected price erosion supports litigation costs.
- Whether the market is large enough to sustain multiple suppliers.
For standard oral calcitriol, the expected litigation risk is low. For a differentiated topical, liquid, or injectable formulation, risk is higher but still product-specific.
What generic launch risks exist for calcitriol?
A new generic launch faces operational risks that exceed its patent risk.
Supply and manufacturing barriers
Calcitriol is highly potent and used at microgram-level doses. Manufacturing controls must address:
- Accurate low-dose blending.
- Content uniformity.
- Light and oxidation sensitivity.
- Sterility for injectable products.
- Stability across shelf life.
- Cross-contamination controls.
- Specialized analytical testing.
These requirements can limit the number of qualified suppliers. They do not create a strong legal monopoly, but they can delay approval, constrain capacity, and raise costs.
Commercial launch barriers
A generic entrant also faces:
- Low price ceilings in oral products.
- Established wholesaler relationships.
- Hospital purchasing contracts.
- Substitution by competing vitamin D analogs.
- Small market size relative to regulatory and manufacturing costs.
- Limited opportunity for premium pricing.
The strongest entry opportunity is usually a shortage-prone injectable, a reliable oral liquid, or a differentiated topical product rather than another standard capsule.
How does calcitriol compare with competing vitamin D analogs?
| Product | Main positioning | Competitive effect on calcitriol |
|---|---|---|
| Calcitriol | Direct active vitamin D receptor agonist | Baseline product; low cost |
| Paricalcitol | Vitamin D analog used in secondary hyperparathyroidism | Strong dialysis and nephrology competitor |
| Doxercalciferol | Prodrug activated in the liver | Alternative for secondary hyperparathyroidism |
| Cholecalciferol | Nutritional vitamin D | Substitute in deficiency and selected CKD settings |
| Ergocalciferol | Nutritional vitamin D2 | Low-cost alternative in deficiency |
| Etelcalcetide and cinacalcet | Calcimimetics | Reduce reliance on vitamin D analogs in some dialysis patients |
Calcitriol retains advantages in cost, clinical familiarity, and direct activity. It has less favorable positioning where clinicians seek lower calcium and phosphate effects or where calcimimetics and alternative vitamin D receptor activators are preferred.
What licensing deals affect calcitriol?
No major current licensing transaction is central to the commercial value of standard calcitriol. The product is mature, generic, and widely distributed. Licensing value is more likely to arise from:
- Regional rights to topical formulations.
- Contract manufacturing arrangements.
- Hospital supply agreements.
- Distribution rights in emerging markets.
- Combination products or novel delivery systems.
A licensing transaction for standard oral calcitriol would generally require a low-cost manufacturing advantage, regulatory approvals in multiple jurisdictions, or access to a concentrated institutional channel.
What patent litigation affects calcitriol?
There is no widely recognized, market-defining U.S. patent litigation campaign centered on standard oral or injectable calcitriol. Litigation risk is more likely to arise from a specific formulation, topical product, manufacturing process, or combination therapy.
For due diligence, the absence of major composition-patent litigation is commercially important. It means that pricing, supply, regulatory execution, and contracting are more important than patent enforcement.
What is the geographic coverage of the calcitriol market?
Calcitriol is sold in North America, Europe, Asia-Pacific, Latin America, and selected Middle Eastern markets. Product names, reimbursement, and approved indications vary substantially.
- The United States has a mature generic and institutional market.
- Europe has country-specific reimbursement and marketing status.
- Japan and other Asian markets have established use in renal and endocrine care.
- Emerging markets may have greater reliance on active vitamin D products but lower realized prices.
- Topical availability is particularly dependent on regional approval and dermatology distribution.
A manufacturer seeking international expansion must manage separate registrations, pharmacopoeial requirements, labeling rules, and local procurement systems. U.S. approval does not automatically provide market access elsewhere.
How strong is the calcitriol patent estate?
The patent estate for standard calcitriol is weak from a blocking perspective and moderate only where a company controls a differentiated formulation or manufacturing process.
| Estate component | Strength |
|---|---|
| Active ingredient | Weak; expired |
| Standard oral capsule | Weak |
| Standard injectable | Weak to moderate, depending on product and process |
| Topical formulation | Moderate if claims are specific and unexpired |
| Manufacturing process | Moderate but difficult to enforce commercially |
| New method of use | Potentially moderate, subject to validity and infringement proof |
| Trade secrets and supply controls | Commercially relevant but not patent exclusivity |
The practical moat is operational rather than legal.
What is the outlook for calcitriol sales?
Calcitriol should remain a durable but low-growth pharmaceutical market. The base case is a roughly flat-to-low-single-digit annual decline through 2030, with injectable and specialty products performing better than standard oral capsules.
Revenue exposure is most attractive for manufacturers that have:
- Low-cost, validated production.
- Reliable sterile injectable capacity.
- Hospital and dialysis contracts.
- A differentiated oral liquid or topical formulation.
- Regulatory approvals across several geographic markets.
- The ability to absorb generic price erosion.
The market is less attractive for a new entrant planning to launch an undifferentiated oral capsule. Patent barriers are low, but so are pricing and differentiation opportunities.
Key Takeaways
- Calcitriol is a mature generic active vitamin D product with no meaningful composition-patent barrier.
- Public sources do not provide a consolidated global sales figure because the market is fragmented.
- A reasonable base case is flat to modest decline through 2030, with an indexed CAGR of approximately negative 1%.
- Dialysis, hypocalcemia, hypoparathyroidism, injectable supply, and topical products are the strongest commercial segments.
- Non-dialysis chronic kidney disease is a structural pressure point because routine active vitamin D use has declined.
- Paragraph IV and patent litigation risk is low for standard oral calcitriol and higher for differentiated topical, liquid, or injectable formulations.
- Manufacturing precision, sterile capacity, supply reliability, and contracting are more important than patent ownership.
- Paricalcitol, doxercalciferol, calcimimetics, and nutritional vitamin D limit long-term growth.
FAQs About Calcitriol Market Revenue and Exclusivity
Is calcitriol still a profitable drug?
Calcitriol can be profitable at scale, particularly in injectable, topical, and institutional channels. Standard oral capsules generally have limited margin because of generic competition and low pricing.
Does calcitriol have biosimilar competition?
No. Calcitriol is a chemically synthesized small molecule, so its competitors are generics and alternative vitamin D therapies rather than biosimilars.
Can a company obtain an exclusive market position for calcitriol?
Exclusivity may be possible for a genuinely new formulation, delivery system, combination product, or approved indication. Standard oral calcitriol cannot support meaningful molecule-level exclusivity.
Which calcitriol formulation has the best growth potential?
Injectable products and differentiated topical or liquid formulations have better growth potential than standard capsules. Their opportunity depends on supply reliability, regulatory status, and channel access.
Will dialysis demand support calcitriol sales through 2030?
Dialysis demand should support a stable base of use, but calcitriol will continue to compete with paricalcitol, doxercalciferol, calcimimetics, and local treatment guidelines. Dialysis growth alone is unlikely to produce high market-wide growth.
References
-
Kidney Disease: Improving Global Outcomes. (2017). KDIGO 2017 clinical practice guideline update for the diagnosis, evaluation, prevention, and treatment of chronic kidney disease-mineral and bone disorder. Kidney International Supplements, 7(1), 1-59.
-
U.S. Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations, Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
-
U.S. Food and Drug Administration. (n.d.). Electronic Orange Book data files. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book-data-files
-
U.S. Renal Data System. (2023). 2023 USRDS annual data report: Epidemiology of kidney disease in the United States. National Institutes of Health.
More… ↓
