Share This Page
Drug Sales Trends for DIOVAN
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for DIOVAN (2020)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
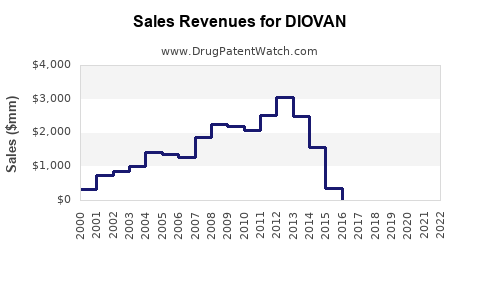
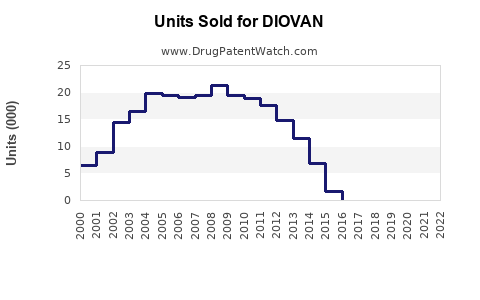
Annual Sales Revenues and Units Sold for DIOVAN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| DIOVAN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| DIOVAN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| DIOVAN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| DIOVAN | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| DIOVAN | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| DIOVAN | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
DIOVAN (VALSARTAN) MARKET ANALYSIS AND SALES PROJECTIONS
Diovan, Novartis’ brand of valsartan, is a mature antihypertensive with limited standalone brand value after loss of major patent protection in the United States and Europe. Novartis’ historical Diovan franchise generated more than $6 billion annually at its peak, but sales declined sharply after generic entry. The commercial opportunity has shifted from branded Diovan to generic valsartan, fixed-dose combinations, and newer cardiovascular products such as Entresto.
A base-case market model estimates global valsartan product sales of approximately $1.4 billion in 2024, rising to $1.6 billion by 2030. Standalone branded Diovan sales are estimated at less than $50 million annually and are likely to continue declining. Generic valsartan, combination products, and institutional tenders account for most current market value.
What is Diovan and how large is its target market?
Diovan is the trade name for valsartan, an angiotensin II receptor blocker, or ARB. It is approved for hypertension, heart failure, and reduction of cardiovascular mortality following myocardial infarction in specified patients. The product is administered as tablets, with approved strengths generally ranging from 40 mg to 320 mg depending on the indication and market.
Diovan product profile
| Attribute | Details |
|---|---|
| Active ingredient | Valsartan |
| Drug class | Angiotensin II receptor blocker |
| Original company | Novartis |
| U.S. approval | 1996 |
| Main indications | Hypertension, heart failure, post-myocardial infarction |
| Dosage forms | Immediate-release tablets; fixed-dose combinations |
| Key combinations | Valsartan/hydrochlorothiazide; amlodipine/valsartan |
| Reference product | Diovan |
| U.S. regulatory status | Generic competition established |
| Current commercial position | Mature, largely genericized product |
Valsartan competes with losartan, irbesartan, candesartan, telmisartan, olmesartan, ACE inhibitors, calcium-channel blockers, thiazide diuretics, and combination therapies. Prescribing is increasingly determined by generic price, payer formulary position, clinical familiarity, and availability rather than brand differentiation.
How much did Diovan sales generate historically?
Diovan was one of Novartis’ largest products before patent expiry. Peak annual sales exceeded $6 billion, supported by broad hypertension use and later expansion into heart failure and post-myocardial infarction treatment.
| Year | Approximate Diovan sales | Commercial development |
|---|---|---|
| 2008 | $5.7 billion | Mature global brand |
| 2009 | $6.0 billion | Near peak sales |
| 2010 | $6.1 billion | Peak-period performance |
| 2011 | $6.0 billion | Generic-entry preparation |
| 2012 | $4.7 billion | U.S. generic competition |
| 2013 | $3.2 billion | Accelerated erosion |
| 2014 | Approximately $2 billion | Broad generic substitution |
| 2024 | Less than $50 million estimated branded sales | Residual brand and selected markets |
Novartis reported Diovan sales of approximately $6 billion around the peak period, followed by a steep decline after loss of exclusivity and generic launches.[1] The historical sales curve reflects the standard lifecycle of an oral small-molecule cardiovascular product: rapid uptake, expansion through additional indications, high-margin maturity, and abrupt price erosion after patent expiry.
When did Diovan lose exclusivity?
Diovan lost practical market exclusivity in the United States in 2012. The core U.S. patent, U.S. Patent No. 5,399,578, covered valsartan-related compounds and had an expiry date in the 2012 period, subject to patent-term calculations and pediatric exclusivity.[2]
Key exclusivity milestones
| Event | Approximate date | Effect |
|---|---|---|
| U.S. approval | 1996 | Launch of Diovan |
| Core compound patent protection | Through 2012 | Protected valsartan monotherapy |
| U.S. generic entry | 2012 | Rapid price and volume erosion |
| European patent expiry | 2011-2012 period | Broad European generic entry |
| Combination-product erosion | 2012 onward | Decline in Diovan HCT and related products |
| Current status | Genericized | Limited standalone brand protection |
Patent expiry did not eliminate every form of intellectual property immediately. Formulation, combination, process, and method-of-use patents may have had different expiry dates and enforceability. Those rights did not preserve substantial exclusivity for the standalone Diovan franchise.
What patents protect Diovan and valsartan products?
The principal historical protection was the valsartan compound patent. Later patent activity covered specific formulations, combinations, manufacturing processes, and therapeutic uses.
Core patent estate
| Patent or right | Subject matter | Commercial relevance |
|---|---|---|
| U.S. Patent No. 5,399,578 | Valsartan and related substituted heterocyclic compounds | Principal compound protection |
| Diovan regulatory exclusivity | FDA-approved reference-product exclusivity | Expired |
| Valsartan/HCT patents | Fixed-dose combination of valsartan and hydrochlorothiazide | Protected combination products for limited periods |
| Amlodipine/valsartan patents | Fixed-dose combination marketed as Exforge | Separate product estate |
| Process patents | Manufacturing and purification methods | Potential manufacturing barriers, generally limited after broad generic access |
| Method-of-use patents | Hypertension, heart failure, and cardiovascular-risk uses | Narrower protection and subject to label carve-outs |
Patent protection for a mature small-molecule product should be analyzed by product configuration rather than by brand name alone. Diovan monotherapy, Diovan HCT, and amlodipine/valsartan had separate regulatory and patent histories.
What is the Orange Book status of Diovan?
The U.S. Food and Drug Administration’s Orange Book historically listed Diovan and related valsartan products as reference-listed drugs. The commercial significance of those listings declined after expiration of the principal patents and approval of multiple abbreviated new drug applications.
Generic valsartan manufacturers typically relied on ANDA certifications, including Paragraph III or Paragraph IV certifications depending on the status of listed patents. Once the core patents expired and generic products launched, the Orange Book ceased to provide a meaningful barrier to ordinary valsartan tablets.
The current commercial question is no longer whether generic valsartan can enter the market. It is whether a manufacturer can achieve sufficient scale, supply reliability, and reimbursement access to earn acceptable margins.
Which companies challenged Diovan patents?
Generic manufacturers, including major U.S., European, Indian, and Israeli pharmaceutical companies, pursued valsartan entry as patent protection approached expiry. Companies active in generic ARB products have included Teva, Mylan, Sandoz, Dr. Reddy’s Laboratories, Torrent Pharmaceuticals, Zydus, Lupin, and other regional suppliers.
Paragraph IV activity was commercially important before 2012 because an early successful challenge could accelerate entry. After expiry, competition shifted toward ANDA approvals, manufacturing capacity, tender access, and price.
Generic-entry dynamics
- Generic applicants targeted the compound patent and relevant listed combination patents.
- Patent challenges created potential 180-day first-filer advantages under the Hatch-Waxman framework.
- Multiple manufacturers entered after the main patent barrier expired.
- Prices declined as additional suppliers obtained approval.
- Pharmacy substitution shifted volume away from Diovan.
What litigation and settlements affected Diovan?
Diovan’s major litigation exposure centered on generic challenges to Novartis’ core valsartan patents and related product rights. The economically important resolution was the transition from protected brand sales to generic competition around 2012.
The Diovan case differs from products with active patent settlements that delay generic entry for many years. Valsartan became a broad generic market relatively soon after core exclusivity ended. Current litigation risk is more likely to involve manufacturing, supply, product liability, recalls, or regulatory compliance than an attempt to restore monopoly pricing.
The 2018 discovery of nitrosamine contamination in certain valsartan products led to global recalls and regulatory investigations. The issue affected multiple manufacturers and exposed supply-chain vulnerabilities involving active pharmaceutical ingredients sourced from selected production facilities.[3] It did not restore Diovan’s brand exclusivity.
What is the current competitive landscape for valsartan?
Valsartan competes in a high-volume, low-price therapeutic category. Generic substitution is widespread in the United States and Europe. In emerging markets, branded generics retain more pricing power, but local competition remains substantial.
Main competitive products
| Product | Active ingredient or combination | Competitive position |
|---|---|---|
| Diovan | Valsartan | Reference brand with limited residual sales |
| Generic valsartan | Valsartan | Primary volume product |
| Co-Diovan and generic equivalents | Valsartan/hydrochlorothiazide | Established combination market |
| Exforge and generic equivalents | Amlodipine/valsartan | Higher-value combination segment |
| Losartan | Losartan | Large ARB competitor |
| Atacand | Candesartan | Heart-failure and hypertension competitor |
| Avapro | Irbesartan | Mature ARB competitor |
| Micardis | Telmisartan | Long-acting ARB competitor |
| Entresto | Sacubitril/valsartan | Higher-value heart-failure product, not a direct generic Diovan substitute |
Entresto is strategically important because it uses valsartan as one component but has a different mechanism, clinical positioning, and patent estate. It has largely replaced Diovan as Novartis’ major cardiovascular growth product. Entresto’s sales should not be counted as Diovan or generic valsartan revenue.
What are the sales projections for Diovan and valsartan?
The following model separates residual branded Diovan revenue from the broader valsartan product market. The forecast assumes continued generic substitution, low inflation-adjusted pricing, stable global hypertension prevalence, and modest growth in fixed-dose combinations.
Global sales projection
| Year | Branded Diovan | Generic standalone valsartan | Valsartan combinations | Total valsartan product market |
|---|---|---|---|---|
| 2024A | $35 million | $850 million | $515 million | $1.40 billion |
| 2025E | $30 million | $870 million | $535 million | $1.44 billion |
| 2026E | $26 million | $890 million | $555 million | $1.47 billion |
| 2027E | $22 million | $910 million | $575 million | $1.51 billion |
| 2028E | $19 million | $925 million | $595 million | $1.54 billion |
| 2029E | $16 million | $940 million | $615 million | $1.57 billion |
| 2030E | $14 million | $950 million | $640 million | $1.60 billion |
The model implies approximately 2.2% compound annual growth for the total valsartan product market from 2024 to 2030. Branded Diovan declines at approximately 14% annually as residual prescriptions migrate to generic equivalents.
Scenario analysis
| Scenario | 2030 total valsartan sales | Main assumptions |
|---|---|---|
| Downside | $1.25 billion | Accelerated price erosion, reduced branded-generic use, tender compression |
| Base case | $1.60 billion | Stable volume, modest combination growth, low price inflation |
| Upside | $1.95 billion | Higher diagnosis rates, stronger emerging-market demand, combination-product expansion |
The upside case does not depend on a return of Diovan brand pricing. It depends on volume growth and higher-value combination products.
What generic-entry risks exist for Diovan?
Generic entry is already established, so the risk is commercial erosion rather than future launch disruption. The main risks are:
- Continued pharmacy substitution away from branded Diovan.
- Price compression from additional suppliers.
- Tender concentration among a small number of low-cost manufacturers.
- Reimbursement exclusion of the Novartis brand.
- Product recalls caused by active pharmaceutical ingredient contamination.
- Supply interruptions that shift volume temporarily between manufacturers.
- Reduced physician differentiation for standalone valsartan.
- Substitution toward losartan or other ARBs.
A new generic entrant would face low regulatory novelty but meaningful operational barriers. FDA approval alone does not guarantee commercial access. Manufacturers need validated API supply, adequate batch capacity, quality-system compliance, stable distribution, and payer contracts.
How strong is the Diovan patent estate?
The standalone Diovan patent estate is weak from a present-value perspective because the core compound protection expired and generic competition is entrenched. Residual value may remain in selected jurisdictions, branded-generic markets, combination products, or manufacturing know-how.
| Patent-estate category | Current strength | Commercial assessment |
|---|---|---|
| Core valsartan compound | Low | Expired |
| Standalone tablet formulation | Low | Generic substitution established |
| Valsartan/HCT combination | Low to moderate | Product-specific rights largely matured |
| Amlodipine/valsartan | Product-dependent | Separate combination market |
| Manufacturing processes | Moderate in narrow cases | Difficult to use as a broad market barrier |
| Method of use | Low to moderate | May support narrow indications, not broad monopoly |
| Trade secrets and supply chain | Moderate operational value | Can affect cost and reliability |
Diovan’s strongest remaining defenses are regulatory quality, physician familiarity, and supply reliability. Those are commercial advantages, not meaningful patent exclusivity.
Are biosimilar risks relevant to Diovan?
No. Diovan is a chemically synthesized small-molecule drug, so biosimilar regulation does not apply. The relevant competitive pathway is the ANDA process for generic drugs under the Hatch-Waxman Act.
This distinction matters for forecasting. Generic valsartan manufacturers can rely on pharmaceutical equivalence and bioequivalence rather than conducting the type of comparative clinical development required for biosimilars. Entry costs and timelines are therefore lower than for biologic products.
What FDA regulatory issues affect valsartan sales?
The FDA approved valsartan as a conventional small-molecule prescription drug and authorized generic products through ANDAs. The most important recent regulatory event was the valsartan impurity crisis, which resulted in recalls beginning in 2018 after detection of N-nitrosodimethylamine and related impurities in some products.[3]
Regulatory controls now emphasize:
- API supplier qualification.
- Nitrosamine risk assessment.
- Process impurity controls.
- Stability testing.
- Manufacturing-site inspections.
- Recall readiness.
- Continuity of supply.
These requirements can favor larger manufacturers with diversified sourcing and stronger quality systems. They can also create temporary price increases when suppliers exit or products are recalled.
What licensing deals affect Diovan?
Diovan’s original commercialization was controlled by Novartis, with regional distribution and generic licensing arrangements varying by market. The most commercially important licensing activity now concerns generic valsartan supply, authorized generics, local manufacturing, and fixed-dose combinations.
The product does not have a current licensing profile comparable with newer specialty drugs. Licensing value is concentrated in:
- Regional registration rights.
- Local manufacturing arrangements.
- Hospital and government tenders.
- Authorized-generic supply.
- Combination-product commercialization.
- API and finished-dose supply contracts.
The strategic value of Diovan-related licensing is therefore volume access rather than patent-based royalty economics.
How does Diovan compare with Entresto?
| Factor | Diovan | Entresto |
|---|---|---|
| Active components | Valsartan | Sacubitril/valsartan |
| Drug class | ARB | Angiotensin receptor-neprilysin inhibitor |
| Primary commercial use | Hypertension and selected cardiovascular indications | Heart failure |
| Patent position | Mature and expired | Active product-specific estate during much of the forecast period |
| Generic competition | Established | More limited and jurisdiction-dependent |
| Revenue profile | Low-value genericized | Higher-value branded cardiovascular product |
| Novartis strategic role | Legacy product | Major cardiovascular franchise |
Entresto has materially higher revenue potential because its clinical positioning and patent protection differ from standalone valsartan. Diovan should not be treated as a proxy for Entresto’s growth trajectory.
What geographic markets offer the greatest opportunity?
The United States and Western Europe offer high prescription volume but limited branded pricing. Growth opportunities are more likely in China, India, Latin America, Southeast Asia, the Middle East, and selected African markets.
Geographic outlook
| Region | Market condition | Outlook |
|---|---|---|
| United States | Mature, generic-dominated | Stable volume, continuing price pressure |
| Western Europe | Mature and tender-driven | Low growth, low pricing |
| Japan | Mature branded-generic market | Stable demand with local pricing controls |
| China | Large hypertension population | Volume growth and local competition |
| India | Strong branded-generic presence | Competitive growth, fragmented pricing |
| Latin America | Mixed generic and branded use | Moderate volume growth |
| Middle East | Import and tender dependent | Opportunity for reliable suppliers |
| Africa | Underdiagnosis and access constraints | Long-term volume potential, low near-term pricing |
Emerging markets can support higher unit growth, but revenue conversion depends on reimbursement, public procurement, local registration, and distribution infrastructure.
What are the likely generic launch and investment scenarios?
For standalone Diovan, no future first generic launch event is expected in the major markets because entry already occurred. The relevant scenarios are:
- Residual brand decline: branded Diovan falls toward a small maintenance business.
- Generic consolidation: supply shifts toward fewer manufacturers as margins compress.
- Combination growth: valsartan/hydrochlorothiazide and amlodipine/valsartan gain share relative to monotherapy.
- Supply disruption: recalls or API constraints create temporary pricing and share volatility.
- Emerging-market expansion: volume rises while average selling prices remain low.
- Strategic substitution: physicians and payers shift heart-failure patients toward Entresto or other newer therapies.
Key Takeaways
- Diovan is a mature valsartan brand with minimal remaining standalone exclusivity.
- Historical peak sales exceeded $6 billion annually.
- Core U.S. patent protection expired in the 2012 period, enabling broad generic competition.
- Branded Diovan sales are estimated below $50 million annually.
- The broader global valsartan product market is modeled at $1.4 billion in 2024 and $1.6 billion in 2030.
- Generic valsartan and fixed-dose combinations account for nearly all current commercial value.
- Biosimilar risk is irrelevant because valsartan is a small-molecule drug.
- The main risks are price erosion, supply disruption, API quality events, and payer exclusion.
- Entresto is a separate, higher-value Novartis product and should not be included in Diovan revenue forecasts.
- Future opportunity lies in combination products, emerging markets, tenders, and reliable low-cost manufacturing.
FAQs About Diovan Sales, Patents, and Market Competition
Is Diovan still sold in the United States?
Diovan may remain available in limited branded channels, but U.S. valsartan prescriptions are overwhelmingly supplied by generic manufacturers. Brand availability does not imply meaningful brand pricing power.
What is the generic name for Diovan?
The generic name is valsartan. Generic valsartan is available in multiple tablet strengths and from numerous manufacturers.
Does Novartis still earn significant revenue from Diovan?
No. Novartis’ major cardiovascular revenue has shifted from Diovan to newer products, particularly Entresto. Diovan revenue is a small residual amount compared with its historical peak.
Can a new manufacturer still enter the valsartan market?
Yes, subject to FDA or other national regulatory approval, bioequivalence, manufacturing compliance, API qualification, and commercial distribution. The principal barriers are operational and economic rather than patent-based.
Is valsartan a good licensing opportunity?
Valsartan can support licensing opportunities in emerging markets, public tenders, authorized generics, and fixed-dose combinations. Standalone branded licensing has limited value because broad generic competition has eliminated most exclusivity-based economics.
References
-
Novartis AG. (2009-2014). Annual report. Basel, Switzerland: Author.
-
U.S. Patent and Trademark Office. (1995). U.S. Patent No. 5,399,578: N-substituted heterocyclic compounds. Washington, DC: U.S. Department of Commerce.
-
U.S. Food and Drug Administration. (2018). FDA updates and press announcements on valsartan, losartan, and irbesartan recalls. Silver Spring, MD: U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (1996). Diovan prescribing information. Silver Spring, MD: U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. Silver Spring, MD: U.S. Department of Health and Human Services.
More… ↓
