Share This Page
Drug Sales Trends for BUDESONIDE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for BUDESONIDE (2020)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
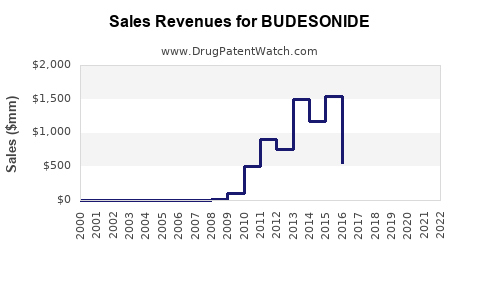
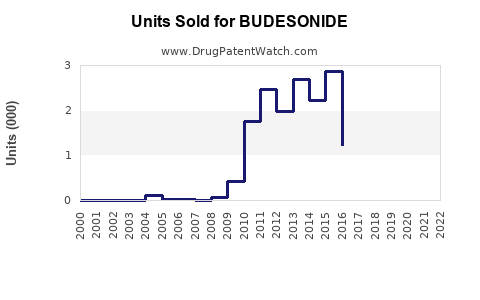
Annual Sales Revenues and Units Sold for BUDESONIDE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| BUDESONIDE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| BUDESONIDE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| BUDESONIDE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| BUDESONIDE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| BUDESONIDE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Budesonide Market Analysis, Sales Forecast, Patent Position and Competitive Outlook
Budesonide is a mature corticosteroid with a fragmented but durable market. Generic inhaled, nebulized, oral and rectal products account for most volume, while specialty controlled-release products generate the highest commercial value. The largest growth opportunity is Tarpeyo, a targeted-release budesonide product for immunoglobulin A nephropathy, although competition from sparsentan, SGLT2 inhibitors and future IgA nephropathy therapies limits long-term pricing power.
A reasonable base-case estimate places global budesonide product sales at approximately $2.0 billion to $2.4 billion in 2024, rising to $2.5 billion to $3.1 billion by 2029. Growth is expected to come from specialty oral formulations and emerging renal indications rather than traditional asthma and COPD products.
What is the current budesonide market size?
Budesonide is sold in several delivery systems:
- Inhaled dry powder and metered-dose products
- Nebulized suspension
- Oral enteric-coated capsules
- Oral extended-release tablets
- Oral targeted-release capsules
- Rectal foam and enemas
- Nasal sprays
- Specialty targeted-release products for IgA nephropathy
The market is difficult to measure as a single product category because manufacturers report sales by brand, franchise or therapeutic area. Generic budesonide is also distributed through multiple suppliers, making volume and revenue data fragmented.
Estimated 2024 market by product segment
| Segment | Principal products | Estimated 2024 global sales | Market position |
|---|---|---|---|
| Inhaled budesonide | Pulmicort, Symbicort combination products, generics | $1.1B-$1.4B | Largest volume segment |
| Oral inflammatory bowel disease products | Entocort EC, Uceris, Ortikos, generics | $300M-$450M | Mature, price-competitive |
| Tarpeyo / Nefecon | Targeted-release budesonide for IgA nephropathy | $150M-$250M | Fastest-growing branded segment |
| Rectal products | Uceris foam and generic equivalents | $50M-$100M | Smaller specialty market |
| Nasal products | Rhinocort and generics | $100M-$200M | Mature over-the-counter and prescription market |
| Other formulations | Regional and hospital products | $100M-$200M | Fragmented |
| Total estimated market | $2.0B-$2.4B |
The estimates include budesonide as a single agent and, where relevant, the budesonide component of combination products. They exclude unrelated inhaled corticosteroids such as fluticasone and mometasone.
Which budesonide products generate the most revenue?
Tarpeyo has the strongest growth profile
Tarpeyo, developed by Calliditas Therapeutics, is a delayed-release formulation of budesonide designed to release drug in the ileum. The product is intended to reduce pathogenic mucosal immune activity associated with IgA nephropathy.
The FDA granted accelerated approval to Tarpeyo in December 2021 based on reduction in proteinuria, a surrogate endpoint associated with kidney disease progression (FDA, 2021). Calliditas reported rapid commercial growth after launch, driven by nephrologist adoption, specialty pharmacy distribution and the absence of a directly substitutable generic product.
Tarpeyo has a higher price and greater revenue potential per treated patient than conventional budesonide products. Its addressable population is also smaller. Commercial performance depends on:
- Identification of patients with IgA nephropathy
- Kidney biopsy and disease-risk assessment
- Payer coverage
- Use before or alongside other renoprotective therapies
- Evidence supporting reduction in long-term kidney function decline
- Competitive pressure from sparsentan and SGLT2 inhibitors
Inhaled budesonide remains the largest volume business
Pulmicort is AstraZeneca’s inhaled budesonide franchise. It is available as a nebulized suspension and as an inhalation powder in selected markets. Budesonide is also combined with formoterol in Symbicort and generic equivalents.
The inhaled market is mature. Generic and authorized-generic competition has reduced pricing for single-agent budesonide products. Combination products maintain stronger commercial value because they combine an inhaled corticosteroid with a long-acting bronchodilator and are used for asthma and chronic obstructive pulmonary disease.
Oral gastrointestinal products remain commercially durable
Entocort EC and related generic products are used for Crohn’s disease. Uceris and generic equivalents are used for ulcerative colitis. These products have established clinical roles because budesonide produces high local gastrointestinal exposure with lower systemic corticosteroid exposure than conventional prednisone.
The segment is exposed to generic substitution and therapeutic competition from mesalamine, biologics, JAK inhibitors, S1P modulators and other advanced inflammatory bowel disease treatments.
What are the sales projections for budesonide through 2029?
The following forecast uses 2024 estimated market sales as the base year and separates mature generic segments from specialty targeted-release products.
Base-case global sales forecast
| Year | Inhaled products | Oral and rectal GI products | Tarpeyo and renal products | Other products | Total estimated sales |
|---|---|---|---|---|---|
| 2024 | $1.25B | $400M | $200M | $250M | $2.10B |
| 2025 | $1.27B | $405M | $280M | $252M | $2.21B |
| 2026 | $1.29B | $410M | $380M | $255M | $2.34B |
| 2027 | $1.31B | $415M | $490M | $258M | $2.47B |
| 2028 | $1.33B | $420M | $600M | $261M | $2.61B |
| 2029 | $1.35B | $425M | $700M | $264M | $2.74B |
Forecast scenarios
| Scenario | 2029 estimated sales | Main assumptions |
|---|---|---|
| Downside | $2.1B-$2.3B | Faster generic erosion, limited Tarpeyo uptake, stronger renal competition |
| Base case | $2.6B-$2.9B | Stable inhaled demand and continued Tarpeyo growth |
| Upside | $3.2B-$3.7B | Broader renal adoption, favorable confirmatory data and additional targeted-release products |
The market’s estimated compound annual growth rate is approximately 4% to 6% in the base case. Tarpeyo may grow at more than 20% annually through the middle of the forecast period, but its growth will be offset by flat or declining revenue from legacy genericized products.
When does budesonide lose exclusivity?
Most conventional budesonide products have already lost core patent exclusivity in the United States and major European markets.
Major products and exclusivity position
| Product | Active ingredient and formulation | Sponsor or originator | Exclusivity position |
|---|---|---|---|
| Pulmicort | Inhaled budesonide | AstraZeneca | Core protection expired; generics available |
| Entocort EC | Enteric-coated oral budesonide | AstraZeneca | Core protection expired; generics available |
| Uceris | Extended-release oral budesonide | Salix Pharmaceuticals | Core protection substantially eroded; generic competition |
| Uceris foam | Rectal extended-release budesonide | Salix Pharmaceuticals | Market-specific formulation protection and generic challenges |
| Ortikos | Extended-release budesonide capsule | Adare/related sponsors | Generic and branded competition |
| Tarpeyo | Targeted-release budesonide | Calliditas Therapeutics | Product-specific patents and regulatory exclusivity remain relevant |
The exact loss-of-exclusivity date depends on dosage form, strength, patent listing, pediatric exclusivity, patent-term adjustment, settlement terms and the applicant’s approved indication. Budesonide has no single market-wide expiration date.
What patents protect Tarpeyo and other budesonide formulations?
The strongest remaining intellectual-property position is concentrated in formulation and use patents rather than the budesonide molecule itself.
Formulation patents
Formulation claims may cover:
- Enteric coatings
- Delayed release in the ileum
- Particle size and drug distribution
- Capsule composition
- pH-dependent dissolution
- Site-specific gastrointestinal delivery
- Extended-release matrices
- Rectal foam delivery systems
- Nebulized suspension characteristics
These claims can delay generic entry when they are listed in the FDA Orange Book and survive validity and infringement challenges. They do not necessarily prevent all competing budesonide products because a competitor may design around coating materials, release profiles or capsule architecture.
Method-of-use patents
Method-of-use claims may cover:
- Treatment of IgA nephropathy
- Reduction of proteinuria
- Treatment of Crohn’s disease
- Induction of remission in ulcerative colitis
- Local treatment of inflammatory bowel disease
- Use in defined patient populations or disease-severity groups
Use patents are more vulnerable to skinny-label strategies. A generic applicant may seek approval for non-protected indications while omitting a patented use from its label. Enforcement then depends on the product label, promotional conduct, prescribing patterns and induced-infringement evidence.
What is the Orange Book status of budesonide products?
The FDA Orange Book lists approved drug products and, for eligible products, associated patents and exclusivity information. Conventional budesonide products have extensive generic competition and multiple abbreviated new drug applications.
Orange Book exposure differs by product:
- Pulmicort inhalation products have generic alternatives in several dosage forms.
- Entocort EC has generic oral alternatives.
- Uceris tablets and foam have faced generic competition and patent disputes.
- Tarpeyo is a newer specialty product with a more concentrated patent and regulatory-exclusivity profile.
- Combination products such as budesonide/formoterol have separate product-specific patent histories.
A generic applicant filing an ANDA may submit a Paragraph IV certification asserting that a listed patent is invalid, unenforceable or not infringed. The reference-product sponsor can file an infringement action within 45 days, potentially triggering a 30-month stay of FDA approval under the Hatch-Waxman framework.
Which companies are challenging budesonide exclusivity?
Competition comes from several groups:
- Teva Pharmaceutical Industries
- Mylan/Viatris
- Sandoz
- Amneal Pharmaceuticals
- Hikma Pharmaceuticals
- Cipla
- Lupin
- Zydus Pharmaceuticals
- Perrigo and other regional suppliers
- Specialty manufacturers developing targeted-release products
The most commercially important challenges have involved inhaled products, oral gastrointestinal formulations and rectal delivery systems. Tarpeyo faces a different risk profile because a future competitor would need to demonstrate pharmaceutical equivalence, bioequivalence and the required clinical or regulatory basis for the targeted-release formulation.
What patent litigation affects budesonide?
Budesonide litigation has generally focused on formulation patents, abbreviated new drug applications and the scope of generic labels. The main legal issues include:
- Whether a generic product infringes a release-profile or coating claim.
- Whether a patent claim is enabled and adequately described.
- Whether the patent is obvious in view of prior budesonide formulations.
- Whether a generic label induces infringement of a patented method of use.
- Whether the proposed product has the same pharmaceutical characteristics as the reference product.
- Whether settlement terms delay generic launch or permit an earlier entry date.
The litigation risk is highest for controlled-release and site-specific formulations. The risk is lower for conventional inhaled or oral products with expired composition and formulation claims.
How strong is the budesonide patent estate?
Overall assessment
| Patent category | Strength | Commercial impact |
|---|---|---|
| Budesonide composition-of-matter patents | Very low | Molecule is long genericized |
| Conventional inhaled formulation patents | Low to moderate | Product-specific protection remains, but competition is established |
| Oral enteric-coated formulations | Low to moderate | Generic substitution is significant |
| Rectal foam formulations | Moderate | Delivery-system claims can delay direct substitutes |
| Tarpeyo targeted-release formulation | Moderate to strong | Most important remaining branded protection |
| Method-of-use patents | Moderate | Value depends on label design and enforceability |
| Manufacturing patents | Moderate | Can raise entry costs but rarely prevents all competition |
Tarpeyo’s patent position is stronger than the legacy budesonide franchises because the product depends on a specific release site and therapeutic use. It is still narrower than a composition-of-matter estate for a new chemical entity.
How does budesonide compare with competing therapies?
Asthma and COPD
Budesonide competes with:
- Fluticasone propionate
- Fluticasone furoate
- Beclomethasone
- Mometasone
- Ciclesonide
- Budesonide/formoterol combinations
- Fluticasone/salmeterol combinations
- Triple inhaled therapies
Budesonide/formoterol has benefited from broad clinical use and generic availability in some markets. Competition is shifting toward combination inhalers, once-daily dosing and single-inhaler triple therapy.
Inflammatory bowel disease
Budesonide competes with:
- Mesalamine
- Prednisone and other systemic corticosteroids
- Biologics targeting TNF, IL-12/23 and integrins
- JAK inhibitors
- S1P receptor modulators
- Other locally acting corticosteroid formulations
Budesonide remains useful for induction of remission but is not a preferred long-term maintenance treatment because corticosteroid exposure limits chronic use.
IgA nephropathy
Tarpeyo competes with:
- Sparsentan
- SGLT2 inhibitors
- Renin-angiotensin system inhibitors
- Systemic corticosteroids
- Supportive-care regimens
- Investigational complement and B-cell pathway therapies
The commercial opportunity is substantial relative to legacy budesonide products because IgA nephropathy has a chronic disease course and a concentrated specialist prescriber base. The competitive threat is also higher because renal therapies are being developed specifically to slow kidney-function decline.
What generic launch scenarios exist for budesonide?
Scenario 1: Mature product continuation
For Pulmicort, Entocort and Uceris, generic products remain widely available. Revenue is sustained by prescription volume, hospital demand, regional brand loyalty and supply reliability. Net pricing remains under pressure.
Scenario 2: Additional formulation-specific generic entry
A new generic entrant can create sharp price erosion if it receives approval for a high-volume dosage form. The first approved generic may capture a disproportionate share through pharmacy substitution, followed by lower prices as additional suppliers enter.
Scenario 3: Tarpeyo Paragraph IV challenge
A Tarpeyo challenge could produce one of three outcomes:
- Litigation settlement with a negotiated launch date
- Court decision upholding or invalidating relevant patents
- Design-around product with a different release system or clinical pathway
A successful early generic or follow-on targeted-release product would materially reduce Tarpeyo revenue because the product’s value is driven by branded pricing rather than molecule scarcity.
What licensing deals and commercial partnerships matter?
Budesonide has been commercialized through multiple licensing, acquisition and regional distribution arrangements. Relevant business structures include:
- AstraZeneca’s development and commercialization of Pulmicort and Symbicort
- Salix’s commercialization of Uceris
- Calliditas’s development and commercialization of Nefecon/Tarpeyo
- Regional licensing and distribution of generic inhaled and oral formulations
- Contract manufacturing arrangements for inhalers, nebulizer suspensions and controlled-release capsules
The most strategically important asset is the targeted-release platform behind Tarpeyo. Its value includes potential expansion into other immune-mediated kidney diseases if clinical evidence and regulatory pathways support additional indications.
What is the FDA regulatory status of budesonide?
Budesonide is FDA-approved in multiple dosage forms and indications, including:
- Maintenance treatment of asthma
- Asthma and COPD treatment in combination with formoterol
- Crohn’s disease
- Ulcerative colitis
- Nasal allergy symptoms
- IgA nephropathy through Tarpeyo’s targeted-release formulation
The regulatory pathway differs by product. Conventional generics use the ANDA pathway. Tarpeyo was approved through an NDA and received accelerated approval based on a surrogate endpoint. Its long-term commercial position depends on confirmatory evidence showing clinical benefit, such as reduced decline in kidney function or delayed progression to kidney failure.
What is the geographic coverage of budesonide patents?
Budesonide has broad global commercial availability, but the strength of patent protection varies by jurisdiction.
- United States: extensive generic competition for legacy products; stronger product-specific protection for newer targeted-release products.
- European Union: mature generic market with national reimbursement and substitution differences.
- Japan: established inhaled and gastrointestinal use, with local regulatory and pricing controls.
- China: expanding inhaled and gastrointestinal market with domestic manufacturers and volume-based procurement pressure.
- Emerging markets: high volume potential but lower realized pricing and weaker enforcement consistency.
The United States is the most important market for Tarpeyo because of specialty pricing and concentrated nephrology prescribing. Europe and Asia offer larger patient pools but generally lower per-patient revenue.
What is the investment outlook for budesonide?
Budesonide is a defensive, diversified pharmaceutical market rather than a single high-growth asset.
Positive factors
- Long clinical history and broad physician familiarity
- Multiple approved dosage forms
- Large installed base in asthma and inflammatory bowel disease
- Continued demand for inhaled corticosteroids
- Specialty growth from targeted-release renal products
- Manufacturing and formulation know-how that can create barriers to entry
Negative factors
- Extensive generic competition
- Low pricing for conventional products
- Limited differentiation of the active ingredient
- Reimbursement pressure
- Competitive renal pipeline
- Dependence of Tarpeyo on confirmatory clinical evidence
- Potential Paragraph IV litigation and settlement risk
For investors, the key distinction is between low-margin generic budesonide volume and high-margin branded targeted-release budesonide revenue. A company with only legacy budesonide products has limited pricing power. A company controlling a protected targeted-release formulation has greater near-term growth but higher regulatory and patent concentration risk.
Key Takeaways
- Global budesonide product sales are estimated at approximately $2.0 billion to $2.4 billion in 2024.
- Base-case sales could reach $2.6 billion to $2.9 billion by 2029.
- Inhaled budesonide is the largest segment by volume and revenue, but it is mature and heavily genericized.
- Tarpeyo is the most important growth product and may reach approximately $600 million to $800 million in annual sales by 2029 under a base case.
- Legacy composition-of-matter protection has expired; remaining protection centers on formulations, delivery systems and methods of use.
- The highest patent risk is concentrated in targeted-release and rectal formulations.
- Paragraph IV challenges remain a material risk for newer formulation products.
- Tarpeyo’s long-term value depends on confirmatory renal outcomes and resistance from sparsentan, SGLT2 inhibitors and emerging IgA nephropathy therapies.
- Manufacturing complexity can delay entry for inhalation and targeted-release products but does not eliminate generic competition.
- Budesonide is commercially durable, but its market growth is driven by specialty formulation innovation rather than the underlying molecule.
FAQs
What is the highest-value budesonide product?
Tarpeyo is likely the highest-value single-agent budesonide product because it is a branded targeted-release therapy for IgA nephropathy with specialty pricing. Inhaled budesonide combination products generate greater aggregate market revenue but include formoterol and are not pure budesonide products.
Is budesonide still patent protected?
The budesonide molecule itself is no longer protected by meaningful composition-of-matter exclusivity. Certain products, including targeted-release and rectal formulations, may retain formulation or method-of-use patents.
Can a generic company make budesonide for IgA nephropathy?
A generic company would need to satisfy FDA requirements for the relevant reference product and address listed patents, regulatory exclusivity and the patented indication. A conventional budesonide generic would not automatically be substitutable for Tarpeyo.
Does budesonide have biosimilar competition?
No. Budesonide is a small-molecule corticosteroid, not a biologic. Competition occurs through generic drug applications rather than the biosimilar pathway.
What is the biggest commercial risk to Tarpeyo?
The largest risks are failure of confirmatory clinical evidence, earlier-than-expected generic or follow-on entry, and displacement by competing IgA nephropathy therapies that demonstrate stronger effects on long-term kidney outcomes.
References
- U.S. Food and Drug Administration. (2021). FDA grants accelerated approval to targeted-release budesonide for IgA nephropathy.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2024). Pulmicort Respules prescribing information. AstraZeneca.
- U.S. Food and Drug Administration. (2024). Uceris prescribing information. Salix Pharmaceuticals.
- U.S. Food and Drug Administration. (2024). Tarpeyo prescribing information. Calliditas Therapeutics.
- Calliditas Therapeutics AB. (2024). Annual report 2023.
- AstraZeneca PLC. (2024). Annual report 2023.
- U.S. Food and Drug Administration. (2024). Approved drug products and abbreviated new drug application database.
More… ↓
