Share This Page
Drug Sales Trends for adapalene
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for adapalene (2019)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
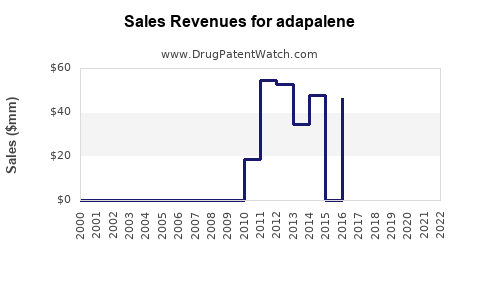
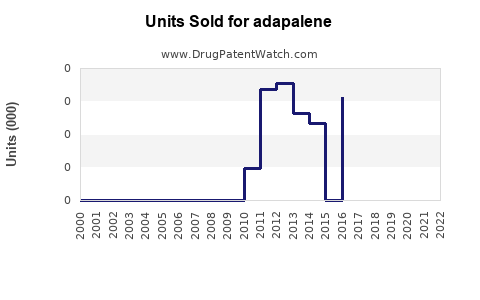
Annual Sales Revenues and Units Sold for adapalene
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ADAPALENE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ADAPALENE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ADAPALENE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Adapalene Market Analysis, Sales Forecast, Competitive Landscape, and Growth Outlook
Adapalene is a mature topical retinoid used primarily for acne vulgaris. The market is divided between generic adapalene, branded Differin, and fixed-dose adapalene/benzoyl peroxide products such as Epiduo and Epiduo Forte. Volume growth remains supported by over-the-counter access in the United States, dermatology prescribing, adolescent acne prevalence, and expansion of consumer skin-care channels. Pricing pressure is high because generic adapalene is widely available and the core molecule has limited differentiation.
Public companies do not report global adapalene revenue as a separate line item. The sales figures below are therefore market-model estimates covering adapalene monotherapy and, where stated, adapalene combination products.
What is adapalene and how is it used?
Adapalene is a third-generation topical retinoid indicated for the treatment of acne vulgaris. It regulates keratinization and reduces formation of comedones. The standard strengths are 0.1% and 0.3%, delivered primarily as gels, creams, lotions, and microsphere formulations.
The main commercial segments are:
| Segment | Principal products | Typical channel | Commercial position |
|---|---|---|---|
| Adapalene 0.1% monotherapy | Differin Gel, generic adapalene | OTC, pharmacy, e-commerce | Largest volume segment |
| Adapalene 0.3% monotherapy | Differin 0.3%, generic products | Prescription and pharmacy | Higher-value niche |
| Adapalene 0.1%/benzoyl peroxide | Epiduo | Prescription | Combination therapy |
| Adapalene 0.3%/benzoyl peroxide | Epiduo Forte | Prescription | Premium combination product |
| Adapalene plus ancillary skin care | Cleansers, moisturizers, barrier products | Consumer and dermatology channels | Adjacent revenue opportunity |
The U.S. FDA approved Differin Gel 0.1% for nonprescription use in 2016, making it the first prescription-strength topical retinoid approved for OTC acne treatment in the United States (FDA, 2016).
How large is the adapalene market?
The global adapalene market is estimated at approximately $650 million to $850 million in 2024 on a retail-equivalent basis, including branded and generic monotherapy but excluding most broader acne products that do not contain adapalene. Including adapalene/benzoyl peroxide fixed-dose products increases the addressable category to approximately $900 million to $1.2 billion.
The market is difficult to measure because:
- Generic adapalene revenue is distributed across numerous manufacturers.
- OTC sales are recorded through retail, pharmacy, and online channels.
- Branded products are often reported within broader dermatology portfolios.
- Combination products may be reported separately from adapalene monotherapy.
- Country-level sales data are fragmented across prescription and consumer-health databases.
Estimated 2024 market split
| Product category | Estimated global share | Estimated 2024 sales |
|---|---|---|
| Generic adapalene 0.1% | 35%-45% | $230m-$380m |
| Branded adapalene 0.1% | 20%-30% | $130m-$250m |
| Adapalene 0.3% | 5%-10% | $35m-$80m |
| Adapalene/benzoyl peroxide | 25%-35% | $250m-$450m |
| Total adapalene-containing market | 100% | $650m-$1.2bn |
These estimates represent a commercial model rather than reported company revenue.
What are the projected adapalene sales through 2030?
The base-case forecast assumes continued global volume growth, modest price erosion, stable clinical demand, and gradual migration from branded OTC products to generics. The combination-product segment is expected to grow faster than monotherapy because of physician preference for multi-mechanism acne treatment and the convenience of once-daily fixed-dose therapy.
Global adapalene sales forecast
| Year | Monotherapy market | Combination market | Total adapalene-containing market |
|---|---|---|---|
| 2024 | $400m-$700m | $250m-$450m | $650m-$1.15bn |
| 2025 | $415m-$730m | $265m-$480m | $680m-$1.21bn |
| 2026 | $430m-$760m | $280m-$510m | $710m-$1.27bn |
| 2027 | $445m-$790m | $295m-$540m | $740m-$1.33bn |
| 2028 | $460m-$825m | $310m-$575m | $770m-$1.40bn |
| 2029 | $475m-$860m | $325m-$610m | $800m-$1.47bn |
| 2030 | $490m-$900m | $340m-$650m | $830m-$1.55bn |
The base-case implied CAGR is approximately 4%-5% from 2024 to 2030. The combination segment is modeled at approximately 5%-7% annual growth, while monotherapy grows at approximately 3%-4%.
Scenario analysis
| Scenario | 2030 global sales | Implied 2024-2030 CAGR | Main drivers |
|---|---|---|---|
| Downside | $650m-$950m | 0%-3% | Rapid generic price erosion, weak brand retention, limited market expansion |
| Base case | $830m-$1.55bn | 4%-5% | Stable acne prevalence, OTC demand, combination-product growth |
| Upside | $1.1bn-$1.9bn | 7%-9% | Strong e-commerce growth, emerging-market access, premium skincare adoption |
The most investable portion of the market is likely to remain combination therapy and differentiated delivery systems rather than standard adapalene 0.1% gel.
Which companies sell adapalene?
Galderma is the principal branded company associated with Differin and Epiduo in major markets. Generic manufacturers compete primarily on price, supply reliability, channel access, and formulation equivalence.
Key market participants
| Company or group | Main adapalene exposure | Competitive role |
|---|---|---|
| Galderma | Differin, Epiduo, Epiduo Forte | Branded dermatology and consumer health |
| Perrigo | OTC and generic topical products | Retail and store-brand distribution |
| Teva | Generic adapalene and topical dermatology | Generic prescription supply |
| Taro Pharmaceutical | Generic topical dermatology | U.S. and international generic supply |
| Viatris | Generic dermatology portfolio | Prescription and pharmacy channels |
| Sandoz | Generic topical products in selected markets | International generic competition |
| Regional manufacturers | Generic adapalene and combinations | China, India, Latin America, and other markets |
The competitive structure differs by country. In the United States, Differin benefits from consumer recognition and OTC availability. In prescription-led markets, generic substitution has a greater effect on price and market share.
How does Differin compare with generic adapalene?
Differin retains a brand premium, but that premium is constrained by therapeutic equivalence and the availability of low-cost generics.
| Factor | Differin | Generic adapalene |
|---|---|---|
| Active ingredient | Adapalene | Adapalene |
| Typical strength | 0.1% OTC; 0.3% prescription | 0.1% and 0.3% depending on market |
| Price | Premium | Low to moderate |
| Distribution | Retail, e-commerce, dermatology | Pharmacy and prescription channels |
| Consumer recognition | High in the United States | Low to moderate |
| Margin profile | Higher gross margin potential | Lower price and margin |
| Switching risk | High where substitution is permitted | Benefits from formulary and pharmacy substitution |
| Main advantage | Brand, packaging, consumer awareness | Price and reimbursement |
Differin's strongest commercial defense is brand visibility, not molecular exclusivity. Consumer advertising, pharmacy placement, skin-care positioning, and tolerability messaging support premium pricing.
What FDA regulatory status applies to adapalene?
Adapalene 0.1% gel is available OTC in the United States. Prescription products remain relevant for higher strengths and combination therapies.
U.S. regulatory milestones
| Product | Regulatory status |
|---|---|
| Differin Gel 0.1% | OTC acne treatment |
| Generic adapalene 0.1% gel | ANDA-based generic products |
| Adapalene 0.3% gel | Prescription product |
| Epiduo | Prescription fixed-dose combination |
| Epiduo Forte | Prescription fixed-dose combination |
The OTC switch expanded the patient base beyond dermatologist-treated populations. It also shifted part of the market toward retail and digital commerce, where consumer acquisition costs, retailer margins, and brand search rankings affect market share.
What patents protect adapalene products?
The adapalene molecule is mature, and commercial protection is concentrated in formulation, delivery, combination, and method-of-use claims rather than basic composition-of-matter rights.
Relevant IP categories include:
- Adapalene formulations with improved tolerability.
- Microsphere and controlled-release delivery.
- Combinations with benzoyl peroxide.
- Vehicles that improve dispersion or reduce irritation.
- Manufacturing processes and particle-size control.
- Packaging and stability systems.
- Methods for treating acne with specific concentrations or dosing schedules.
Core product patents associated with Differin and Epiduo have largely expired or reached the end of their primary commercial life in the United States. Current competitive barriers are more likely to arise from formulation patents, regulatory exclusivity, trademarks, manufacturing know-how, and channel control.
Patent and exclusivity risk
| IP category | Current commercial relevance |
|---|---|
| Adapalene composition-of-matter patent | Low; molecule is mature |
| Basic 0.1% gel patent | Low to moderate |
| Adapalene/benzoyl peroxide formulation patents | Moderate |
| Controlled-release or microsphere formulation | Moderate to high for specific products |
| Trademark protection | High for Differin and Epiduo branding |
| Manufacturing know-how | Moderate |
| Regulatory exclusivity | Limited for mature products |
Patent risk for a new generic adapalene product is generally lower than for a complex topical combination. FDA approval may still require substantial formulation, bioequivalence, and product-quality work because topical products can present locally acting bioequivalence challenges.
Are there Paragraph IV challenges to adapalene products?
Paragraph IV litigation risk is product-specific and depends on the patents listed for the relevant reference product at the time of an ANDA filing. The principal risk areas are branded combination products and complex topical formulations.
For standard adapalene 0.1% gel, generic entry has already occurred in the United States. The commercial question is therefore supply economics rather than first generic exclusivity. For adapalene/benzoyl peroxide products, an ANDA applicant may challenge formulation or method patents, seek a non-infringement position, or wait for listed patents to expire.
No broad, molecule-level Paragraph IV barrier is expected to prevent generic adapalene competition. Litigation exposure is more relevant to:
- Formulations using specialized vehicles.
- High-strength products.
- Fixed-dose combination products.
- Products with listed method-of-use patents.
- Formulations relying on nontraditional bioequivalence approaches.
What generic entry risks exist for branded adapalene?
Generic entry risk is high for conventional adapalene monotherapy and moderate to high for combination products.
Risk by product
| Product type | Generic entry risk | Pricing impact |
|---|---|---|
| Adapalene 0.1% gel | High | Significant |
| Adapalene 0.1% cream or lotion | High | Moderate to significant |
| Adapalene 0.3% gel | Moderate to high | Moderate |
| Adapalene/benzoyl peroxide gel | Moderate | Potentially significant |
| Microsphere or differentiated delivery | Moderate | Lower if clinically differentiated |
| Premium OTC brand | High substitution risk, but brand retention possible | Depends on consumer loyalty |
For a branded product, the most likely launch pattern is not an immediate collapse in all sales. Retail consumers may continue buying the brand, while prescription and pharmacy channels shift quickly to lower-cost alternatives. Combination products can preserve a larger premium when they offer convenience, tolerability, or formulary advantages.
Which geographic markets offer the strongest growth?
The United States is the largest commercially developed market for branded OTC adapalene. Western Europe is more fragmented because product classification, reimbursement, and prescription status vary by country. Asia-Pacific offers the strongest volume opportunity because of population size, increasing dermatology access, and expanding e-commerce.
Regional outlook
| Region | Market profile | 2024-2030 outlook |
|---|---|---|
| United States | Mature OTC and prescription market | Low to mid-single-digit growth |
| Western Europe | Fragmented regulatory and reimbursement environment | Low to mid-single-digit growth |
| China | Large consumer base, e-commerce-driven | Mid- to high-single-digit growth |
| India | Strong generic manufacturing and price competition | High volume, lower average price |
| Latin America | Prescription and pharmacy-led | Mid-single-digit growth |
| Middle East and Africa | Underpenetrated dermatology access | Higher growth from a smaller base |
China and India may produce the greatest unit growth, but average selling prices are likely to remain below U.S. and Western European levels. Local manufacturing can improve access while reducing branded-company pricing power.
How strong is the commercial patent estate for adapalene?
The patent estate is weak for the active ingredient and stronger for selected formulations. Brand owners can still protect economics through trademarks, retail execution, formulation complexity, and combination-product positioning.
A relative assessment is:
| Asset | Patent strength | Commercial defensibility |
|---|---|---|
| Generic adapalene 0.1% gel | Low | Low |
| Branded adapalene 0.1% OTC | Low to moderate | Moderate through brand |
| Adapalene 0.3% | Moderate | Moderate |
| Adapalene/benzoyl peroxide | Moderate | Moderate to high |
| Controlled-release adapalene | Moderate to high | Potentially high |
| New vehicle or irritation-reduction technology | Moderate to high | Depends on clinical differentiation |
Manufacturing barriers are meaningful for stable, homogeneous topical products but are unlikely to prevent competition indefinitely. The strongest barriers involve reproducible particle size, drug dispersion, preservative systems, packaging compatibility, and locally acting bioequivalence.
What licensing deals affect adapalene?
Adapalene has historically been commercialized through dermatology licensing, acquisition, and regional distribution arrangements rather than large current platform deals. The most important commercial relationship is the branded portfolio ownership and commercialization structure around Galderma's dermatology products.
Licensing value is likely to center on:
- Regional OTC rights.
- Dermatology portfolio distribution.
- Fixed-dose combination technology.
- Novel topical delivery platforms.
- Co-branding with acne-focused consumer-health companies.
A new licensing transaction involving adapalene alone would likely have limited strategic value unless it included a differentiated delivery system, combination product, or high-growth regional rights.
What revenue exposure does adapalene create for manufacturers?
Adapalene revenue is commercially relevant but generally not material as a standalone driver for diversified pharmaceutical companies. For Galderma, Differin and Epiduo contribute to the broader dermatology and aesthetics portfolio, but the company does not publicly disclose a standalone global adapalene revenue line.
Revenue exposure differs by business model:
- Branded OTC manufacturers have higher revenue per unit and greater marketing exposure.
- Generic manufacturers gain volume but face rapid price compression.
- Combination-product owners have higher value per prescription.
- Retailers benefit from repeat purchases and adjacent acne-care products.
- Contract manufacturers may gain stable volume without brand risk.
The most attractive economics are likely in premium combinations, differentiated vehicles, and integrated acne-care regimens rather than commodity adapalene gel.
What are the most likely generic launch scenarios?
Scenario 1: Standard generic substitution
Generic adapalene captures prescription volume rapidly, while the branded OTC product retains a portion of consumer sales through recognition and convenience. Net prices decline, but the category expands modestly.
Scenario 2: Combination-product erosion
Generic adapalene/benzoyl peroxide products enter after patent and regulatory barriers are addressed. The branded combination loses formulary share, but physician demand maintains a premium segment.
Scenario 3: Premium formulation defense
A brand owner emphasizes reduced irritation, improved tolerability, or enhanced cosmetic properties. The product maintains a higher price despite generic availability, provided the benefit is visible to consumers or supported by clinical data.
Scenario 4: Emerging-market volume expansion
Generic manufacturers drive increased access in China, India, Latin America, and other markets. Unit sales grow faster than revenue because of lower prices.
Key Takeaways
- The global adapalene-containing market is estimated at $650 million to $1.2 billion in 2024.
- A base-case forecast places 2030 sales at approximately $830 million to $1.55 billion.
- Expected market growth is approximately 4%-5% annually through 2030.
- Generic adapalene 0.1% is the largest volume segment and has high price pressure.
- Combination products such as Epiduo and Epiduo Forte offer better commercial defensibility than standard monotherapy.
- Differin's principal advantages are OTC access, brand recognition, retail distribution, and consumer marketing.
- The active ingredient has limited remaining exclusivity value; formulation, combination, trademark, and manufacturing rights are more relevant.
- The United States remains the most developed branded market, while Asia-Pacific offers the strongest unit-growth opportunity.
- Standard generic entry is already established in the United States. Future litigation risk is concentrated in complex topical and fixed-dose products.
- The main growth opportunity is premium, tolerable, convenient topical therapy rather than undifferentiated adapalene gel.
FAQs About Adapalene Market Size and Sales
Is adapalene a billion-dollar drug?
The combined global market for adapalene monotherapy and adapalene-containing combinations may approach or exceed $1 billion on a retail-equivalent basis, but no company publicly reports adapalene as a standalone billion-dollar product.
Does Differin still have pricing power after generic entry?
Yes, but mainly in OTC retail and e-commerce channels. Prescription and pharmacy channels are more exposed to generic substitution and reimbursement pressure.
Is adapalene more commercially attractive than tretinoin?
Adapalene has stronger OTC and consumer-health positioning, while tretinoin has broader dermatology use and greater formulation diversity. Adapalene is generally more exposed to generic price competition.
Can a new adapalene formulation obtain meaningful market exclusivity?
A new formulation may obtain patent protection and regulatory differentiation if it improves tolerability, delivery, stability, or adherence. The commercial value depends on whether the benefit is clinically demonstrable and difficult to replicate.
What is the highest-growth adapalene product segment?
Adapalene/benzoyl peroxide combinations and differentiated topical delivery systems are expected to grow faster than conventional adapalene 0.1% gel, particularly in markets with expanding dermatology access.
References
- U.S. Food and Drug Administration. (2016). FDA approves first over-the-counter topical acne treatment. https://www.fda.gov
- U.S. Food and Drug Administration. (2023). Differin adapalene gel 0.1% label. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2023). Epiduo and Epiduo Forte prescribing information. https://www.accessdata.fda.gov
- Galderma. (2024). Annual report and company information. https://www.galderma.com
- American Academy of Dermatology. (2016). Guidelines of care for the management of acne vulgaris. Journal of the American Academy of Dermatology.
More… ↓
