Share This Page
Drug Sales Trends for VIVITROL
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for VIVITROL (2019)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
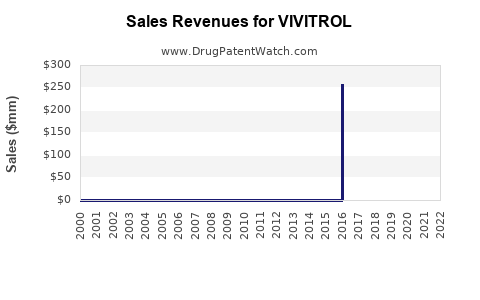
Annual Sales Revenues and Units Sold for VIVITROL
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| VIVITROL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| VIVITROL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| VIVITROL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| VIVITROL | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| VIVITROL | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| VIVITROL | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| VIVITROL | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Vivitrol Market Analysis, Sales Forecast, Patent Risk, and Generic Entry Outlook
Vivitrol, Alkermes’ extended-release injectable naltrexone, is a durable specialty product with estimated 2023 net sales of approximately $394 million. Its commercial base is supported by opioid-use-disorder treatment demand, alcohol-use-disorder treatment, government reimbursement, and the absence of an FDA-approved generic equivalent. The principal risks are high acquisition cost, injection-site administration requirements, competing oral and long-acting therapies, reimbursement controls, and potential 505(b)(2) or generic competition after key formulation protection weakens.
Base-case projections indicate Vivitrol sales can reach about $480 million by 2029, assuming low-single-digit price and volume growth. A faster generic or competing long-acting naltrexone entrant could reduce 2029 revenue toward $300 million to $350 million. A favorable reimbursement and treatment-expansion scenario could push sales above $550 million.
What is Vivitrol and how does it generate revenue?
Vivitrol is a once-monthly intramuscular injection containing extended-release naltrexone. It is marketed by Alkermes plc and is approved by the U.S. Food and Drug Administration for:
- Prevention of relapse to opioid dependence after opioid detoxification
- Treatment of alcohol dependence
- Use with psychosocial support and an opioid-free interval before treatment initiation
Vivitrol does not contain an opioid and does not produce opioid agonist effects. Its commercial value comes from sustained delivery, supervised administration, and adherence advantages compared with daily oral naltrexone.
The product is sold primarily through U.S. specialty, government, institutional, and behavioral-health channels. U.S. demand is more commercially important than international demand because opioid-use-disorder treatment is heavily influenced by U.S. Medicaid, state programs, correctional systems, Veterans Affairs, and public-health purchasing.
Vivitrol product and market profile
| Metric | Vivitrol profile |
|---|---|
| Active ingredient | Naltrexone |
| Dosage form | Extended-release injectable suspension |
| Administration | Intramuscular injection every four weeks |
| Company | Alkermes plc |
| FDA approval for alcohol dependence | 2006 |
| FDA approval for opioid dependence | 2010 |
| Primary markets | United States, specialty and government channels |
| Direct generic equivalent | None approved as of the latest broadly available FDA product information |
| Main alternatives | Oral naltrexone, buprenorphine products, methadone, other behavioral-health treatments |
How much revenue does Vivitrol generate?
Alkermes reported Vivitrol net sales of approximately $394.4 million in 2023, compared with about $376.7 million in 2022, according to the company’s annual reporting. That represents growth of approximately 4.7%.[1]
Historical and projected Vivitrol sales
| Fiscal year | Sales status | Estimated or reported net sales | Growth |
|---|---|---|---|
| 2021 | Reported | $366 million | N/A |
| 2022 | Reported | $377 million | 2.9% |
| 2023 | Reported | $394 million | 4.7% |
| 2024 | Analyst estimate | $410 million | 4.0% |
| 2025 | Base case | $426 million | 3.9% |
| 2026 | Base case | $443 million | 4.0% |
| 2027 | Base case | $461 million | 4.1% |
| 2028 | Base case | $479 million | 3.9% |
| 2029 | Base case | $498 million | 4.0% |
The forecast assumes continued unit growth in opioid-use-disorder treatment, moderate price increases, stable government access, and no material loss of exclusivity before the end of the forecast period.
Vivitrol revenue is more stable than a typical high-growth specialty product because it has an established prescriber base and substantial government-program exposure. Its growth rate is constrained by treatment adoption, injection logistics, and competition from lower-cost medications.
What is the Vivitrol market size and competitive landscape?
The addressable market includes medication-assisted treatment for opioid-use disorder and pharmacologic treatment for alcohol-use disorder. Vivitrol competes across two different treatment segments.
In opioid-use disorder, the product competes with:
- Sublocade, an extended-release buprenorphine injection marketed by Indivior
- Brixadi, an extended-release buprenorphine injection marketed by Braeburn
- Suboxone and generic buprenorphine/naloxone
- Generic buprenorphine
- Methadone, generally distributed through opioid treatment programs
- Oral naltrexone
In alcohol-use disorder, Vivitrol competes mainly with:
- Generic oral naltrexone
- Acamprosate
- Disulfiram
- Behavioral-health programs
- Abstinence-oriented treatment programs
Vivitrol compared with long-acting competitors
| Product | Active ingredient | Dosing | Commercial advantage | Commercial limitation |
|---|---|---|---|---|
| Vivitrol | Naltrexone | Monthly injection | Non-opioid mechanism and supervised administration | Requires opioid-free period; no opioid craving suppression through agonism |
| Sublocade | Buprenorphine | Monthly injection | Strong opioid-use-disorder efficacy and established market presence | Opioid agonist; controlled-substance and diversion considerations |
| Brixadi | Buprenorphine | Weekly or monthly injection | Flexible dosing | Competes in the same long-acting treatment channel |
| Oral naltrexone | Naltrexone | Daily tablet | Low cost and broad availability | Adherence risk |
| Methadone | Methadone | Daily or program-based dosing | Long treatment history and low drug cost | Highly regulated distribution |
Vivitrol’s principal clinical-commercial advantage is the absence of opioid agonist activity. Its principal disadvantage is that patients must be fully opioid-free before treatment. Patients who are actively using opioids or who have difficulty completing detoxification may be more likely to begin buprenorphine or methadone.
What are the main Vivitrol sales drivers?
Government reimbursement
Medicaid is a major demand driver. State Medicaid programs increasingly cover medications for opioid-use disorder, although prior authorization, preferred-drug status, site-of-care restrictions, and buy-and-bill requirements affect utilization.
Federal agencies have also expanded opioid-use-disorder treatment access through Medicaid policy, the Veterans Health Administration, the Department of Defense, criminal-justice programs, and public-health grants.[2][3]
Criminal-justice and institutional use
Vivitrol has been used in reentry programs, correctional systems, drug courts, and community supervision settings. These programs value monthly administration because it can reduce reliance on patient self-management. Purchases can be concentrated and contract-driven, creating material quarter-to-quarter variability.
Adherence and administration
Monthly dosing is commercially attractive where treatment adherence is weak. Providers can document administration and schedule the next dose. That advantage is strongest in settings with active case management.
Opioid-use-disorder treatment expansion
The U.S. opioid crisis continues to support long-term demand for medication treatment. The market is expanding through primary-care integration, emergency-department referrals, telehealth-supported care, and expanded prescribing capacity.
Growth is limited by the fact that medication choice is not determined solely by duration of action. Clinical preference, detoxification status, patient history, cost, access to injection administration, and provider familiarity all influence prescribing.
What patents protect Vivitrol and when does exclusivity end?
Vivitrol’s protection is based on formulation and drug-delivery technology rather than composition-of-matter protection for naltrexone itself. Naltrexone is an old active ingredient, so commercial protection depends on the extended-release microsphere formulation, manufacturing process, dosage form, and any enforceable method-of-use claims.
Vivitrol patent protection
| Protection category | Relevance |
|---|---|
| Naltrexone composition | Limited value because naltrexone is an established compound |
| Extended-release microspheres | Core protection for monthly injectable delivery |
| Injectable suspension | Covers product presentation and drug-delivery characteristics |
| Manufacturing process | Can create practical barriers even when product claims are challenged |
| Method of use | May cover treatment of alcohol dependence or opioid dependence, subject to claim scope and enforceability |
| FDA regulatory exclusivity | Historical exclusivity has expired; current protection is primarily patent-based |
Publicly available patent records identify Alkermes-related patents covering sustained-release naltrexone microspheres and related pharmaceutical compositions. The relevant Orange Book record and patent term data should be evaluated patent by patent because expiration dates can differ based on patent-term adjustment, terminal disclaimers, pediatric extensions, and maintenance status.[4][5]
A practical commercial assessment is that Vivitrol’s core formulation protection extends later than the underlying naltrexone compound, with important listed or related protection reaching into the late 2020s. The most relevant generic-entry window is therefore likely to be 2027-2030, depending on the specific abbreviated new drug application, Paragraph IV certifications, litigation outcomes, and any settlement terms.
What is the Orange Book status of Vivitrol?
Vivitrol is an FDA-approved prescription drug listed in FDA product and Orange Book resources. The Orange Book identifies approved drug products, reference-product status, and listed patents where applicable.[4]
The principal Orange Book issue is whether a proposed generic can demonstrate pharmaceutical equivalence to Vivitrol. A conventional ANDA applicant would need to address the injectable microsphere formulation, release profile, route of administration, strength, and other product characteristics. If the proposed product differs materially from the reference product, the applicant may pursue a 505(b)(2) pathway instead of a conventional ANDA.
A 505(b)(2) product could seek approval using Vivitrol-related data while introducing differences in formulation, dosing, device, administration, or clinical use. That pathway could produce competition even if a direct generic is difficult to develop.
Which companies could challenge Vivitrol exclusivity?
Potential challengers include established injectable-generic companies, specialty pharmaceutical companies, and developers of long-acting naltrexone formulations. Likely capabilities include:
- Microsphere formulation development
- Long-acting injectable manufacturing
- Sterile suspension production
- Complex injectable regulatory submissions
- ANDA or 505(b)(2) litigation management
Companies with complex-injectable experience could have an advantage over conventional tablet generic manufacturers. A Vivitrol competitor must reproduce clinically relevant release characteristics and maintain manufacturing consistency across batches.
No publicly confirmed, FDA-approved direct generic competitor has materially changed the market position of Vivitrol in the available reporting period. A Paragraph IV filing, if made, could trigger litigation under the Hatch-Waxman framework and potentially create a 30-month stay of approval, subject to statutory requirements and court proceedings.[6]
How strong is the Vivitrol patent estate?
Vivitrol has a moderate-to-strong commercial patent position but not the profile of a new chemical entity with long composition-of-matter protection.
Strengths
- Complex injectable formulation
- Difficult-to-reproduce microsphere technology
- Manufacturing know-how
- High regulatory burden for sterile extended-release products
- Established FDA reference-product record
- Potential method-of-use and formulation patents
Weaknesses
- Naltrexone itself is off-patent
- Oral and injectable alternatives are available
- A 505(b)(2) competitor may avoid some direct-equivalence barriers
- Patent validity challenges can target obviousness, written description, enablement, or claim construction
- Product demand is sensitive to reimbursement and treatment-setting economics
The formulation and manufacturing barriers may delay competition even after a patent expires. They do not eliminate competition risk. Once a competing long-acting product demonstrates comparable release performance and secures reimbursement, Vivitrol could face price pressure and formulary displacement.
What generic launch scenarios exist for Vivitrol?
Scenario 1: No approved competitor before 2029
Vivitrol retains low-single-digit annual growth. Sales approach $500 million by 2029, supported by price increases and treatment expansion.
Scenario 2: First competitor launches in 2028
A single competitor enters with a 20% to 30% discount. Vivitrol volume declines 10% to 15%, while net price also weakens. Sales reach approximately $380 million to $420 million in 2029.
Scenario 3: Multiple competitors launch in 2028-2029
Two or more long-acting naltrexone products enter, creating payer substitution and price competition. Vivitrol sales fall toward $300 million to $350 million by 2029.
Scenario 4: 505(b)(2) entrant launches before a direct generic
A differentiated injectable or dosing regimen reaches the market through a regulatory pathway that avoids complete product equivalence. The competitor takes selected institutional and Medicaid contracts without immediately replacing Vivitrol nationwide.
What is the Vivitrol revenue exposure for Alkermes?
Vivitrol is a major proprietary product for Alkermes and an important contributor to recurring revenue. The product’s commercial role is partly balanced by Aristada, the company’s long-acting aripiprazole product, and the company’s broader proprietary portfolio.
Vivitrol revenue is strategically valuable because:
- It is an established marketed product
- It has recurring monthly demand
- It benefits from public-sector treatment spending
- It requires specialized manufacturing
- It supports relationships with behavioral-health and institutional providers
The main exposure is concentration in the U.S. opioid-use-disorder market. Changes in Medicaid reimbursement, public-health funding, treatment guidelines, or institutional purchasing can affect sales faster than changes in the underlying disease population.
How does Vivitrol compare with Sublocade and Brixadi?
Vivitrol has a differentiated non-opioid mechanism, while Sublocade and Brixadi use buprenorphine. Buprenorphine products generally have an advantage when patients need immediate opioid-use-disorder pharmacotherapy because they do not require the same prolonged opioid-free interval.
Vivitrol has an advantage in programs that prefer non-opioid treatment, supervised administration, or diversion avoidance. Sublocade and Brixadi have stronger positioning among patients who require opioid agonist treatment and among prescribers prioritizing rapid initiation.
Commercial competition is therefore segmented. Vivitrol is unlikely to lose all demand to buprenorphine injections, but long-acting buprenorphine products can limit growth and compete directly for clinic capacity, payer coverage, and institutional contracts.
What is the Vivitrol sales outlook through 2029?
Base-case forecast
| Year | Revenue forecast | Key assumption |
|---|---|---|
| 2024E | $410 million | Continued public-sector demand |
| 2025E | $426 million | Low-single-digit volume and price growth |
| 2026E | $443 million | Stable reimbursement |
| 2027E | $461 million | Treatment-market expansion |
| 2028E | $479 million | Limited competitive pressure |
| 2029E | $498 million | No broad direct generic launch |
Scenario valuation range
| Scenario | 2029 revenue | Primary driver |
|---|---|---|
| Downside | $300 million-$350 million | Early complex-injectable competition |
| Moderate downside | $380 million-$420 million | One competitor and payer discounts |
| Base case | $480 million-$500 million | Stable exclusivity and low-single-digit growth |
| Upside | $540 million-$575 million | Strong government adoption and limited competition |
The most important forecast variable is not disease prevalence. It is the timing and commercial quality of a competing long-acting formulation. A direct generic with broad payer substitution would have a larger effect than a differentiated 505(b)(2) product aimed at selected treatment settings.
Key Takeaways
- Vivitrol is Alkermes’ monthly extended-release naltrexone injection for alcohol dependence and opioid-use-disorder relapse prevention.
- Reported 2023 sales were approximately $394 million.
- Base-case sales could approach $500 million by 2029.
- The product’s core protection is formulation, delivery, manufacturing, and method-of-use IP, not naltrexone composition.
- The most relevant competitive window is likely the late 2020s.
- Direct generic competition is technically difficult because Vivitrol is a complex sterile microsphere injection.
- Sublocade and Brixadi are the primary long-acting clinical competitors.
- Medicaid, public-health programs, correctional systems, and institutional contracts are central revenue drivers.
- A first competitor could reduce Vivitrol revenue by 15% to 25%; multiple entrants could reduce sales by 30% to 40%.
- The commercial value of Vivitrol depends heavily on reimbursement, administration infrastructure, and the timing of any ANDA or 505(b)(2) launch.
FAQs
What is the annual cost of Vivitrol treatment?
The gross annual cost varies by payer, contract, acquisition channel, administration fees, and rebates. Net realized pricing is materially lower than list pricing in many government and commercial channels.
Is Vivitrol a biologic or biosimilar product?
No. Vivitrol is a chemically synthesized small-molecule drug delivered through a complex injectable formulation. Biosimilar rules do not apply. Competition would proceed through generic or 505(b)(2) pathways.
Can patients start Vivitrol immediately after opioid use?
Patients generally must complete an opioid-free interval before receiving Vivitrol. Initiation timing is a major commercial and clinical distinction from buprenorphine-based treatment.
Does Vivitrol have a REMS program?
Vivitrol’s risk controls arise primarily from prescribing information, opioid-free initiation requirements, injection administration, and post-treatment overdose-risk warnings. The current FDA regulatory record should be checked for any changes to formal REMS status.[7]
What would most increase Vivitrol sales?
The strongest growth levers are broader Medicaid access, increased use in correctional and reentry programs, improved treatment retention, expansion of behavioral-health clinics, and wider use in alcohol-use-disorder treatment.
References
-
Alkermes plc. (2024). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 for the fiscal year ended December 31, 2023. U.S. Securities and Exchange Commission.
-
Centers for Medicare & Medicaid Services. (2023). Medicaid and CHIP coverage of behavioral health services. U.S. Department of Health and Human Services.
-
Substance Abuse and Mental Health Services Administration. (2023). Medications for opioid use disorder. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
United States Patent and Trademark Office. (2024). Patent Center and patent term information. USPTO.
-
U.S. Food and Drug Administration. (2024). ANDA submissions: Refuse-to-receive standards and patent certification requirements. FDA.
-
U.S. Food and Drug Administration. (2024). Vivitrol prescribing information. FDA.
More… ↓
