Share This Page
Drug Sales Trends for NITROFURANTOIN
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for NITROFURANTOIN (2019)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
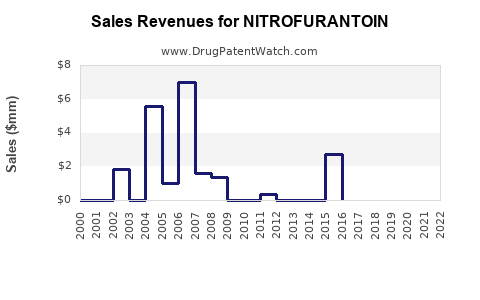
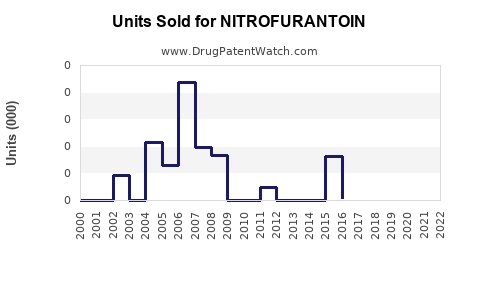
Annual Sales Revenues and Units Sold for NITROFURANTOIN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| NITROFURANTOIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| NITROFURANTOIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| NITROFURANTOIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| NITROFURANTOIN | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| NITROFURANTOIN | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| NITROFURANTOIN | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Nitrofurantoin Market Analysis, Sales Projections, Patent Status, and Generic Competition
Nitrofurantoin is a mature, low-cost urinary anti-infective with durable demand from uncomplicated urinary tract infection treatment. The market is dominated by generic manufacturers, while branded products such as Macrobid and Macrodantin have limited strategic relevance. Growth is driven by prescription volume, recurrent UTI treatment, antimicrobial stewardship, and resistance patterns rather than pricing power.
A modeled global nitrofurantoin market is estimated at approximately $1.0 billion to $1.3 billion in 2024 sales, including immediate-release and extended-release oral products. Under a base case, the market could reach $1.3 billion to $1.6 billion by 2029, representing an estimated compound annual growth rate of 4% to 6%. The range reflects uncertainty in public market data, country coverage, hospital tender pricing, and the separation of nitrofurantoin revenue from broader UTI drug categories.
What is nitrofurantoin and how is it used?
Nitrofurantoin is an oral antibacterial drug used primarily for acute uncomplicated cystitis and, in selected cases, prevention of recurrent lower urinary tract infections. It is not generally appropriate for pyelonephritis or systemic infections because therapeutic concentrations are not reliably achieved in renal tissue or plasma.
The main commercial products are:
| Product type | Active ingredient | Common use | Commercial status |
|---|---|---|---|
| Nitrofurantoin monohydrate/macrocrystals | Nitrofurantoin | Acute uncomplicated cystitis | Generic and branded |
| Nitrofurantoin macrocrystals | Nitrofurantoin | Acute cystitis and selected prophylaxis | Generic and branded |
| Macrobid | Nitrofurantoin monohydrate/macrocrystals | Twice-daily acute cystitis treatment | Legacy brand and generics |
| Macrodantin | Nitrofurantoin macrocrystals | Acute cystitis and prophylaxis | Legacy brand and generics |
The monohydrate/macrocrystals formulation is commercially important because its twice-daily dosing supports adherence compared with more frequent macrocrystal dosing. FDA labeling identifies nitrofurantoin for lower urinary tract infection caused by susceptible organisms, including certain strains of Escherichia coli, Enterobacter species, Klebsiella species, Enterococcus species, and Staphylococcus saprophyticus.[1]
How large is the nitrofurantoin market?
The market is fragmented and predominantly generic. No single manufacturer controls global sales, and public company disclosures usually aggregate nitrofurantoin into broader generic pharmaceutical revenue.
Modeled 2024 market by region
| Region | Estimated 2024 sales | Share of global market | Market characteristics |
|---|---|---|---|
| United States | $400 million-$550 million | 35%-45% | High prescription volume, multiple ANDA holders, commercial and Medicaid demand |
| Europe | $250 million-$350 million | 20%-30% | Country-specific reimbursement and tender pricing |
| Asia-Pacific | $180 million-$280 million | 15%-25% | Large patient population, lower average price, variable regulatory access |
| Latin America | $70 million-$120 million | 5%-10% | Private-pay and public procurement markets |
| Middle East and Africa | $40 million-$80 million | 3%-7% | Smaller formal market and uneven availability |
| Global total | $1.0 billion-$1.3 billion | 100% | Modeled product market |
These figures are analytical estimates rather than audited manufacturer sales. The largest source of uncertainty is the treatment of combination products, hospital procurement, private-label products, and country-level products sold under local brand names.
The United States is likely the most commercially attractive market because of prescription volume, relatively high generic reimbursement, and broad use of nitrofurantoin for uncomplicated cystitis. Unit growth is likely to exceed revenue growth because price competition continues after generic entry.
What are the nitrofurantoin sales projections through 2029?
The base case assumes continued use in uncomplicated cystitis, stable clinical preference where local susceptibility supports treatment, moderate growth in diagnosed UTIs, and annual generic price erosion of approximately 2% to 4% in mature markets.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $1.0B | $1.15B | $1.3B |
| 2025 | $1.02B | $1.20B | $1.37B |
| 2026 | $1.04B | $1.26B | $1.45B |
| 2027 | $1.06B | $1.32B | $1.54B |
| 2028 | $1.08B | $1.39B | $1.64B |
| 2029 | $1.10B | $1.46B | $1.75B |
| 2024-2029 CAGR | 1.9% | 4.9% | 6.1% |
The base-case revenue increase depends on volume growth of approximately 6% to 8% annually, offset by generic price declines. In the United States, revenue growth could be lower than prescription growth because additional ANDA suppliers and pharmacy purchasing consolidation reduce net price.
Key sales-growth drivers
- Rising diagnosis and treatment of uncomplicated cystitis.
- Continued antimicrobial stewardship favoring narrow-spectrum urinary agents when clinically appropriate.
- Use in recurrent UTI prophylaxis in selected patients.
- Increased generic access in emerging markets.
- Relatively low resistance to nitrofurantoin among common urinary pathogens in many markets.
- Expansion of retail and mail-order pharmacy dispensing.
Key sales constraints
- Low unit prices and limited brand differentiation.
- Renal-function restrictions and safety concerns in selected patients.
- Inappropriate use for pyelonephritis or systemic infection.
- Substitution by fosfomycin, trimethoprim-sulfamethoxazole, pivmecillinam, and fluoroquinolones where appropriate.
- Generic price erosion and procurement concentration.
- Local resistance patterns that may limit use in specific geographies.
What is the FDA regulatory status of nitrofurantoin?
Nitrofurantoin is an FDA-approved prescription antibacterial available through multiple abbreviated new drug applications. The FDA-approved products include both macrocrystal and monohydrate/macrocrystal dosage forms.
The main regulatory considerations are:
| Regulatory issue | Assessment |
|---|---|
| FDA approval | Established prescription drug with multiple generic approvals |
| Regulatory pathway | ANDA approval for therapeutically equivalent products |
| Reference products | Legacy nitrofurantoin products, including Macrobid and Macrodantin |
| Prescription status | Prescription-only |
| Therapeutic equivalence | Product-specific FDA Orange Book ratings |
| Pediatric use | Label-dependent; dosing and age limitations apply |
| Renal impairment | Important prescribing restriction |
| Major safety concerns | Pulmonary, hepatic, neurologic, and hemolytic adverse reactions |
Nitrofurantoin is primarily a retail pharmacy product. It does not have the manufacturing complexity of an injectable antibiotic or biologic. Regulatory competition is therefore more dependent on bioequivalence, supply reliability, manufacturing compliance, and commercial contracting than on clinical differentiation.
What is the Orange Book status of nitrofurantoin?
Nitrofurantoin has an established Orange Book presence through reference listed drugs and multiple generic equivalents. The relevant products are generally marketed under ANDAs rather than protected by active composition-of-matter patents.
Orange Book considerations include:
- Therapeutic-equivalence ratings for approved generic products.
- Separate product records for macrocrystal and monohydrate/macrocrystal formulations.
- Product-specific labeling and dosage-form requirements.
- Possible differences in listed reference products and strengths.
- Limited commercial impact from legacy brand listings because generic substitution is widespread.
Because nitrofurantoin was discovered and commercialized decades ago, the original composition-of-matter and formulation exclusivity periods have expired. Current market access does not depend on a live pioneering patent estate.
What patents protect nitrofurantoin products?
No commercially meaningful composition-of-matter patent protection remains for nitrofurantoin. The drug is a legacy small molecule with generic competition in the United States and other major markets.
Patent protection assessment
| Patent category | Current commercial relevance |
|---|---|
| Composition-of-matter patents | Expired |
| Original product patents | Expired |
| Core antibacterial mechanism patents | Not applicable to market exclusivity |
| Macrocrystal formulation patents | Legacy protection expired or commercially immaterial |
| Monohydrate/macrocrystal formulation patents | Any relevant legacy protection has expired or does not prevent generic access |
| Method-of-use patents | No broad, commercially blocking patent identified for ordinary cystitis treatment |
| Manufacturing-process patents | May exist at supplier level but generally do not block finished-dose competition |
| Device or delivery patents | Not material for standard oral capsules or tablets |
Current competitive barriers are operational rather than patent-based. These include formulation consistency, dissolution performance, impurity control, validated manufacturing processes, drug-shortage risk, and the ability to meet FDA current good manufacturing practice requirements.
Are there Paragraph IV challenges involving nitrofurantoin?
Nitrofurantoin has experienced generic entry through the standard ANDA framework, but current market dynamics are not defined by an active, high-value Paragraph IV patent dispute.
A Paragraph IV certification is relevant when an ANDA applicant asserts that a listed patent is invalid, unenforceable, or not infringed. For legacy nitrofurantoin products, the principal patent barriers have expired. Any historical Paragraph IV litigation would have had greater relevance during earlier generic-entry periods than in the current market.
The practical conclusion is that a new nitrofurantoin applicant would face commercial competition from existing ANDA holders rather than a dominant patent owner defending current exclusivity.
When did nitrofurantoin lose exclusivity?
Nitrofurantoin lost meaningful market exclusivity decades ago. The relevant commercial exclusivity periods ended long before the current generic market was established.
There is no current New Chemical Entity exclusivity, orphan-drug exclusivity, pediatric exclusivity, or first-to-file exclusivity that materially protects the overall nitrofurantoin market. Any limited exclusivity attached to a particular new generic product would be product-specific and would not restore broad market protection for the active ingredient.
What formulations are protected by nitrofurantoin patents?
The principal commercial formulations are macrocrystals and monohydrate/macrocrystals. Their historical formulation and product patents do not create a current barrier to generic substitution.
The formulation still matters commercially because it affects:
- Dosing frequency.
- Gastrointestinal tolerability.
- Bioequivalence requirements.
- Manufacturing complexity.
- Product positioning in retail pharmacy.
- Prescriber preference for twice-daily therapy.
The monohydrate/macrocrystal product has stronger commercial recognition through the Macrobid brand, but this recognition does not provide material patent protection. Generic manufacturers compete on FDA therapeutic equivalence, availability, contract pricing, and pharmacy substitution.
How does nitrofurantoin compare with competing UTI drugs?
| Drug | Main advantage | Main limitation | Competitive effect on nitrofurantoin |
|---|---|---|---|
| Nitrofurantoin | Narrow urinary activity and low cost | Not suitable for pyelonephritis; renal restrictions | Baseline first-line competitor |
| Fosfomycin | Single-dose option in many markets | Higher cost and variable susceptibility | Substitution in adherence-sensitive cases |
| Trimethoprim-sulfamethoxazole | Low cost and familiar use | Resistance and allergy concerns | Strong alternative where susceptibility is favorable |
| Pivmecillinam | Guideline-supported option in certain markets | Geographic availability | Limits growth in Europe and selected markets |
| Fluoroquinolones | Systemic tissue penetration | Safety and stewardship restrictions | Used when broader tissue penetration is needed |
| Beta-lactams | Broad prescribing familiarity | Often lower efficacy for uncomplicated cystitis | Alternative when first-line agents are unsuitable |
Nitrofurantoin is positioned most strongly in uncomplicated lower UTI treatment. It is less competitive in complicated infections, upper-tract infections, severe renal impairment, and situations requiring systemic antibacterial exposure.
Which companies compete in the nitrofurantoin market?
The market includes branded-product owners, generic manufacturers, specialty pharmaceutical companies, contract manufacturers, and regional distributors. Competitive participation varies by country and dosage form.
In the United States, the relevant competitor set typically includes manufacturers with approved ANDAs for nitrofurantoin macrocrystals or monohydrate/macrocrystals. Generic portfolios may change through acquisitions, discontinuations, supply interruptions, or changes in wholesaler contracts.
The strongest commercial positions generally belong to companies with:
- Multiple approved strengths and dosage forms.
- Reliable API sourcing.
- Established retail-pharmacy distribution.
- National wholesaler contracts.
- FDA-compliant manufacturing capacity.
- The ability to sustain low margins during price competition.
Brand owners retain limited pricing power. A generic manufacturer with a single product and no distribution scale may face lower profitability even if regulatory approval is obtained.
What is the patent strength of the nitrofurantoin estate?
The patent estate is weak for purposes of blocking generic entry and weak for supporting premium pricing. Nitrofurantoin has high regulatory maturity but low remaining exclusivity value.
Patent-strength score
| Factor | Score | Assessment |
|---|---|---|
| Composition-of-matter protection | 0/5 | Expired |
| Core formulation protection | 1/5 | Historical protection does not materially block entry |
| Method-of-use protection | 0/5 | No broad blocking indication patent |
| Manufacturing protection | 1/5 | Process know-how may support quality but not market exclusivity |
| Brand differentiation | 1/5 | Limited by generic substitution |
| Generic entry resistance | 1/5 | Multiple suppliers and mature regulatory pathway |
| Overall patent strength | 1/5 | Commercially weak |
The relevant intellectual-property value is therefore concentrated in process know-how, supplier relationships, quality systems, and market access rather than enforceable exclusivity.
What generic launch scenarios exist for nitrofurantoin?
A new generic entrant could pursue three principal strategies.
Standard ANDA launch
The most direct route is an ANDA for an established dosage form and strength. This route has the lowest technical risk but the highest risk of price competition. A new entrant would need efficient manufacturing and sufficient distribution scale.
Formulation or dosage-form differentiation
A company could pursue modified-release, improved tolerability, or an alternative dosage form. This strategy may support higher pricing but increases formulation, bioequivalence, clinical, and regulatory risk. Any new intellectual property would need to withstand obviousness and enablement challenges.
Geographic expansion
Manufacturers with existing FDA or European regulatory infrastructure could expand into markets where nitrofurantoin availability is limited. The main risks are local registration requirements, reimbursement restrictions, API sourcing, and fragmented distribution.
A new U.S. entrant should expect rapid price compression unless it has a differentiated supply position, an underserved strength, or a commercial agreement with a large pharmacy or wholesaler.
What litigation and settlement issues affect nitrofurantoin?
Current market value is unlikely to be affected by major patent litigation. The more relevant legal and regulatory risks are:
- Product-liability claims involving pulmonary or hepatic toxicity.
- Manufacturing-defect claims.
- FDA warning letters or manufacturing restrictions.
- Antitrust scrutiny of generic pricing or supply arrangements.
- Contract disputes involving wholesalers and pharmacy benefit managers.
- Drug-shortage investigations if production is concentrated.
Historical settlements involving legacy brand and generic entry may have influenced earlier market access, but they do not appear to create current broad exclusivity for nitrofurantoin.
What is the revenue exposure for manufacturers?
Nitrofurantoin is usually a small product within a generic company’s portfolio, but its revenue can be strategically useful because demand is recurring and linked to a high-volume outpatient condition.
Revenue exposure depends on:
- Number of approved strengths.
- Share of monohydrate/macrocrystal versus macrocrystal products.
- Net price after rebates and wholesaler discounts.
- Government versus commercial payer mix.
- Manufacturing concentration.
- API cost and supply reliability.
- Volume from retail, mail-order, and institutional channels.
A manufacturer with 10% of a modeled $450 million U.S. market would have gross sales exposure of approximately $45 million before rebates, returns, and channel discounts. Net revenue could be materially lower. The same share in a low-price European tender market may generate lower revenue despite similar unit volume.
What are the principal manufacturing and IP barriers?
Nitrofurantoin is easier to manufacture than sterile anti-infectives, but quality execution remains important. The main barriers include:
- Consistent particle-size distribution.
- Control of polymorphic or solid-state properties.
- Uniform content and dissolution.
- Impurity and degradation-product control.
- Reliable nitrofurantoin API supply.
- Bioequivalence performance for modified or combined formulations.
- Compliance with FDA and European good manufacturing practice standards.
These barriers can delay approval or create supply interruptions, but they do not provide durable exclusivity unless protected by a valid, enforceable patent. Manufacturing know-how may improve margins without preventing competitor entry.
How does nitrofurantoin compare with other mature generic antibiotics?
Nitrofurantoin has a more defensible clinical position than some older broad-spectrum antibiotics because stewardship programs favor targeted therapy for uncomplicated cystitis. Its commercial position is weaker than that of branded or recently differentiated anti-infectives because pricing is low and generic substitution is extensive.
Compared with trimethoprim-sulfamethoxazole, nitrofurantoin benefits where resistance or allergy limits the comparator. Compared with fosfomycin, it usually has a lower cost but less convenient dosing. Compared with fluoroquinolones, it benefits from stewardship restrictions on broader-spectrum agents but cannot replace systemic therapy for upper-tract disease.
Key Takeaways
- Nitrofurantoin is a mature generic urinary anti-infective with durable outpatient demand.
- A modeled global market of $1.0 billion to $1.3 billion in 2024 could reach $1.3 billion to $1.6 billion by 2029.
- Base-case growth is estimated at approximately 4% to 6% annually, with unit growth exceeding revenue growth.
- The United States is the largest commercial market, but generic price competition limits margin expansion.
- Composition, formulation, and method-of-use exclusivity have expired or lack current blocking value.
- The market has no material current patent moat and is not primarily exposed to biosimilar risk because nitrofurantoin is a small-molecule drug.
- A new ANDA entrant would face regulatory execution risk, price erosion, and distribution barriers rather than significant patent litigation.
- The strongest commercial opportunities are supply reliability, underserved geographies, differentiated dosage forms, and efficient manufacturing.
FAQs
Is nitrofurantoin a high-growth pharmaceutical market?
No. It is a low- to mid-single-digit growth market driven by prescription volume, recurrent UTI treatment, and geographic expansion. Revenue growth is constrained by generic price erosion.
Does nitrofurantoin have biosimilar competition?
No. Nitrofurantoin is a chemically synthesized small-molecule drug. Its competitors are generic versions approved through ANDA or comparable national pathways, not biosimilars.
Can a new company obtain a patent on a nitrofurantoin formulation?
Yes, a genuinely novel formulation may be patentable if it satisfies novelty, non-obviousness, written-description, and enablement standards. A patent would protect only the claimed formulation or use, not the underlying nitrofurantoin molecule.
Is Macrobid still commercially important?
Macrobid remains clinically recognized, but generic monohydrate/macrocrystal products dominate dispensing in many markets. The brand has limited pricing power where substitution is permitted.
What is the main investment risk in nitrofurantoin?
The main risk is margin compression. A company can maintain or increase unit volume while experiencing declining net revenue because multiple generic suppliers compete for pharmacy and wholesaler contracts.
References
-
U.S. Food and Drug Administration. (2022). Macrobid (nitrofurantoin monohydrate/macrocrystalline) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. FDA.
-
Gupta, K., Hooton, T. M., Naber, K. G., Wullt, B., Colgan, R., Miller, L. G., Moran, G. J., Nicolle, L. E., Raz, R., Schaeffer, A. J., & Soper, D. E. (2011). International clinical practice guidelines for the treatment of acute uncomplicated cystitis and pyelonephritis in women. Clinical Infectious Diseases, 52(5), e103-e120.
-
Infectious Diseases Society of America and European Society for Microbiology and Infectious Diseases. (2011). International clinical practice guidelines for acute uncomplicated cystitis and pyelonephritis in women. IDSA.
-
World Health Organization. (2023). WHO bacterial priority pathogens list, 2024. World Health Organization.
More… ↓
