Share This Page
Drug Sales Trends for ondansetron
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ondansetron (2018)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
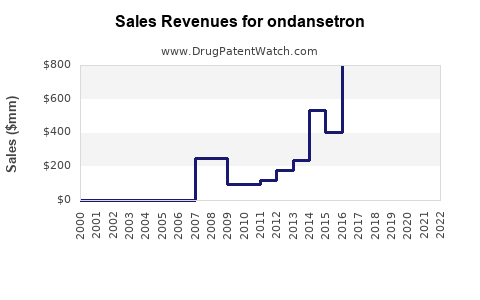
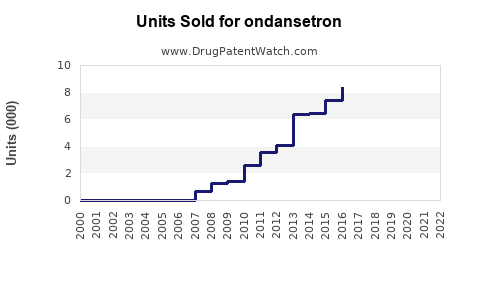
Annual Sales Revenues and Units Sold for ondansetron
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ONDANSETRON | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ONDANSETRON | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ONDANSETRON | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ONDANSETRON | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ONDANSETRON | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Ondansetron Market Analysis and Sales Projections, Patent Status, and Competitive Landscape
Ondansetron is a mature, off-patent 5-HT3 receptor antagonist used to prevent nausea and vomiting associated with chemotherapy, radiotherapy, surgery, and gastroenteritis. The market is genericized, price-competitive, and fragmented across tablets, orally disintegrating tablets, oral solution, and injectable products. Global ondansetron sales are best modeled as a low-growth market driven by procedure volumes, oncology treatment, hospital demand, and emerging-market access rather than by patent-protected pricing.
A base-case model estimates global ondansetron product revenue of approximately $1.05 billion in 2024, rising to $1.20 billion by 2029 at a compound annual growth rate of about 2.7%. Growth is concentrated in injectable hospital products, pediatric oral formulations, and markets with expanding generic access. U.S. revenue is likely to remain broadly flat because generic competition has removed most brand pricing power.
What is ondansetron used for and how large is its market?
Ondansetron is approved for the prevention of nausea and vomiting associated with:
- Moderately and highly emetogenic cancer chemotherapy
- Radiotherapy
- Postoperative nausea and vomiting
- Selected off-label uses, including gastroenteritis-related vomiting and pregnancy-associated nausea under clinical supervision
The active ingredient is ondansetron hydrochloride, commonly supplied as ondansetron hydrochloride dihydrate. Products are administered orally, sublingually through orally disintegrating tablets, as oral solution, or by intravenous and intramuscular injection.
The original branded product, Zofran, was developed by GlaxoSmithKline. The U.S. product was approved in 1991, and generic products subsequently entered after expiration of the principal patent and regulatory exclusivity rights (U.S. Food and Drug Administration [FDA], 1991).
Estimated global market size
Public market reports differ because some count only finished-dose ondansetron products while others include broader antiemetic categories. The following forecast isolates ondansetron products and uses a bottom-up estimate based on hospital injectables, outpatient oral prescriptions, oncology use, surgical use, and international generic markets.
| Year | Estimated global ondansetron revenue | Year-over-year growth | Primary growth drivers |
|---|---|---|---|
| 2024 | $1.05 billion | 2.1% | Oncology procedures, surgery, generic access |
| 2025 | $1.08 billion | 2.9% | Injectable demand and emerging markets |
| 2026 | $1.11 billion | 2.8% | Hospital purchasing and pediatric use |
| 2027 | $1.14 billion | 2.7% | Procedure growth and broader reimbursement |
| 2028 | $1.17 billion | 2.6% | Stable oncology and surgical demand |
| 2029 | $1.20 billion | 2.5% | Mature-market stability and international expansion |
These figures represent modeled product revenue, not audited sales reported by a single manufacturer. Ondansetron has no consolidated global commercial owner, and public company filings generally report it within broader generic or hospital-product portfolios.
Regional revenue mix
North America and Europe have high utilization but low prices. Asia-Pacific, Latin America, and parts of the Middle East and Africa have lower average selling prices but stronger unit-volume growth.
| Region | Estimated 2024 share | Estimated 2024 revenue | Market characteristics |
|---|---|---|---|
| North America | 28% | $294 million | Mature generic market; hospital and retail demand |
| Europe | 24% | $252 million | National tendering and low generic prices |
| Asia-Pacific | 31% | $326 million | High unit growth; price-sensitive procurement |
| Latin America | 10% | $105 million | Public-sector purchasing and private retail |
| Middle East and Africa | 7% | $74 million | Uneven access; injectable and hospital demand |
India and China are important volume markets, while the United States remains commercially important because of its large hospital, ambulatory surgery, oncology, and retail pharmacy systems.
When did ondansetron lose exclusivity?
Ondansetron lost meaningful U.S. market exclusivity years ago. The original Zofran patents and regulatory exclusivity periods have expired, and generic manufacturers can market approved products without relying on a brand license.
The principal commercial consequences were:
- Multiple abbreviated new drug applications entered the U.S. market.
- Retail prices declined sharply from branded levels.
- Hospital procurement shifted toward contract pricing and tenders.
- Commercial value moved from molecular exclusivity to manufacturing scale, supply reliability, and formulation differentiation.
The active ingredient does not have current composition-of-matter protection in major markets. Any remaining patent value would generally relate to a specific formulation, delivery system, manufacturing process, or narrow method of use rather than ondansetron itself.
What is the FDA regulatory and Orange Book status of ondansetron?
Ondansetron is an FDA-approved small-molecule drug available through both brand and generic pathways. Generic versions are approved under abbreviated new drug applications and must demonstrate pharmaceutical equivalence and bioequivalence to the applicable reference product.
The FDA reference product is associated with Zofran and its dosage forms. The Orange Book identifies approved products, therapeutic equivalence ratings, and relevant patent or exclusivity information. Because the original product is off-patent, current commercial competition depends primarily on ANDA approvals, manufacturing capacity, pricing, and supply-chain performance rather than Orange Book exclusivity (FDA, 2024a).
Key FDA dosage forms
| Dosage form | Main commercial use | Competitive position |
|---|---|---|
| 4 mg and 8 mg tablets | Outpatient nausea and vomiting | Highly genericized |
| Orally disintegrating tablets | Patients unable to swallow; convenience use | Generic competition, modest formulation value |
| Oral solution | Pediatric and swallowing-related use | Smaller segment; manufacturing and stability matter |
| Injectable solution | Chemotherapy, surgery, emergency and inpatient use | Higher hospital relevance and supply risk |
| Premixed or ready-to-use injection | Institutional settings | Potential operational differentiation |
The ODT format may carry practical value because it supports administration without water. It does not, by itself, create durable molecular exclusivity. Product-specific formulation patents would need to be reviewed by jurisdiction and dosage form.
What patents protect ondansetron products today?
No active basic-patent barrier is expected to prevent generic ondansetron entry in the United States. The legacy Zofran patent estate has expired.
The relevant intellectual-property categories are:
- Expired composition and product patents covering ondansetron or early formulations
- Formulation patents covering orally disintegrating or rapidly dissolving dosage forms
- Manufacturing patents covering crystallization, impurity control, or process yield
- Device or packaging patents covering delivery systems
- Method-of-use patents covering specific patient populations or dosing regimens
A formulation or process patent can affect a particular product without preventing competitors from selling conventional tablets or injections. For commercial analysis, patent scope must be separated from product-level market access. A manufacturer may have freedom to sell a standard ondansetron tablet even if another company holds a narrow patent on a flavored oral solution or specialized delivery platform.
Patent strength assessment
| Patent category | Current barrier to generic ondansetron | Commercial strength |
|---|---|---|
| Core molecule | None expected in major markets | Very low |
| Conventional tablets | Minimal | Very low |
| Standard injection | Minimal | Very low |
| Orally disintegrating formulations | Potentially narrow | Low to moderate |
| Manufacturing processes | Product-specific | Moderate if difficult to design around |
| Packaging or delivery device | Narrow and jurisdiction-specific | Low to moderate |
| New method of use | Limited by clinical and legal scope | Low for the established market |
Overall patent strength is low. The commercial moat is operational rather than legal.
Which companies compete in the ondansetron market?
The market includes multinational generic manufacturers, specialty pharmaceutical companies, hospital suppliers, and regional manufacturers. Competitive participation varies by country and dosage form.
Representative U.S. and international suppliers have included:
- Hikma Pharmaceuticals
- Fresenius Kabi
- Teva Pharmaceutical Industries
- Sandoz
- Cipla
- Dr. Reddy’s Laboratories
- Aurobindo Pharma
- Viatris
- Amneal Pharmaceuticals
- Sun Pharmaceutical Industries
- Accord Healthcare
- Zydus Lifesciences
- Eugia Pharma
- Pfizer through hospital and injectable portfolios in selected markets
Manufacturer presence changes as products are discontinued, acquired, transferred, or removed from shortage-prone markets. Hospital injectable supply is more concentrated than oral tablet supply because sterile manufacturing requires higher capital investment, regulatory compliance, and quality-control capacity.
How does ondansetron compare with competing antiemetics?
Ondansetron competes with other 5-HT3 antagonists, dopamine antagonists, neurokinin-1 antagonists, corticosteroids, antihistamines, and combination regimens.
| Drug or class | Main competitive advantage | Main limitation versus ondansetron |
|---|---|---|
| Palonosetron | Longer half-life; oncology use | Higher cost in many settings |
| Granisetron | Established oncology use | Less broad generic differentiation |
| Dolasetron | Historical 5-HT3 option | Limited current relevance |
| Metoclopramide | Low cost; prokinetic effect | Extrapyramidal and other adverse effects |
| Prochlorperazine | Low cost; broad antiemetic use | Sedation and movement-related risks |
| Aprepitant and other NK1 agents | Strong chemotherapy regimen role | Higher cost and combination use |
| Dexamethasone | Effective combination partner | Not a direct standalone substitute in every indication |
Ondansetron’s position is strongest where clinicians value predictable tolerability, oral and injectable availability, low cost, and broad institutional familiarity.
What drives ondansetron sales growth through 2029?
The principal volume drivers are:
Oncology treatment
Chemotherapy remains a core demand source. Growth in cancer incidence, treatment access, infusion-center capacity, and supportive-care protocols supports unit demand. Ondansetron is often used as part of a multi-drug antiemetic regimen rather than as the only antiemetic.
Surgical and procedural volume
Ambulatory surgery, emergency care, and inpatient procedures generate demand for injectable ondansetron. Recovery-room and perioperative use is particularly relevant for hospital suppliers.
Pediatric and oral-solution demand
Oral solution and ODT products address pediatric patients and individuals who cannot reliably swallow conventional tablets. This segment is smaller than standard tablets but can support better pricing where supplier competition is limited.
Generic access in emerging markets
In lower- and middle-income countries, increased access to cancer treatment, surgery, and hospital care can raise unit volumes. Pricing remains constrained by public tenders and local competition.
Hospital supply resilience
Shortages or manufacturing interruptions can shift contracts between suppliers. A manufacturer with redundant sterile capacity, validated alternate sites, and reliable regulatory compliance can gain share even in a low-margin market.
What sales risks affect ondansetron projections?
Ondansetron has limited pricing power. The principal risks are volume, price, and substitution risks.
| Risk | Expected effect | Commercial exposure |
|---|---|---|
| Generic price erosion | Reduces revenue despite stable volume | High |
| Hospital tender losses | Rapid share loss | High for injectable suppliers |
| Sterile manufacturing disruption | Lost sales and regulatory scrutiny | High |
| Alternative antiemetic use | Modest volume pressure | Moderate |
| Reduced chemotherapy intensity | Lower oncology demand | Moderate |
| Retail reimbursement changes | Lower net price | Moderate |
| Product discontinuation | Local supply gaps | Moderate |
| Regulatory inspection findings | Supply interruption | High |
The most significant risk is not patent litigation. It is loss of supply contracts or inability to maintain sterile production.
What are the bull-case, base-case, and bear-case sales projections?
The following scenarios apply to global ondansetron product revenue and assume no major new branded formulation captures the market.
| Scenario | 2024 revenue | 2029 revenue | 2024-2029 CAGR | Core assumptions |
|---|---|---|---|---|
| Bear case | $1.05 billion | $1.00 billion | -1.0% | Faster price erosion, weak hospital pricing, substitution |
| Base case | $1.05 billion | $1.20 billion | 2.7% | Stable oncology and surgery demand; moderate emerging-market growth |
| Bull case | $1.05 billion | $1.38 billion | 5.6% | Strong procedure growth, injectable shortages, higher treatment access |
The bull case does not depend on restored patent exclusivity. It assumes suppliers capture value through injectable capacity, specialized formulations, or temporary market dislocation. The bear case is plausible for manufacturers exposed primarily to commodity tablets.
Manufacturer-level revenue outlook
A supplier with a broad generic portfolio should treat ondansetron as a portfolio contributor rather than a standalone growth asset. A manufacturer focused on oral tablets may see flat or declining net sales even if global units increase. A sterile-injectable producer can achieve better revenue performance because hospital contracts, quality requirements, and supply constraints support higher average prices.
What generic launch risks exist for ondansetron?
Generic launch risk is low from a legal-entry perspective and moderate from a commercial-execution perspective.
A new entrant must manage:
- ANDA approval and therapeutic-equivalence requirements
- Active pharmaceutical ingredient qualification
- Bioequivalence for oral products
- Sterility assurance for injectable products
- Container-closure and stability testing
- State and federal purchasing contracts
- Pharmacy benefit and wholesaler access
- Price erosion following additional entrants
The standard tablet market is relatively easy to enter but difficult to scale profitably. Injectable products have stronger manufacturing barriers and may offer better strategic value, although they carry greater regulatory and operational risk.
What patent litigation and Paragraph IV activity affects ondansetron?
Ondansetron is not currently characterized by an active, high-value U.S. Paragraph IV litigation campaign comparable with patented specialty drugs. The main branded-product patent barriers expired before the current generic market structure was established.
Paragraph IV risk for a new ondansetron ANDA would generally be limited unless the applicant targets a product with an unexpired, listed formulation or method-of-use patent. For conventional tablets and injections, the key risks are regulatory approval, supply, and pricing rather than patent litigation.
There is no biosimilar risk because ondansetron is a chemically synthesized small molecule, not a biologic. Competition proceeds through ANDAs and other national generic pathways.
What licensing deals and commercial partnerships matter?
The original Zofran commercialization was associated with GlaxoSmithKline. Current ondansetron economics are dominated by generic manufacturing, contract supply, hospital procurement, and regional distribution arrangements rather than major originator licensing deals.
The most commercially relevant agreements are likely to involve:
- Contract manufacturing
- API supply
- Hospital group purchasing
- Regional distribution
- Product transfers between generic companies
- Co-marketing or authorized-generic arrangements
- Licensing of differentiated ODT, oral-solution, or injectable presentations
These agreements can change supplier share without altering the underlying patent position.
What is the investment outlook for ondansetron?
Ondansetron is a defensive, mature generic product with predictable demand and limited innovation upside. Its investment profile differs by business model.
| Business model | Outlook |
|---|---|
| Commodity oral-tablet manufacturer | Low growth; high price pressure |
| Sterile-injectable manufacturer | Better share and margin potential; higher compliance risk |
| Specialty formulation developer | Selective upside if delivery or usability improves |
| API manufacturer | Volume opportunity but commodity economics |
| Hospital distributor | Stable demand; limited product-level differentiation |
| Branded reformulation strategy | Difficult without clinical, device, or reimbursement advantage |
A reasonable base-case investment view is stable-to-low single-digit market growth, with stronger outcomes for companies that control sterile capacity or differentiated delivery formats. The product is unlikely to support premium valuation based on molecule-level intellectual property.
Key Takeaways
- Ondansetron is a mature, globally genericized antiemetic.
- Estimated global product revenue is approximately $1.05 billion in 2024.
- Base-case revenue reaches about $1.20 billion by 2029, representing a 2.7% CAGR.
- U.S. sales are likely to remain flat because of intense generic competition.
- Injectable products offer better commercial differentiation than conventional tablets.
- The original Zofran patent estate has expired, and core-molecule patent protection is no longer a market barrier.
- Current risks center on price erosion, hospital tenders, sterile manufacturing, and supply reliability.
- Ondansetron has no biosimilar risk because it is a small-molecule drug.
- Paragraph IV and patent-litigation exposure is low for conventional products.
- Commercial upside depends on formulation, manufacturing, and distribution execution rather than exclusivity.
FAQs About Ondansetron Market Sales and Exclusivity
How much does ondansetron cost the healthcare system?
Generic oral ondansetron is typically low cost, while injectable pricing varies by supplier, hospital contract, package size, and shortage conditions. Net prices are substantially below historical branded Zofran pricing.
Is ondansetron still a profitable drug?
It can be profitable at scale, particularly in sterile injectables and institutional supply. Conventional tablets generally have low margins because multiple generic suppliers compete on price.
Does Zofran still have patent protection?
The original Zofran patent and exclusivity barriers have expired in the United States. Narrow patents covering particular formulations or delivery systems must be assessed separately.
Is ondansetron approved for pregnancy-related nausea?
Ondansetron is used in some pregnancy-related nausea and vomiting cases, but this use is distinct from the principal FDA-approved indications. Prescribing decisions depend on patient-specific clinical assessment and applicable labeling.
Which ondansetron formulation has the strongest commercial outlook?
Injectable ondansetron has the strongest strategic outlook because sterile manufacturing limits supplier participation. ODT and oral-solution products may offer selective value where convenience, pediatric dosing, or supply reliability supports differentiation.
References
-
U.S. Food and Drug Administration. (1991). Zofran (ondansetron hydrochloride) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: The Orange Book. FDA.
-
U.S. Food and Drug Administration. (2024b). Drugs@FDA: FDA-approved drugs database. FDA.
-
U.S. Food and Drug Administration. (2024c). Approved drug product list and abbreviated new drug application information. FDA.
-
National Cancer Institute. (2024). Nausea and vomiting related to cancer treatment. National Institutes of Health.
-
World Health Organization. (2023). WHO model list of essential medicines. World Health Organization.
More… ↓
