Share This Page
Drug Sales Trends for mirtazapine
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for mirtazapine (2018)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
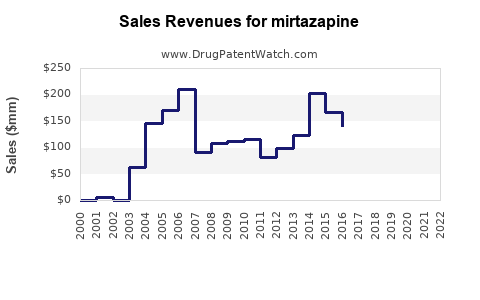
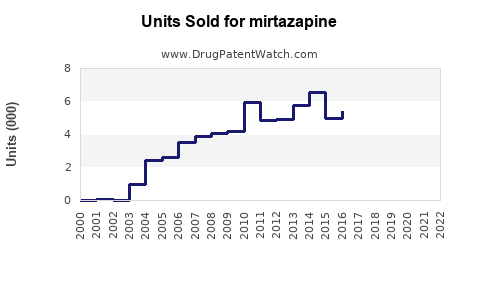
Annual Sales Revenues and Units Sold for mirtazapine
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| MIRTAZAPINE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| MIRTAZAPINE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| MIRTAZAPINE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| MIRTAZAPINE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| MIRTAZAPINE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| MIRTAZAPINE | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| MIRTAZAPINE | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Mirtazapine Market Analysis, Sales Forecast, Patent Status, and Generic Competition
Mirtazapine is a mature, fully generic antidepressant with limited brand revenue and low patent risk. The market is driven by prescription volume, low-cost generic supply, and continued use in major depressive disorder where insomnia, poor appetite, or weight loss are clinical considerations. Global mirtazapine sales are likely concentrated in low-price generic channels, with limited opportunity for premium pricing unless a company develops a differentiated formulation or combination product.
A reasonable base-case estimate places global mirtazapine market value at approximately $350 million to $550 million in 2025, measured at manufacturer and distributor revenue rather than retail sales. The market is likely to decline modestly in nominal value through 2030 as price competition offsets stable or slightly increasing prescription volume.
What is mirtazapine and how is it used?
Mirtazapine is a noradrenergic and specific serotonergic antidepressant approved in the United States for major depressive disorder in adults. The original brand, Remeron, was developed by Organon and later commercialized by Schering-Plough and Merck. Remeron SolTab is the orally disintegrating tablet version. Both products have faced generic competition for many years.
Mirtazapine is available in:
| Dosage form | Common strengths | Commercial status |
|---|---|---|
| Immediate-release tablet | 15 mg, 30 mg, 45 mg | Generic |
| Orally disintegrating tablet | 15 mg, 30 mg, 45 mg | Generic |
| Brand tablet, Remeron | 15 mg, 30 mg, 45 mg | Legacy or limited availability |
| Brand orally disintegrating tablet, Remeron SolTab | 15 mg, 30 mg, 45 mg | Legacy or limited availability |
The usual starting dose is 15 mg once daily, generally administered at bedtime. The FDA-approved labeling identifies somnolence, increased appetite, weight gain, dizziness, and dry mouth among common adverse reactions. The label also carries antidepressant class warnings concerning suicidal thoughts and behaviors in pediatric, adolescent, and young adult patients. Mirtazapine is not approved by the FDA for pediatric major depressive disorder.[1]
How large is the mirtazapine market?
The market is substantial in prescription volume but small in branded pharmaceutical value. Mirtazapine competes in the mature antidepressant segment against generic sertraline, escitalopram, fluoxetine, bupropion, venlafaxine, duloxetine, trazodone, and paroxetine.
Public company filings generally do not report mirtazapine revenue separately because the product is generic and sold through diversified portfolios. Market estimates therefore depend on prescription counts, dosage mix, geographic pricing, and channel assumptions.
Estimated 2025 global market
| Market measure | 2025 estimate |
|---|---|
| Global prescription volume | 90 million to 130 million monthly treatment equivalents |
| Global manufacturer-level value | $350 million to $550 million |
| Global retail value | $700 million to $1.2 billion |
| U.S. manufacturer-level value | $80 million to $150 million |
| U.S. retail and pharmacy-channel value | $180 million to $350 million |
| Branded Remeron contribution | De minimis relative to generic sales |
The wide value range reflects differences in generic pricing. A 30-day supply of generic mirtazapine may cost only a few dollars in high-volume markets, while private-pay prices can be materially higher in some countries. Orally disintegrating tablets also carry a price premium in certain channels, although generic competition has narrowed that premium.
What are the mirtazapine sales projections through 2030?
The base case assumes stable underlying demand, gradual unit growth in aging populations, continued generic price erosion, and no major branded reformulation. Under those assumptions, value declines even if prescription volume is stable.
Global mirtazapine market forecast
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2025 | $325 million | $450 million | $575 million |
| 2026 | $310 million | $440 million | $580 million |
| 2027 | $295 million | $430 million | $590 million |
| 2028 | $280 million | $420 million | $600 million |
| 2029 | $265 million | $410 million | $605 million |
| 2030 | $250 million | $400 million | $610 million |
| 2025-2030 CAGR | -5.1% | -2.3% | 1.2% |
The base case projects a market decline of about 2% annually. Volume is expected to remain comparatively resilient because mirtazapine is inexpensive, established in clinical practice, and used in patients for whom sedation or appetite stimulation can be clinically useful. Price erosion is the primary constraint on revenue.
The bull case requires one or more of the following developments:
- Increased prescribing in older adults with depression, insomnia, or appetite loss.
- Greater use of orally disintegrating tablets in patients with swallowing difficulty.
- Supply disruptions affecting competing antidepressants.
- Premium pricing for a differentiated delivery system.
- Expansion in emerging markets with rising diagnosis and treatment rates.
The bear case reflects accelerated generic price compression, substitution by low-cost SSRIs, declining use for off-label insomnia, and fewer suppliers maintaining commercially active mirtazapine portfolios.
When does mirtazapine lose exclusivity?
Mirtazapine lost meaningful U.S. market exclusivity years ago. The original Remeron product was approved in 1996, and generic products entered the U.S. market after expiration of the relevant patent and regulatory exclusivity barriers.[2]
| Milestone | Approximate timing |
|---|---|
| Original Remeron FDA approval | 1996 |
| Remeron SolTab approval | 2001 |
| Generic tablet competition | Early 2000s |
| Generic orally disintegrating tablet competition | Mid-2000s onward |
| Current U.S. patent barrier | No material blocking patent expected |
| Current commercial status | Mature generic market |
Mirtazapine is therefore not an asset with a conventional loss-of-exclusivity event ahead. The commercial question is supply economics, not the timing of generic entry.
What patents protect mirtazapine?
The core composition-of-matter protection for mirtazapine has expired. Current patent risk is limited to narrow formulation, process, packaging, or device claims rather than the active ingredient itself.
Potentially relevant patent categories include:
- Drug substance manufacturing processes.
- Crystal form or polymorph claims.
- Orally disintegrating tablet compositions.
- Taste-masking technologies.
- Modified-release delivery systems.
- Combination products.
- Method-of-use claims for specific populations or symptoms.
These rights generally do not prevent standard generic tablets from entering the market. A process patent may affect manufacturing economics without blocking a competitor that uses a non-infringing process. A formulation patent may create a narrower commercial position for an orally disintegrating or modified-release product, but it does not restore exclusivity for conventional tablets.
What is the Orange Book status of mirtazapine?
The FDA Orange Book historically listed Remeron and Remeron SolTab products with patent information associated with the branded products. Current generic competition means that ordinary mirtazapine tablets and orally disintegrating tablets are established abbreviated new drug application products rather than protected branded products.[3]
The key commercial conclusions are:
- No active composition-of-matter exclusivity protects standard mirtazapine.
- Paragraph IV litigation is unlikely to affect the ordinary generic market.
- Any remaining listed patent issue would likely concern a specific formulation or product presentation.
- Generic applicants can generally compete on standard tablet strengths without waiting for a future loss-of-exclusivity date.
Are there Paragraph IV challenges to mirtazapine?
Paragraph IV challenges were commercially relevant when generic companies first sought approval for Remeron and Remeron SolTab products. They are no longer a central market event because generic mirtazapine has been available for many years.
Current commercial risk does not depend on a new Paragraph IV filing. It depends on:
- The number of active manufacturers.
- API availability.
- FDA manufacturing compliance.
- Contracting with wholesalers and pharmacy benefit managers.
- Channel-specific price competition.
- Supply continuity for 15 mg, 30 mg, and 45 mg strengths.
For an investor or originator, a new Paragraph IV campaign would have limited strategic value unless linked to a new formulation with meaningful differentiation.
What companies compete in the mirtazapine market?
The market has historically included large generic manufacturers and specialty suppliers such as Teva, Sandoz, Mylan, Zydus, Dr. Reddy's Laboratories, Aurobindo, Torrent, Sun Pharma, and other regional manufacturers. Corporate ownership and product availability have changed over time, and not every company continuously markets every strength or dosage form.
Competition is fragmented. No single manufacturer is likely to control the global market across all territories. Local registration, procurement contracts, and wholesaler relationships are more important than brand recognition.
Competitive structure by product type
| Product type | Competitive intensity | Margin outlook |
|---|---|---|
| 15 mg standard tablet | Very high | Low |
| 30 mg standard tablet | Very high | Low |
| 45 mg standard tablet | High | Low to moderate |
| Orally disintegrating tablet | Moderate to high | Moderate where differentiated |
| Modified-release product | Low | Potentially higher, subject to clinical and patent support |
| Combination product | Low | Higher potential but greater regulatory risk |
A company entering standard tablets would face a commodity market. A company entering an orally disintegrating tablet could obtain better pricing only if the product improves adherence, taste, administration, or supply reliability.
What formulations are protected by mirtazapine patents?
The most commercially relevant formulation opportunity is the orally disintegrating tablet. Remeron SolTab was designed for patients who have difficulty swallowing conventional tablets. Generic orally disintegrating versions have reduced the opportunity for a premium branded product.
Potential differentiation remains in:
- Faster disintegration.
- Improved taste masking.
- Lower friability.
- Better stability under humidity.
- Unit-dose packaging.
- Pediatric or geriatric administration.
- Lower-cost manufacturing.
- Combination with digital adherence or specialty pharmacy services.
A new formulation would need to demonstrate a commercial advantage large enough to offset development, manufacturing, and regulatory costs. A basic reformulation without a meaningful clinical or handling benefit would face rapid generic substitution.
What is the FDA regulatory status of mirtazapine?
Mirtazapine is an FDA-approved prescription drug for major depressive disorder in adults. Generic tablets and orally disintegrating tablets are approved through the abbreviated new drug application pathway, which generally requires demonstration of pharmaceutical equivalence and bioequivalence rather than a new efficacy trial.[1][4]
Key regulatory characteristics include:
- FDA-approved active ingredient: mirtazapine.
- Primary approved indication: major depressive disorder in adults.
- Generic pathway: ANDA.
- Pediatric approval for depression: none.
- Controlled-substance status: not scheduled under the federal Controlled Substances Act.
- Regulatory complexity: low for standard immediate-release products; higher for novel delivery systems or combination products.
Off-label use is common in clinical practice, particularly for insomnia, appetite loss, and anxiety-related symptoms, but those uses do not expand the FDA-approved label or create automatic market exclusivity.
What generic entry risks exist for mirtazapine?
Generic entry risk is already realized rather than prospective. The principal risks for a mirtazapine manufacturer are margin compression and portfolio rationalization.
Manufacturer risks
- Additional suppliers can reduce prices quickly.
- Low-volume strengths may be discontinued.
- API sourcing disruptions can affect multiple manufacturers.
- Wholesalers may shift purchases toward the lowest-cost supplier.
- Pharmacy benefit managers may prefer a narrow group of manufacturers.
- FDA warning letters or manufacturing observations can remove capacity.
- Retail demand can shift between tablet and orally disintegrating formats.
Originator risks
For the original brand owner, residual revenue exposure is limited. The brand has no realistic path to regain mass-market share without a new formulation, a new indication supported by clinical evidence, or a licensing arrangement with a differentiated delivery technology.
How does mirtazapine compare with other antidepressants?
Mirtazapine has a different commercial and clinical profile from the leading generic SSRIs.
| Drug | Market position | Key differentiator | Generic price pressure |
|---|---|---|---|
| Mirtazapine | Mature generic | Sedation and appetite effects | Very high |
| Sertraline | High-volume generic | Broad first-line use | Very high |
| Escitalopram | High-volume generic | Tolerability and efficacy | Very high |
| Fluoxetine | Mature generic | Long half-life and low cost | Very high |
| Bupropion | High-volume generic | Lower sexual side-effect burden for some patients | Very high |
| Trazodone | Generic | Sedating, often used off label for insomnia | Very high |
| Duloxetine | Generic | Depression plus neuropathic pain indications | High |
| Venlafaxine | Generic | Broad antidepressant use | High |
Mirtazapine's competitive advantage is not patent-based. It is clinical positioning. Prescribers may select it when insomnia, weight loss, nausea, or poor appetite are relevant. Its principal commercial disadvantage is sedation and weight gain, which can lead to discontinuation or substitution.
What licensing deals affect mirtazapine?
No major current licensing transaction is required to commercialize standard mirtazapine tablets in the United States. The product is available through generic licensing, contract manufacturing, and distribution arrangements rather than through a high-value originator partnership.
A licensing opportunity could arise around:
- Long-acting injectable mirtazapine.
- Modified-release delivery.
- Fixed-dose combinations.
- Geriatric or dysphagia-focused formulations.
- Digital adherence programs tied to specialty distribution.
- Geographic rights in markets where generic access remains limited.
The economic value of such a deal would depend on differentiated clinical utility. A license covering ordinary immediate-release mirtazapine would have limited value because multiple equivalent products already exist.
What is the revenue exposure for pharmaceutical companies?
Revenue exposure is asymmetric.
| Stakeholder | Revenue exposure |
|---|---|
| Original brand owner | Low and declining |
| Large generic manufacturer | Low per product, but meaningful across volume |
| API supplier | Moderate if supplying multiple finished-dose manufacturers |
| Specialty formulation developer | Potentially high if a premium product succeeds |
| Wholesaler and pharmacy | Low margin, high transaction volume |
| Payer | Low absolute spend relative to newer branded therapies |
Mirtazapine is unlikely to be a material revenue driver for a diversified pharmaceutical company. It can still be commercially useful as part of a generic CNS portfolio, especially where the manufacturer has low-cost API access and established pharmacy distribution.
What is the likely generic launch scenario?
A new entrant would likely face the following launch conditions:
- Standard tablets would enter a crowded market with low pricing.
- The 15 mg strength would likely have the greatest volume but the most competition.
- The 45 mg strength could have fewer suppliers and somewhat better economics.
- Orally disintegrating tablets may support higher gross margins than standard tablets.
- Hospital and institutional contracts could provide volume but impose aggressive price concessions.
- Regulatory compliance and supply reliability would matter more than promotional spending.
The strongest entry strategy would combine low-cost manufacturing with reliable supply and a formulation advantage. A conventional tablet-only launch would likely produce modest revenue and low operating margins.
How strong is the mirtazapine patent estate?
The patent estate is weak for the active ingredient and standard tablets, but potentially moderate for narrow delivery technologies.
| Patent category | Strength today | Ability to block generic tablets |
|---|---|---|
| Composition of matter | Expired | None |
| Standard tablet formulation | Weak or expired | None |
| Orally disintegrating tablet | Product-specific | Limited |
| Manufacturing process | Potentially active in some jurisdictions | Usually indirect |
| Modified release | Potentially stronger if valid | Product-specific |
| Combination product | Potentially moderate | Depends on claim scope |
| Method of use | Limited commercial value | Usually does not block all sales |
Patent enforcement would be difficult unless a competitor copied a protected formulation or manufacturing process. Patent litigation is not a central risk for ordinary generic mirtazapine.
What is the geographic market opportunity?
The largest commercial markets are the United States, Western Europe, Japan, Canada, Australia, and selected Central and Eastern European markets. Emerging markets may generate higher unit growth but lower prices.
Geographic outlook
| Region | Volume outlook | Price outlook | Commercial assessment |
|---|---|---|---|
| United States | Stable | Low | Large, mature generic market |
| Western Europe | Stable to modest growth | Low to moderate | Tender and reimbursement driven |
| Japan | Stable | Moderate | Local regulatory and distribution requirements |
| China | Growth potential | Low | Competitive domestic supply |
| India | High volume | Very low | Strong generic competition |
| Latin America | Modest growth | Variable | Country-specific access and pricing |
| Middle East and Africa | Modest growth | Variable | Procurement and supply reliability matter |
The United States and Europe will likely remain the largest value markets, while India, China, and other emerging markets may account for a greater share of unit growth.
Key Takeaways
- Mirtazapine is a mature, fully generic antidepressant with no meaningful upcoming loss-of-exclusivity event.
- Estimated global 2025 manufacturer-level market value is approximately $350 million to $550 million.
- A base-case forecast projects roughly $400 million in global value by 2030.
- Prescription volume should remain comparatively stable, but generic price erosion will pressure revenue.
- Standard tablets are commodity products with low margins.
- Orally disintegrating, modified-release, and combination formulations offer the strongest remaining commercial opportunities.
- Paragraph IV litigation and biosimilar risk are not material to mirtazapine. Biosimilars are irrelevant because mirtazapine is a small-molecule drug.
- The principal risks are supplier concentration, API disruptions, manufacturing compliance, and reimbursement-driven price competition.
- The strongest commercial position belongs to manufacturers with low-cost production, broad geographic registrations, and reliable supply.
FAQs About Mirtazapine Market Size and Commercial Outlook
Is mirtazapine still profitable for generic manufacturers?
Yes, but profitability depends on production cost, manufacturing scale, and supply reliability. Standard tablets generate low margins, while less crowded strengths and orally disintegrating products may provide better economics.
Does mirtazapine have biosimilar competition?
No. Mirtazapine is a chemically synthesized small-molecule drug, so competition occurs through generic drugs approved under the ANDA pathway rather than biosimilars.
Can a new company obtain exclusivity for a mirtazapine product?
Potentially, but not for the old active ingredient alone. A company would need a qualifying new formulation, combination product, clinical indication, or other patentable innovation.
Is Remeron still commercially important?
Remeron has limited commercial importance compared with generic mirtazapine. The branded product's historical value has largely transferred to generic manufacturers and distributors.
What mirtazapine product has the best market opportunity?
A differentiated orally disintegrating or modified-release product has the strongest potential. A standard immediate-release tablet would enter a mature, highly competitive market with limited pricing power.
References
-
U.S. Food and Drug Administration. (2024). Mirtazapine tablets: Prescribing information. FDA-approved labeling.
-
U.S. Food and Drug Administration. (1996). Remeron (mirtazapine) approval history. Drugs@FDA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. Orange Book.
-
U.S. Food and Drug Administration. (2024). Abbreviated new drug application (ANDA) process. FDA.
More… ↓
