Share This Page
Drug Sales Trends for DICYCLOMINE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for DICYCLOMINE (2017)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
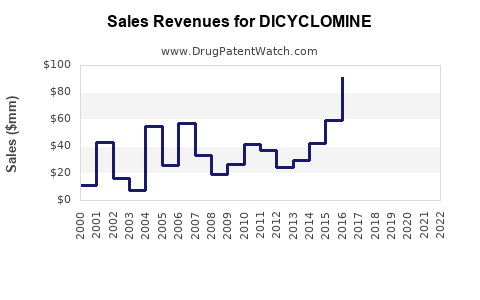
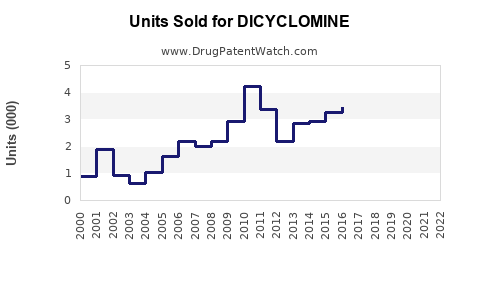
Annual Sales Revenues and Units Sold for DICYCLOMINE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| DICYCLOMINE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| DICYCLOMINE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| DICYCLOMINE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| DICYCLOMINE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| DICYCLOMINE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Dicyclomine Market Analysis, Sales Projections, Patent Status, and Competitive Outlook
Dicyclomine is a mature, low-cost generic anticholinergic used primarily for irritable bowel syndrome and functional bowel spasm. The U.S. market has limited brand economics, no meaningful remaining composition-of-matter exclusivity, and low barriers to entry for approved manufacturers. Commercial upside is concentrated in manufacturing efficiency, contract supply, pharmacy distribution, and differentiated dosage forms rather than in price expansion.
A reasonable U.S. manufacturer-revenue estimate is approximately $20 million to $55 million annually, with a base-case projection of $32 million in 2025 rising to $36 million by 2029. The range reflects uncertainty in prescription volume, channel mix, gross-to-net deductions, shortages, and manufacturer transfer pricing. Public databases do not provide a reliable consolidated revenue figure for all dicyclomine suppliers.
What is dicyclomine and how is it used?
Dicyclomine hydrochloride is a synthetic anticholinergic and antispasmodic. It reduces gastrointestinal smooth-muscle spasm through antimuscarinic activity and has historically been marketed in the United States under the Bentyl brand.
The FDA-approved indication is the treatment of patients with functional bowel or irritable bowel syndrome. Available dosage forms have included:
| Dosage form | Common strength or presentation | Commercial relevance |
|---|---|---|
| Tablets | 20 mg | Main outpatient generic form |
| Capsules | 10 mg and 20 mg | Alternative oral presentation |
| Oral solution | 10 mg/5 mL | Pediatric and swallowing-related use, subject to labeling restrictions |
| Injection | 10 mg/mL | Institutional and acute-care use |
The FDA labeling limits use in infants younger than six months because of serious adverse-event risk. Common adverse effects include dry mouth, dizziness, blurred vision, constipation, urinary retention, and tachycardia. These tolerability issues limit chronic use in some patients and support competition from newer IBS therapies. (U.S. Food and Drug Administration [FDA], 2023a)
How large is the dicyclomine market?
The dicyclomine market is a high-volume, low-value generic market. U.S. demand is generated mainly by primary-care physicians, gastroenterologists, emergency departments, and retail pharmacies.
Publicly available sources do not disclose an audited, combined revenue figure covering all dicycline manufacturers. Market sizing therefore requires a prescription-volume and net-price model.
Modeled U.S. market estimate
The following model uses a range of annual prescriptions and estimated manufacturer net revenue per prescription. It excludes pharmacy dispensing margins and most wholesaler revenue.
| Scenario | Annual U.S. prescriptions | Estimated manufacturer net revenue per prescription | Estimated annual manufacturer revenue |
|---|---|---|---|
| Low | 5.0 million | $3.50 | $17.5 million |
| Base | 7.0 million | $4.50 | $31.5 million |
| High | 9.0 million | $6.00 | $54.0 million |
These figures are analytical estimates, not reported sales. Retail cash prices can be substantially higher than manufacturer net revenue because they include dispensing fees, pharmacy margins, distribution costs, rebates, and payer adjustments.
What drives dicycline demand?
Demand is linked to:
- The prevalence of irritable bowel syndrome and functional gastrointestinal disorders.
- Continued generic prescribing.
- Physician familiarity with dicyclomine.
- Low acquisition cost compared with branded IBS therapies.
- Availability of multiple oral dosage forms.
- Use in patients seeking rapid, symptom-directed relief.
Demand is constrained by anticholinergic side effects, limited evidence for durable control of IBS symptoms, and competition from dietary interventions, peppermint oil, laxatives, antidiarrheals, antidepressants, rifaximin, linaclotide, plecanatide, lubiprostone, and eluxadoline.
What are the dicyclomine sales projections through 2029?
The base case assumes stable prescription volume, modest inflation in manufacturer net pricing, and no material new branded indication.
| Year | Low-case revenue | Base-case revenue | High-case revenue |
|---|---|---|---|
| 2025 | $17.5 million | $31.5 million | $54.0 million |
| 2026 | $17.6 million | $32.1 million | $54.5 million |
| 2027 | $17.8 million | $32.7 million | $55.0 million |
| 2028 | $18.0 million | $34.0 million | $56.1 million |
| 2029 | $18.2 million | $35.7 million | $57.2 million |
The base-case compound annual growth rate is approximately 3.2%. The forecast reflects price normalization and modest prescription stability rather than clinical expansion.
Sales forecast assumptions
The projection assumes:
- No major branded relaunch.
- No FDA-approved new indication.
- Continued availability from multiple generic suppliers.
- Stable reimbursement access.
- No sustained nationwide shortage.
- No material withdrawal of major manufacturers.
- No significant switch from oral products to a new long-acting formulation.
A shortage could temporarily increase supplier revenue and pricing. A new low-cost entrant could reduce revenue per prescription even if total volume remained stable.
What is the competitive landscape for dicyclomine?
Dicyclomine competes in two separate markets: low-cost antispasmodic therapy and broader IBS symptom management.
Direct generic competitors
Direct competitors include generic dicyclomine tablets, capsules, oral solution, and injectable products supplied by manufacturers such as Hikma Pharmaceuticals, Bausch Health-related businesses, Rising Pharmaceuticals, Teva, Amneal, and other FDA-approved suppliers. Manufacturer participation can change through product discontinuations, acquisitions, and private-label arrangements.
The principal competitive variables are:
- Wholesale acquisition cost.
- Supply reliability.
- FDA-approved dosage forms.
- Contract manufacturing capacity.
- Ability to serve Medicaid, managed-care, hospital, and retail channels.
- Product availability during shortages.
- Customer service and wholesaler inventory.
Therapeutic alternatives
| Therapy category | Examples | Competitive effect |
|---|---|---|
| Anticholinergic antispasmodics | Dicyclomine, hyoscyamine | Direct symptom-control competition |
| IBS with constipation therapies | Linaclotide, plecanatide, lubiprostone | Compete for chronic constipation-predominant IBS |
| IBS with diarrhea therapies | Rifaximin, eluxadoline | Compete for diarrhea-predominant IBS |
| General symptom treatments | Loperamide, fiber, polyethylene glycol | Lower-cost alternatives |
| Nonprescription approaches | Peppermint oil, dietary modification | Reduce drug use in some patients |
Dicyclomine retains an affordability advantage but lacks the commercial differentiation and reimbursement leverage of newer prescription IBS products.
What is the FDA regulatory status of dicyclomine?
Dicyclomine is an FDA-approved small-molecule prescription drug. It is not a biologic and does not face biosimilar competition.
Generic approvals are generally submitted under abbreviated new drug applications. A generic applicant must demonstrate pharmaceutical equivalence and bioequivalence to the relevant reference product. The principal regulatory risks are manufacturing compliance, product quality, labeling accuracy, and supply continuity rather than clinical-development risk.
The FDA has maintained labeling warnings concerning infants, glaucoma, urinary retention, ulcerative colitis complications, and other anticholinergic risks. (FDA, 2023a)
Is dicyclomine an Orange Book product?
The FDA Orange Book is principally relevant to approved reference products and listed patents or exclusivity. Dicyclomine products are now predominantly generic. The historical Bentyl product does not provide a practical exclusivity platform for current commercial planning.
Current Orange Book analysis should distinguish:
- The historical branded reference product.
- Approved generic dicyclomine products.
- Any listed patents associated with a specific reference formulation.
- Drug product discontinuation status.
- Manufacturer-specific approval status.
No active, commercially meaningful composition-of-matter patent is expected to block generic dicyclomine tablets or capsules. (FDA, 2024a)
When did dicyclomine lose exclusivity?
Dicyclomine’s core exclusivity expired decades ago. The active ingredient has been available in generic form for many years, and the market has no current small-molecule exclusivity comparable to a newly launched branded drug.
| Exclusivity type | Current commercial position |
|---|---|
| Composition-of-matter patent | Expired or no longer commercially blocking |
| New chemical entity exclusivity | Expired |
| Pediatric exclusivity | No current market significance |
| Orphan-drug exclusivity | Not applicable |
| Generic approval exclusivity | No meaningful current barrier |
| Biosimilar exclusivity | Not applicable |
A specific formulation, delivery system, or newly approved combination could receive separate protection, but conventional dicyclomine tablets and capsules do not have a defensible remaining exclusivity period based on the mature generic market.
What patents protect dicyclomine products?
The commercial patent estate is weak for conventional dicyclomine products. Historical patents may have covered the active compound, manufacturing processes, formulations, or dosage forms, but these rights are generally expired or have limited practical value.
Formulation patent exposure
Potential formulation claims could cover:
- Taste-masked oral solution.
- Modified-release tablets.
- Stable liquid formulations.
- Combination products.
- Abuse-deterrent or controlled-delivery systems.
- Pharmaceutical compositions with selected excipients.
Such claims would not automatically block ordinary immediate-release generic tablets or capsules. Their commercial value would depend on FDA approval, prescription demand, and whether the formulation creates clinically meaningful differentiation.
Manufacturing and process barriers
Dicyclomine is a mature small molecule with established manufacturing routes. Process patents, if active in a particular jurisdiction, would typically be avoidable through alternative synthesis or a design-around route. The more important barriers are:
- Current good manufacturing practice compliance.
- Validated analytical methods.
- Impurity control.
- Raw-material sourcing.
- Batch consistency.
- FDA inspection history.
- Ability to maintain low-cost supply.
Manufacturing economics, rather than patent exclusivity, determine most competitive outcomes.
Are there Paragraph IV challenges involving dicyclomine?
Paragraph IV litigation is not a major current feature of the conventional dicyclomine market. Paragraph IV certifications are most commercially important when an ANDA applicant challenges an unexpired Orange Book patent. With the core dicyclomine market already genericized, there is limited incentive for a large-scale patent challenge.
Applicants seeking approval for a novel dicyclomine formulation could face a different patent analysis. That would depend on the listed reference product, formulation claims, and any later-issued patents.
No major active Paragraph IV dispute is central to the conventional U.S. dicyclomine market based on the mature generic status of the product and the absence of a commercially significant blocking patent estate in the core dosage forms.
What patent litigation affects dicyclomine?
No major branded patent litigation currently defines the conventional dicyclomine market. Litigation risk is more likely to arise from:
- Manufacturing contracts.
- Product liability.
- FDA inspection or quality disputes.
- ANDA approval timing for a novel formulation.
- Trade-secret claims involving process technology.
- Distribution or supply agreements.
The low expected value of dicyclomine sales reduces the economic incentive for expensive patent litigation. A dispute would need to involve a differentiated product, a supply disruption, or a high-value formulation to justify substantial litigation spending.
Which companies are challenging or competing with dicyclomine?
Competition is fragmented among generic manufacturers and therapeutic alternatives. The most relevant commercial participants include generic suppliers with FDA-approved dicyclomine products, large wholesalers, pharmacy benefit managers, and companies selling branded IBS therapies.
The competitive threat is greater from inexpensive substitutes and newer IBS drugs than from a single patent challenger. Generic suppliers can enter or exit with limited public disclosure, making market-share tracking difficult without prescription-audit data.
What licensing deals involve dicyclomine?
Dicyclomine has limited licensing appeal because the active ingredient is generic, low priced, and broadly available. Commercial arrangements are more likely to involve:
- Contract manufacturing.
- Private-label supply.
- Authorized generic distribution.
- Hospital purchasing agreements.
- Wholesaler and pharmacy contracts.
- Regional product rights.
There is no widely disclosed current licensing transaction that materially changes the market outlook for conventional dicyclomine. A licensing transaction involving modified release, combination therapy, or a novel delivery system would have greater strategic value than a license covering standard immediate-release dicyclomine.
How strong is the dicyclomine patent estate?
The patent estate is weak for standard products and potentially moderate for a genuinely differentiated formulation.
| Asset area | Patent strength | Commercial assessment |
|---|---|---|
| Active ingredient | Low | Historical rights are expired |
| Immediate-release tablets | Low | Multiple generic suppliers |
| Immediate-release capsules | Low | Limited differentiation |
| Oral solution | Low to moderate | Formulation and manufacturing claims may exist |
| Injection | Low | Institutional product with limited margin |
| Modified release | Potentially moderate | Requires clinical and regulatory validation |
| Combination product | Potentially moderate | Dependent on new approval and market uptake |
| Manufacturing process | Low to moderate | Design-around options are likely |
Patent strength does not equal commercial strength. Even an enforceable formulation patent would have limited value unless the product can command a higher net price or capture meaningful chronic IBS use.
What generic launch scenarios exist for dicyclomine?
Base scenario
Existing suppliers maintain adequate supply, generic pricing remains competitive, and total U.S. revenue grows slowly through volume stability and modest price increases.
Downside scenario
A new supplier enters with aggressive pricing, payer substitution increases, and prescribers shift toward non-anticholinergic IBS treatments. Manufacturer revenue declines toward the low end of the forecast range.
Upside scenario
A supply disruption reduces the number of active suppliers, or a differentiated liquid, modified-release, or combination product gains approval. Revenue increases temporarily or shifts toward a higher-value formulation.
The most likely outcome is continued commoditization rather than a branded re-expansion.
How does dicycline compare with newer IBS drugs?
Dicyclomine has the lowest cost and the broadest generic availability among the compared therapies, but it has less clinical differentiation and weaker pricing power.
| Product or class | Market status | Pricing power | Patent position | Main advantage |
|---|---|---|---|---|
| Dicyclomine | Generic | Low | Expired core rights | Low cost |
| Linaclotide | Branded and generic-entry sensitive | High | Later-life-cycle patents | Chronic IBS-C treatment |
| Plecanatide | Branded | High | Active product-specific rights may apply | IBS-C and constipation |
| Rifaximin | Branded/generic-entry sensitive | High | Product and use patents | IBS-D and recurrence management |
| Eluxadoline | Branded/generic-entry sensitive | Moderate to high | Product-specific rights may apply | IBS-D |
| Hyoscyamine | Generic | Low | Mature | Antispasmodic alternative |
Dicyclomine’s main commercial defense is price, not intellectual property.
What revenue exposure do manufacturers face?
For a generic manufacturer, dicyclomine is unlikely to represent a major revenue concentration unless the company has a narrow portfolio or controls a large share of a specific dosage form. Revenue exposure is more significant in cases involving:
- A single-source oral solution.
- Hospital injectable supply.
- A temporary shortage.
- A private-label contract.
- A portfolio of gastrointestinal generics.
- A wholesaler agreement with concentrated demand.
Margin exposure can be material even when absolute revenue is small because generic products operate on thin spreads. Manufacturing downtime, batch rejection, or raw-material inflation can eliminate profitability.
Key Takeaways
- Dicyclomine is a mature generic antispasmodic with no meaningful remaining core exclusivity.
- Estimated U.S. manufacturer revenue is approximately $20 million to $55 million annually.
- A base-case model projects revenue of $31.5 million in 2025 and $35.7 million in 2029.
- Patent risk for conventional tablets, capsules, solution, and injection products is low.
- Paragraph IV litigation is not a central market issue.
- Biosimilar risk does not apply because dicyclomine is a small molecule.
- The strongest commercial risks are price erosion, supply disruption, quality compliance, and therapeutic substitution.
- Modified-release, liquid, combination, or other differentiated formulations could create new patent value.
- The market’s main competitive advantage is low cost, while its principal weakness is limited clinical and commercial differentiation.
FAQs
Is dicyclomine still profitable for generic drug manufacturers?
It can be profitable at scale, but margins are generally low. Profitability depends on manufacturing cost, supplier concentration, dosage form, contract terms, and supply reliability.
Can a new company launch generic dicyclomine without a patent license?
For conventional approved dosage forms, a patent license is generally not the principal barrier because the core exclusivity has expired. The applicant must still satisfy FDA requirements for an ANDA, manufacturing, labeling, and bioequivalence.
Does dicyclomine have a 180-day generic exclusivity period?
A 180-day period could apply to a qualifying first ANDA applicant under the Hatch-Waxman framework, but it is not a continuing exclusivity feature of the established dicyclomine market. The commercial market is already supplied by multiple generic products.
Is dicyclomine subject to biosimilar competition?
No. Dicyclomine is a chemically synthesized small molecule. Competition occurs through generic drug approvals, not biosimilar applications.
Could a modified-release dicyclomine product support a higher valuation?
Yes, but only if the product demonstrates clinical or adherence benefits, receives FDA approval, obtains defensible formulation protection, and captures demand beyond low-cost immediate-release products. Without those conditions, a modified-release formulation would face limited pricing power.
References
-
U.S. Food and Drug Administration. (2023a). Bentyl (dicyclomine hydrochloride) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations, commonly known as the Orange Book. FDA.
-
U.S. Food and Drug Administration. (2024b). Drugs@FDA: FDA-approved drugs database. FDA.
-
National Institute of Diabetes and Digestive and Kidney Diseases. (2024). Irritable bowel syndrome. National Institutes of Health.
-
U.S. Food and Drug Administration. (2024c). Abbreviated new drug application process for generic drugs. FDA.
More… ↓
