Drug Sales Trends for ATORVASTATIN
Payment Methods and Pharmacy Types for ATORVASTATIN (2017)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
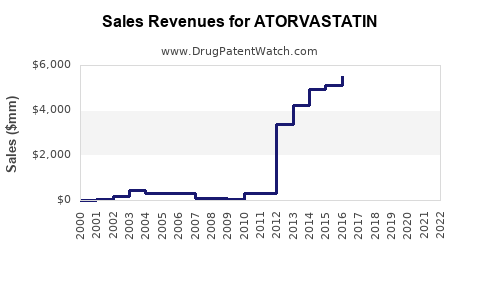
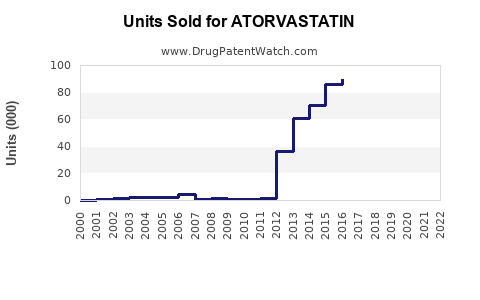
Annual Sales Revenues and Units Sold for ATORVASTATIN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ATORVASTATIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ATORVASTATIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ATORVASTATIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Atorvastatin Market Analysis, Sales Projections, Patent Status, and Competitive Outlook
Atorvastatin remains the largest global statin franchise by prescription volume and one of the most commercially durable generic medicines. Pfizer’s Lipitor generated approximately $13.2 billion at peak annual sales, but brand revenue collapsed after U.S. generic entry in November 2011. The current market is driven by high-volume generic atorvastatin, expanding cardiovascular screening, combination therapy, and continued use in primary and secondary prevention.
A base-case market model estimates global atorvastatin product sales of approximately $3.4 billion in 2024, rising to $4.1 billion by 2030 at a nominal compound annual growth rate of about 3.2%. Unit demand should grow faster than revenue because generic pricing remains under pressure.
What is the current atorvastatin market size?
Atorvastatin is a generic HMG-CoA reductase inhibitor marketed in more than 100 countries. The market includes generic tablets, branded generics, limited residual Lipitor sales, and combination products containing atorvastatin with antihypertensive agents or other cardiovascular therapies.
Public market estimates vary widely because analysts use different definitions. Some include only atorvastatin calcium tablets, while others include fixed-dose combinations, hospital procurement, private-label products, and regional branded generics. A practical commercial range is shown below.
| Market measure | 2024 estimated value | 2030 projected value | 2024-2030 CAGR |
|---|---|---|---|
| Global atorvastatin active-ingredient market | $2.5B-$4.5B | $3.2B-$5.8B | 3%-5% |
| Base-case global market | $3.4B | $4.1B | 3.2% |
| U.S. atorvastatin product sales | $0.8B-$1.2B | $0.9B-$1.3B | 1%-3% |
| European market | $0.6B-$0.9B | $0.7B-$1.0B | 2%-3% |
| Emerging markets | $1.0B-$1.8B | $1.5B-$2.7B | 5%-8% |
These are analyst-model estimates rather than consolidated manufacturer-reported figures. Pfizer reports Lipitor revenue, but generic atorvastatin sales are distributed across many companies and are not disclosed in a single audited global total.
What are the projected atorvastatin sales from 2025 to 2030?
The base case assumes continued volume growth, annual net price erosion of 1%-3% in mature markets, and higher demand in emerging economies.
| Year | Global market estimate | Base-case growth | Primary driver |
|---|---|---|---|
| 2024 | $3.4B | - | Baseline |
| 2025 | $3.5B | 3.0% | Prescription growth and broader screening |
| 2026 | $3.6B | 3.1% | Emerging-market expansion |
| 2027 | $3.7B | 3.2% | Chronic therapy persistence |
| 2028 | $3.8B | 3.3% | Combination products and guideline use |
| 2029 | $4.0B | 3.4% | Population aging and cardiovascular risk |
| 2030 | $4.1B | 3.5% | Continued volume growth despite price pressure |
Bull-case projection
The bull case reaches approximately $5.0 billion by 2030. It requires stronger statin adoption in China, India, Latin America, and Southeast Asia; increased treatment of high-risk patients; and sustained use of atorvastatin in combination cardiovascular regimens.
Bear-case projection
The bear case reaches approximately $3.2 billion by 2030. It assumes aggressive generic price competition, substitution by rosuvastatin, greater use of PCSK9 inhibitors in high-risk patients, and reduced adherence caused by intolerance or patient discontinuation.
The most likely outcome is volume growth with low-single-digit revenue growth. Atorvastatin is a mature generic market, so additional prescriptions do not translate directly into proportional sales increases.
Why does atorvastatin continue to generate substantial sales after patent expiry?
Atorvastatin retains commercial value because cardiovascular disease creates a large, recurring treatment population. Patients often take statins for many years, and the active ingredient has broad use across primary prevention, secondary prevention, diabetes-associated cardiovascular risk, and established coronary artery disease.
The main demand drivers are:
- Aging populations with higher cardiovascular risk.
- Expanded diagnosis of hyperlipidemia.
- Greater use of preventive therapy in diabetes and chronic kidney disease.
- Treatment intensification after myocardial infarction and stroke.
- Lower generic prices that improve payer access.
- Strong physician familiarity with atorvastatin.
- Availability in 10 mg, 20 mg, 40 mg, and 80 mg strengths.
- Use in fixed-dose combinations in markets where branded generics remain common.
The American Heart Association estimates that cardiovascular disease remains the leading global cause of death. The World Health Organization reported approximately 17.9 million cardiovascular deaths annually, supporting a large long-term prevention market (World Health Organization, 2021).
How does atorvastatin compare with rosuvastatin and other statins?
Atorvastatin competes primarily with rosuvastatin, simvastatin, pravastatin, and pitavastatin. Ezetimibe combinations and PCSK9 therapies compete for patients who require additional low-density lipoprotein cholesterol reduction.
| Drug | Market status | Relative LDL reduction | Commercial position |
|---|---|---|---|
| Atorvastatin | Generic, broad global availability | High | Largest volume franchise |
| Rosuvastatin | Generic, high potency | High to very high | Main share gainer |
| Simvastatin | Generic | Moderate | Mature and declining |
| Pravastatin | Generic | Moderate | Used where tolerability is prioritized |
| Pitavastatin | Generic or branded generic in selected markets | Moderate to high | Niche, higher-price positioning |
| Ezetimibe/atorvastatin | Generic or branded generic | Higher than statin alone | Combination-growth segment |
| PCSK9 inhibitors | Branded biologics | Very high | Specialist and high-risk patients |
Rosuvastatin is the most important competitive threat. Both drugs are potent, widely available, and inexpensive. Atorvastatin has greater historical prescribing depth and broader manufacturer coverage, while rosuvastatin benefits from high-intensity treatment demand and strong use in patients requiring substantial LDL reduction.
What is the FDA regulatory status of atorvastatin?
Atorvastatin is FDA-approved as atorvastatin calcium, an oral tablet indicated as an adjunct to diet for reducing LDL cholesterol and the risk of cardiovascular events in appropriate patients. Lipitor was originally approved in 1996. Multiple abbreviated new drug applications have since been approved for generic atorvastatin calcium tablets.
The FDA-approved strength range is generally 10 mg to 80 mg. The 80 mg dose is used for high-intensity treatment but has a smaller patient base than the 10 mg and 20 mg strengths.
Atorvastatin is a small-molecule drug. Biosimilar regulation does not apply. Generic manufacturers use the abbreviated new drug application pathway and must demonstrate pharmaceutical equivalence and bioequivalence rather than repeat the full clinical development program required for an innovator product.
What is the Orange Book status of atorvastatin?
The key Lipitor patent barriers have expired, and generic atorvastatin products are widely approved in the United States. Current commercial protection does not depend on an active composition-of-matter patent for the original atorvastatin product.
| Patent or protection | Relevance | Status |
|---|---|---|
| U.S. Patent No. 4,681,893 | Atorvastatin compound patent | Expired |
| Lipitor FDA approval | New drug approval | 1996 |
| Pediatric exclusivity | Added regulatory protection | Expired |
| U.S. generic launch | First major entry | November 2011 |
| Current generic market | Multiple ANDA holders | Active |
The precise Orange Book listing must be evaluated by product and strength because listed patents and regulatory exclusivity can change over time. The original Lipitor patent estate no longer prevents ordinary generic atorvastatin tablet entry.
When did atorvastatin lose exclusivity?
U.S. atorvastatin exclusivity effectively ended with generic entry in November 2011. Pfizer’s Lipitor sales fell sharply after the first generic launches. Pfizer reported Lipitor revenue of approximately $9.6 billion in 2011, followed by a steep decline as generic substitution accelerated (Pfizer, 2012).
| Milestone | Date |
|---|---|
| Lipitor FDA approval | 1996 |
| Peak annual Lipitor sales | Approximately $13.2B, 2006 |
| U.S. patent expiry and generic entry period | 2011 |
| First large-scale U.S. generic launches | November 2011 |
| Post-entry branded erosion | 2012 onward |
Generic entry was commercially disruptive because atorvastatin had unusually high prescription volume and strong pharmacy substitution potential. Pfizer retained some branded sales through pricing, contracting, and authorized-generic strategies, but the original blockbuster economics did not return.
What patents protect atorvastatin today?
The original atorvastatin compound patent and Lipitor’s core market protection are expired. Potentially relevant rights may still exist around:
- Fixed-dose combinations.
- Modified-release or alternative dosage forms.
- Manufacturing processes.
- Salt, polymorph, or crystalline forms.
- Specific formulations or excipients.
- New therapeutic uses.
- Combination treatment regimens.
These rights generally do not recreate broad exclusivity over conventional atorvastatin calcium tablets. Their commercial value depends on claim scope, enforceability, regulatory labeling, and whether physicians prescribe the protected use or formulation.
What formulations are protected by atorvastatin patents?
Formulation patents may cover tablet composition, dissolution characteristics, stability, particle size, coating, or manufacturing processes. A formulation patent can delay or complicate entry into a specific product configuration but usually does not prevent an ANDA applicant from marketing a non-infringing conventional tablet.
Fixed-dose combinations have greater potential for differentiated protection. Products combining atorvastatin with amlodipine, ezetimibe, or antihypertensive agents may have separate patent histories and regulatory approvals. The patent analysis must be conducted at the product level rather than assumed from the atorvastatin active ingredient.
Are there Paragraph IV challenges for atorvastatin?
Paragraph IV litigation was central to the original generic-entry process, but conventional atorvastatin tablets are now a mature generic category. New Paragraph IV activity is more likely to concern:
- A branded combination product.
- A new dosage form.
- A formulation patent.
- A new method of use.
- A recently approved fixed-dose combination.
A Paragraph IV certification asserts that a listed patent is invalid, unenforceable, or will not be infringed. Under the Hatch-Waxman framework, the patent holder may file an infringement action within 45 days, potentially triggering a 30-month stay of FDA approval for the relevant ANDA.
For ordinary atorvastatin calcium tablets, the commercial risk from a new Paragraph IV case is limited because multiple generic suppliers already operate in the market. For a protected combination product, the risk can be material if the product has high prescription value and few substitutes.
Which companies sell generic atorvastatin?
The global supplier base includes multinational generic companies, regional branded-generic manufacturers, and contract manufacturers. Major companies with atorvastatin products or historical supply positions include:
- Viatris.
- Teva Pharmaceutical Industries.
- Sandoz.
- Sun Pharmaceutical Industries.
- Dr. Reddy’s Laboratories.
- Cipla.
- Torrent Pharmaceuticals.
- Zydus Lifesciences.
- Lupin.
- Aurobindo Pharma.
- Accord Healthcare.
- Amneal Pharmaceuticals.
The competitive structure differs by country. The United States has strong pharmacy-benefit-manager purchasing pressure and low unit prices. India and parts of Southeast Asia have more branded-generic competition, allowing manufacturers to differentiate through physician promotion, packaging, distribution, and combination products.
What is the generic launch risk for atorvastatin?
Generic launch risk is high for any new conventional atorvastatin tablet because the market already has many suppliers and limited product differentiation. A new entrant would face:
- Low wholesale pricing.
- High payer and pharmacy concentration.
- Commodity-like active pharmaceutical ingredient sourcing.
- Limited brand loyalty.
- Price erosion after additional approvals.
- Inventory and supply-chain requirements.
- Manufacturing compliance risk.
The opportunity is stronger in markets with fragmented distribution, limited generic competition, or demand for fixed-dose cardiovascular combinations. Manufacturing scale, regulatory history, API security, and reliable supply are more important than patent exclusivity for ordinary atorvastatin.
What is the revenue exposure from Lipitor and atorvastatin?
Lipitor was one of the largest pharmaceutical products in history. Its peak sales illustrate the difference between innovator economics and mature generic economics.
| Period | Commercial position | Revenue implication |
|---|---|---|
| 1997-2006 | Broad patent-protected growth | Rapid expansion and premium pricing |
| 2007-2011 | Mature branded blockbuster | Approximately $9B-$13B annual sales |
| 2012-2015 | Rapid generic substitution | Sharp branded revenue decline |
| 2016-present | Generic market | High volume, low unit price |
The residual revenue opportunity is distributed across manufacturers rather than concentrated in Pfizer. For investors, the key metric is not Lipitor brand revenue but manufacturer share, tablet volume, net price, and exposure to regulated markets.
How strong is the atorvastatin patent estate?
The original patent estate is weak as a barrier to conventional generic entry because the core compound rights have expired. The broader intellectual-property position is moderate only for selected combinations, formulations, manufacturing methods, or later-developed uses.
| Patent factor | Assessment |
|---|---|
| Core compound protection | Expired |
| Conventional tablet protection | Low |
| Fixed-dose combinations | Product-specific, potentially moderate |
| Manufacturing patents | Narrow and process-dependent |
| Method-of-use patents | Usually limited by labeling and enforceability |
| Biosimilar protection | Not applicable |
| Generic entry barrier | Low for standard tablets |
The principal commercial barrier is operational rather than legal. A manufacturer needs compliant production, approved regulatory filings, reliable API supply, and cost-efficient distribution.
What are the main risks to the atorvastatin forecast?
The largest downside risks are generic price compression, substitution by rosuvastatin, tighter reimbursement controls, and increasing use of non-statin therapies in high-risk patients. PCSK9 inhibitors and inclisiran may capture a larger share of patients who fail to reach LDL targets with statins, although their higher prices limit broad replacement of atorvastatin.
Upside risks include expanded screening, improved adherence, growth in cardiovascular care in emerging markets, and broader use of high-intensity statin therapy after cardiovascular events.
Key Takeaways
- Atorvastatin is a mature, global generic franchise with estimated 2024 sales of about $3.4 billion in the base case.
- Global revenue could reach approximately $4.1 billion by 2030, with unit growth exceeding revenue growth.
- The original Lipitor patent estate no longer blocks conventional generic atorvastatin tablets.
- The U.S. market is low-growth and price-sensitive; emerging markets provide the strongest volume opportunity.
- Rosuvastatin is the principal competitive threat.
- Fixed-dose combinations and differentiated formulations offer more commercial potential than standard atorvastatin tablets.
- Biosimilar risk does not apply because atorvastatin is a small-molecule drug.
- Manufacturing scale, API sourcing, regulatory compliance, and distribution are more important than core patent exclusivity.
- New Paragraph IV litigation is most relevant to combination products and specialized formulations, not ordinary atorvastatin tablets.
Frequently Asked Questions
Is atorvastatin still a profitable drug?
Yes, but profitability has shifted from the innovator to efficient generic manufacturers. High prescription volume supports revenue, while price competition limits per-tablet margins.
What is the expected atorvastatin CAGR through 2030?
A reasonable base-case estimate is approximately 3.2% in global nominal sales, with a range of 3%-5% depending on emerging-market growth and generic price erosion.
Does Pfizer still own important atorvastatin exclusivity?
Pfizer retains the Lipitor brand, but the core atorvastatin tablet exclusivity has expired. Pfizer no longer has the broad patent-based control it held before generic entry.
Can a new company launch a generic atorvastatin tablet?
Yes, subject to FDA or other national regulatory approval, pharmaceutical-equivalence requirements, bioequivalence, manufacturing compliance, and commercial viability. Patent risk is generally low for standard tablets.
Will PCSK9 drugs replace atorvastatin?
They are unlikely to replace atorvastatin broadly. PCSK9 therapies are more expensive and are mainly used for patients with very high cardiovascular risk, familial hypercholesterolemia, or inadequate response to conventional therapy.
References
-
Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs database. U.S. Department of Health and Human Services.
-
Pfizer Inc. (2012). 2011 annual report. Pfizer.
-
World Health Organization. (2021). Cardiovascular diseases. https://www.who.int/health-topics/cardiovascular-diseases
-
U.S. Patent and Trademark Office. (1987). U.S. Patent No. 4,681,893: Trans-6-[2-(substituted pyrrol-1-yl)alkyl]-4-hydroxypyran-2-ones. U.S. Department of Commerce.
-
American Heart Association. (2024). Heart disease and stroke statistics: 2024 update. Circulation.
More… ↓
