Share This Page
Drug Sales Trends for SEVELAMER
✉ Email this page to a colleague
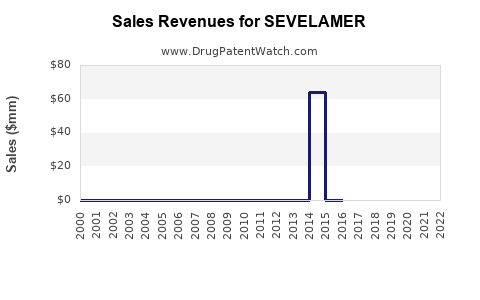
Annual Sales Revenues and Units Sold for SEVELAMER
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| SEVELAMER | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| SEVELAMER | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| SEVELAMER | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| SEVELAMER | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| SEVELAMER | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| SEVELAMER | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| SEVELAMER | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Sevelamer Market Analysis, Sales Forecast, Patent Status, and Generic Competition
Sevelamer is a mature phosphate binder used primarily in patients with chronic kidney disease and dialysis-dependent end-stage renal disease. The market is shifting from branded Renvela and Renagel products to lower-priced generic sevelamer carbonate and sevelamer hydrochloride. Global sevelamer sales are estimated at approximately $1.0 billion to $1.3 billion in 2024, with a base-case decline to $850 million to $1.1 billion by 2030 as generic penetration increases and dialysis populations grow gradually.
The market remains commercially durable because phosphate control is a recurring treatment requirement. Revenue growth is limited by generic substitution, payer pressure, tablet burden, competing binders such as sucroferric oxyhydroxide and ferric citrate, and the use of calcium-based phosphate binders in cost-sensitive markets.
What is sevelamer and how is it used?
Sevelamer is a nonabsorbed, cross-linked polymer that binds dietary phosphate in the gastrointestinal tract. It is administered orally with meals to reduce serum phosphorus in adults with chronic kidney disease on dialysis. The two principal active ingredients are sevelamer hydrochloride and sevelamer carbonate.
| Product | Active ingredient | Dosage forms | Original commercial sponsor |
|---|---|---|---|
| Renagel | Sevelamer hydrochloride | Tablets | Genzyme, later Sanofi |
| Renvela | Sevelamer carbonate | Tablets and powder for oral suspension | Genzyme, later Sanofi |
| Generic products | Sevelamer hydrochloride or carbonate | Tablets, powder, suspension formulations | Multiple manufacturers |
Renvela has largely replaced Renagel in commercial importance because sevelamer carbonate avoids the chloride load associated with sevelamer hydrochloride. The FDA label supports use in adults on dialysis and includes tablet and powder-for-suspension dosing options.[1]
How large is the sevelamer market?
The global sevelamer market is estimated at $1.0 billion to $1.3 billion in 2024. Published market estimates differ because some reports include only branded products, while others include generic sales, hospital procurement, and regional formulations.
Estimated 2024 market by region
| Region | Estimated 2024 market | Share of global market | Market characteristics |
|---|---|---|---|
| United States | $350 million-$500 million | 30%-38% | High dialysis spending, extensive generic substitution |
| Europe | $250 million-$350 million | 22%-28% | Strong generic and tender activity |
| Japan | $150 million-$220 million | 13%-17% | Large dialysis population and established sevelamer use |
| China | $100 million-$180 million | 8%-14% | Growing dialysis base and local competition |
| Other markets | $150 million-$250 million | 12%-20% | Variable reimbursement and generic access |
| Global total | $1.0 billion-$1.3 billion | 100% | Mature, recurring-use market |
The United States remains the largest single commercial market, but it is no longer a branded-growth market. Generic sevelamer carbonate has reduced average selling prices, while Medicare reimbursement and dialysis-provider purchasing constrain pricing.
What are the sevelamer sales projections through 2030?
The base case assumes continued dialysis-patient growth, stable clinical use of non-calcium binders, and annual price erosion of approximately 4% to 7% in markets with established generic competition.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $1.0B | $1.15B | $1.3B |
| 2025 | $970M | $1.10B | $1.29B |
| 2026 | $930M | $1.06B | $1.28B |
| 2027 | $900M | $1.02B | $1.27B |
| 2028 | $870M | $980M | $1.26B |
| 2029 | $840M | $950M | $1.25B |
| 2030 | $810M | $920M | $1.24B |
Forecast assumptions
The base-case forecast implies a compound annual growth rate of approximately negative 3.6% from 2024 through 2030. The main assumptions are:
- Dialysis patient growth of approximately 2% to 4% annually in major markets.
- Generic penetration rising in the United States and Europe.
- Net price erosion offsetting much of the volume increase.
- Continued use in patients with hyperphosphatemia who require non-calcium phosphate binders.
- Limited expansion into new indications.
- No major clinical event that materially displaces sevelamer.
The bull case assumes stronger growth in dialysis populations in China, India, Latin America, and other emerging markets, with slower generic price erosion. The bear case assumes faster conversion to iron-based binders and more aggressive government procurement discounts.
Which companies sell sevelamer?
The commercial market has three levels: originator products, generic manufacturers, and regional distributors.
Originator and branded suppliers
Sanofi commercialized Renagel and Renvela after acquiring Genzyme. Sanofi has progressively reduced the strategic importance of sevelamer as the products matured and generic competition expanded. Renvela remains recognized by nephrologists and dialysis providers, but its commercial value is below the level achieved before generic entry.
Generic manufacturers
Generic sevelamer products have been supplied by multiple manufacturers and contract manufacturers. The competitive field varies by country and dosage form. In the United States, suppliers can enter through abbreviated new drug applications, while European suppliers typically rely on national or decentralized marketing authorization procedures.
The most important competitive variables are:
- Tablet strength and pack size.
- Powder-for-suspension availability.
- Bioequivalence or product-specific regulatory requirements.
- Manufacturing consistency for a cross-linked polymer.
- Distribution access to dialysis providers.
- Contracting with group purchasing organizations.
- Ability to support Medicare and Medicaid pricing.
What is the FDA regulatory status of sevelamer?
Sevelamer hydrochloride and sevelamer carbonate are FDA-approved prescription phosphate binders. Renagel was approved before Renvela, and Renvela is approved in tablet and powder formulations.[1][2]
Generic competition is available for both active-ingredient forms. The FDA regulatory pathway is generally an ANDA pathway for products that meet applicable pharmaceutical equivalence and bioequivalence requirements. Sevelamer is not a biologic, so biosimilar regulation does not apply.
The regulatory risks are formulation-specific. A generic tablet must match critical quality attributes, including polymer composition, particle characteristics, dissolution behavior, impurity profile, and dose uniformity. Powder products also require reliable reconstitution and acceptable suspension performance.
What is the Orange Book status of sevelamer?
The FDA Orange Book is the principal source for current listed patents, exclusivity, therapeutic-equivalence ratings, and reference-listed-drug information.[3]
Sevelamer is no longer protected by the type of market exclusivity associated with a newly approved product. The commercial question is therefore not whether the active ingredient has regulatory exclusivity, but whether any remaining formulation, process, or method-of-use claims can delay or complicate generic entry.
The Orange Book position should be evaluated by product and dosage form:
| Product | Regulatory position | Commercial implication |
|---|---|---|
| Renagel tablets | Mature product with generic competition | Limited originator pricing power |
| Renvela tablets | Mature product with generic competition | Generic substitution is the primary risk |
| Renvela powder | More formulation-sensitive | Potentially stronger manufacturing and quality barriers |
| Generic carbonate tablets | ANDA-based competition | Price competition and tender pressure |
| Generic hydrochloride tablets | Older product class | Lower differentiation and intense competition |
Patent listings and expiration dates can change as FDA records are updated. A transaction or litigation analysis should use the current Orange Book entry rather than historical patent summaries.
What patents protect sevelamer formulations and methods of use?
The strongest historical patent protection covered:
- The cross-linked polymer composition.
- Pharmaceutical compositions containing sevelamer.
- Tablet manufacturing and excipient systems.
- Powder formulations for oral suspension.
- Processes for producing the polymer.
- Methods for treating hyperphosphatemia.
The original composition patents for sevelamer hydrochloride and carbonate have expired or reached the end of their commercial life in major markets. Any remaining patent value is more likely to arise from narrow formulation, manufacturing, or use claims than from broad coverage of sevelamer itself.
Formulation patent risk
Formulation patents can matter where they cover:
- A specific polymer particle-size distribution.
- Reduced tablet size or improved swallowability.
- A stable powder formulation.
- Improved suspension characteristics.
- A particular binder or excipient system.
- Manufacturing controls that affect phosphate-binding capacity.
These claims are commercially relevant because sevelamer tablets can require multiple tablets per meal and because product quality depends on polymer structure. A generic sponsor can still challenge such claims through Paragraph IV certification or design around them.
When does sevelamer lose exclusivity?
Sevelamer’s principal exclusivity loss occurred in stages rather than on one single date. Renagel and Renvela moved from originator protection to generic competition as composition and formulation patents expired and ANDA applicants entered the market.
Exclusivity timeline
| Period | Event | Market effect |
|---|---|---|
| 1990s | Renagel development and approval | Originator control begins |
| 2000s | Renvela approval | Carbonate formulation broadens product franchise |
| Early-to-mid 2010s | Core patent protection weakens | Generic development accelerates |
| Late 2010s | Generic sevelamer products gain access | Price erosion begins |
| 2020s | Mature generic market | Volume growth does not translate into revenue growth |
| 2025-2030 | Continued formulation and tender competition | Originator revenue declines; generic volume rises |
A precise patent-expiration analysis must be performed by jurisdiction, product, patent, and dosage form. Patent-term adjustments, pediatric extensions, terminal disclaimers, and settlement agreements can alter the effective entry date.
Which companies are challenging sevelamer patents?
Generic manufacturers have challenged or bypassed originator protection through the standard ANDA and patent-certification framework. The relevant parties have included manufacturers seeking approval for sevelamer carbonate and hydrochloride tablets or powder formulations.
Public litigation risk is lower than for high-value small molecules because sevelamer is already a mature generic product. The greater commercial risk is parallel generic entry, which can reduce prices without requiring a prolonged patent dispute.
Paragraph IV exposure is most relevant when a generic applicant certifies that an Orange Book-listed patent is invalid, unenforceable, or not infringed. A first-filer position can create 180-day generic exclusivity under the Hatch-Waxman framework, but the economic value of that exclusivity is constrained when multiple products enter after resolution or when market prices are already low.
What patent litigation affects sevelamer?
Sevelamer litigation has historically centered on generic entry, formulation claims, and the scope of listed patents. The commercial importance of any dispute depends on:
- The number of generic applicants.
- Whether the patent covers all major dosage forms.
- Whether the product has first-filer exclusivity.
- The availability of alternative sevelamer formulations.
- The likely duration of an injunction.
- The number of dialysis-provider contracts that can be retained.
Because sevelamer is a polymer and not a conventional low-molecular-weight compound, technical arguments may focus on polymer characterization, equivalence, manufacturing parameters, and product performance rather than only on chemical identity.
How does sevelamer compare with competing phosphate binders?
| Product | Active ingredient | Main advantage | Main commercial constraint |
|---|---|---|---|
| Sevelamer | Polymer | No calcium or aluminum load; extensive clinical use | High pill burden and generic pricing |
| Sucroferric oxyhydroxide | Iron-based complex | Lower pill burden in many patients | Higher cost and gastrointestinal tolerability issues |
| Ferric citrate | Iron-based compound | Phosphate binding and iron delivery | Iron-related monitoring and payer restrictions |
| Calcium acetate | Calcium salt | Low cost and broad availability | Calcium load and vascular-calcification concerns |
| Lanthanum carbonate | Lanthanum salt | Lower tablet burden than some alternatives | Cost and gastrointestinal effects |
Sevelamer’s strongest competitive position is in patients for whom clinicians want to avoid calcium-based binders. Its weakest position is against low-cost calcium acetate in markets where reimbursement dominates clinical preference.
Iron-based binders represent the principal branded competitive threat. Their adoption depends on pill burden, iron parameters, gastrointestinal tolerability, formulary placement, and total treatment cost.
What generic entry risks exist for sevelamer?
The generic-entry risk is high and persistent. Key risks include:
- Multiple approved generic suppliers.
- Limited differentiation between chemically equivalent products.
- Annual price reductions in the mid-single digits or higher.
- Pharmacy substitution for tablet products.
- Dialysis-provider purchasing concentration.
- Private-label and contract-manufactured products.
- Regional tender losses.
- Lower prescriber attachment to the originator brand.
The powder formulation may retain greater commercial defensibility than standard tablets because manufacturing and quality requirements are more demanding. That advantage does not eliminate generic risk because a competing powder can still capture institutional and payer contracts.
What licensing deals and partnerships affect sevelamer?
Sevelamer’s commercial history has been shaped more by acquisition and commercialization arrangements than by recent high-value licensing transactions. Genzyme developed and commercialized the original franchise, and Sanofi later acquired Genzyme. Generic suppliers typically rely on contract manufacturing, distribution agreements, or regional marketing partnerships rather than global licensing deals.
Potential transaction value is concentrated in:
- Regional rights in emerging markets.
- Powder formulations.
- Hospital and dialysis-provider supply contracts.
- Manufacturing technology.
- Combination products that reduce pill burden.
- Distribution platforms serving nephrology clinics.
A standalone sevelamer asset is unlikely to command a premium valuation based only on active-ingredient ownership. Value depends on cost of goods, regulatory approvals, supply reliability, and access to institutional buyers.
How much revenue is exposed to sevelamer patent and generic risk?
The global revenue pool exposed to generic and pricing risk is approximately $1.0 billion to $1.3 billion annually. The originator share is much smaller than the total product-market value because generics have captured a substantial portion of volume.
A practical exposure framework is:
| Revenue category | Estimated exposure |
|---|---|
| Originator-branded revenue | $150M-$300M globally |
| Generic revenue | $650M-$900M globally |
| Institutional and tender business | $200M-$350M globally |
| Revenue exposed to further price erosion | $500M-$800M |
The largest risk is not abrupt loss of all demand. It is a gradual decline in net price, market share, and contract value while the treated patient population continues to expand.
Key Takeaways
- Sevelamer is a mature, recurring-use phosphate binder with estimated global sales of $1.0 billion to $1.3 billion in 2024.
- Base-case global sales are projected to decline to approximately $920 million by 2030.
- Generic competition is the primary commercial risk for Renvela and Renagel.
- Sevelamer carbonate has stronger long-term relevance than sevelamer hydrochloride because it avoids chloride loading.
- Formulation and manufacturing claims have more residual patent value than broad composition claims.
- Sevelamer is not a biologic and has no biosimilar risk.
- Iron-based phosphate binders are the main branded competitive threat.
- The powder formulation may have higher technical barriers than standard tablets.
- Market growth from dialysis expansion is unlikely to offset generic price erosion in developed markets.
- Commercial value depends on manufacturing cost, institutional contracting, regulatory approvals, and reliable supply.
FAQs
Is sevelamer still a profitable drug?
Yes, but profitability depends on manufacturing scale, generic market share, and institutional contracts. Originator margins have declined sharply, while efficient generic suppliers can remain profitable at lower prices.
Is Renvela better than generic sevelamer carbonate?
Both products contain sevelamer carbonate, but product performance, tablet characteristics, excipients, supply reliability, and payer status can differ. Clinical substitution depends on regulatory equivalence and local prescribing rules.
Does sevelamer have biosimilar competition?
No. Sevelamer is a synthetic polymer, not a biologic. Competition occurs through generic-drug pathways rather than biosimilar pathways.
Which sevelamer formulation has the strongest commercial outlook?
Sevelamer carbonate powder for oral suspension has the strongest potential differentiation because it involves more complex formulation and manufacturing requirements. Standard tablets remain the largest volume segment but face the greatest price pressure.
Will dialysis growth increase sevelamer sales?
Dialysis growth will increase treated volume, particularly in emerging markets. In the United States, Europe, and Japan, generic price erosion and competition from iron-based binders are likely to offset much of the volume increase.
References
- U.S. Food and Drug Administration. (2023). Renvela: Sevelamer carbonate prescribing information. FDA.
- U.S. Food and Drug Administration. (2023). Renagel: Sevelamer hydrochloride prescribing information. FDA.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
- Kidney Disease: Improving Global Outcomes. (2017). KDIGO 2017 clinical practice guideline update for the diagnosis, evaluation, prevention, and treatment of chronic kidney disease-mineral and bone disorder. Kidney International Supplements, 7(1), 1-59.
- Sanofi. (2023). Annual report 2023. Sanofi.
- U.S. Renal Data System. (2023). 2023 USRDS annual data report: Epidemiology of kidney disease in the United States. National Institute of Diabetes and Digestive and Kidney Diseases.
More… ↓
