Share This Page
Drug Sales Trends for ROSUVASTATIN
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ROSUVASTATIN (2016)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
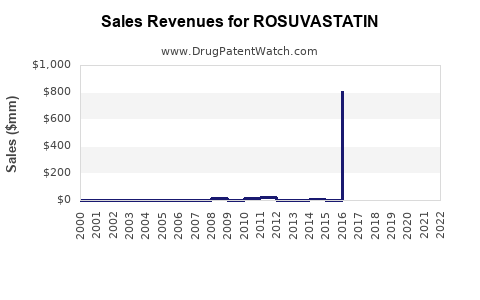
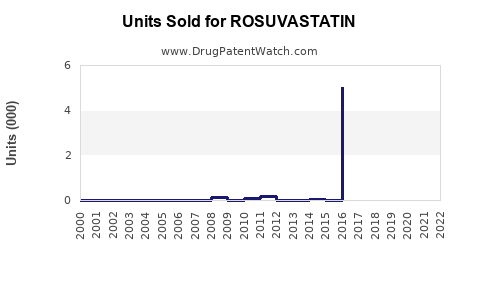
Annual Sales Revenues and Units Sold for ROSUVASTATIN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ROSUVASTATIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ROSUVASTATIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ROSUVASTATIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ROSUVASTATIN | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Rosuvastatin Market Analysis, Sales Projections, Patent Status, and Generic Competition
Rosuvastatin is a mature, high-volume statin with declining branded revenue and durable generic demand. The commercial opportunity is concentrated in generic volume, combination products, emerging markets, and high-intensity lipid management. Global rosuvastatin sales are estimated at approximately $3.0 billion in 2024, with a base-case market value of $3.4 billion by 2029, representing roughly 2.5% annual growth. Unit demand should grow faster than revenue because US and European generic prices remain under pressure.
AstraZeneca's branded Crestor has lost its former revenue scale. The competitive market is led by rosuvastatin generics, atorvastatin, ezetimibe combinations, and newer LDL-lowering agents such as PCSK9 inhibitors and bempedoic acid.
What is the current rosuvastatin market size?
Rosuvastatin is one of the largest global statin products by prescription volume and a major component of cardiovascular generic spending. The market includes rosuvastatin calcium tablets in 5 mg, 10 mg, 20 mg, and 40 mg strengths, as well as fixed-dose combinations with ezetimibe and other cardiovascular agents.
Global rosuvastatin market estimate
Public company reports generally disclose branded Crestor revenue, not total global rosuvastatin sales. The following estimate uses branded sales history, generic prescription penetration, public price erosion trends, and regional cardiovascular-treatment growth.
| Metric | 2024 estimate | 2029 base case | 2024-2029 outlook |
|---|---|---|---|
| Global rosuvastatin market value | $2.9-$3.2 billion | $3.2-$3.7 billion | 1.8%-3.1% CAGR |
| Generic share by volume | More than 90% | More than 94% | Continued increase |
| Branded Crestor share by value | Low single digits globally | Approximately 1% or lower | Decline |
| Primary growth driver | Prescription volume | Cardiovascular diagnosis and treatment expansion | Moderate |
| Main constraint | Generic price erosion | Mature-market reimbursement pressure | Persistent |
The base case is a $3.0 billion 2024 market expanding to $3.4 billion in 2029. This projection excludes most combination-product revenue where companies report the product under a separate commercial category.
What drives rosuvastatin demand?
Demand is supported by:
- Expanded treatment of high-risk patients under cardiovascular prevention guidelines.
- Increased diagnosis of diabetes, chronic kidney disease, and dyslipidemia.
- Use of high-intensity statin therapy for secondary prevention.
- Generic affordability in emerging markets.
- Continued use in patients who require substantial LDL-cholesterol reduction.
- Broader adoption of 20 mg and 40 mg doses in high-risk populations.
Demand is limited by statin intolerance, treatment discontinuation, therapeutic substitution to atorvastatin, and migration of some high-risk patients to PCSK9 inhibitors or other non-statin therapies.
What are the rosuvastatin sales projections through 2029?
The expected market trajectory is volume-led rather than price-led. Generic prescription growth should offset lower average selling prices in North America and Western Europe.
| Scenario | 2024 market | 2029 market | CAGR | Principal assumptions |
|---|---|---|---|---|
| Downside | $2.9 billion | $2.8 billion | -0.7% | Severe price erosion, limited diagnosis growth, stronger atorvastatin substitution |
| Base case | $3.0 billion | $3.4 billion | 2.5% | Moderate volume growth and stable emerging-market pricing |
| Upside | $3.2 billion | $4.0 billion | 4.6% | Higher cardiovascular screening, stronger combination-product demand, slower price erosion |
Regional sales outlook
| Region | 2024 commercial profile | 2029 outlook |
|---|---|---|
| United States | Mature generic market with significant price competition | Stable or modest volume growth; declining unit economics |
| Western Europe | Predominantly generic, centralized reimbursement | Low revenue growth and continued tender pressure |
| Japan | Established demand with pricing controls | Low-single-digit value change |
| China | Large patient pool and expanding cardiovascular treatment | Volume growth with competitive pricing |
| India | Strong generic manufacturing and domestic demand | Volume growth, low average prices |
| Latin America | Mixed branded-generic market | Above-market volume growth in selected countries |
| Middle East and Africa | Lower baseline penetration | High percentage growth from a small base |
China, India, Brazil, and other emerging markets offer the strongest volume growth. The United States remains strategically important for scale, but its profitability is constrained by group purchasing organizations, pharmacy benefit managers, wholesaler concentration, and generic competition.
How does rosuvastatin compare with atorvastatin?
Rosuvastatin and atorvastatin compete directly in primary prevention, secondary prevention, diabetes, and high-risk cardiovascular disease. Atorvastatin remains the larger global statin by prescription volume in many markets, while rosuvastatin has a strong position in high-intensity therapy.
| Factor | Rosuvastatin | Atorvastatin |
|---|---|---|
| Originator brand | Crestor | Lipitor |
| Main originator | AstraZeneca | Pfizer |
| Generic availability | Broad | Broad |
| High-intensity doses | 20 mg and 40 mg | 40 mg and 80 mg |
| LDL reduction | Strong milligram-for-milligram potency | Strong clinical use and extensive evidence |
| Generic pricing | Highly competitive | Highly competitive |
| Combination opportunity | Ezetimibe and other cardiovascular combinations | Ezetimibe and antihypertensive combinations |
| Competitive position | Strong in high-intensity and certain intolerance-switch patients | Broadest historical statin utilization |
| Patent risk | Originator estate largely exhausted | Originator estate largely exhausted |
Rosuvastatin can command a modest price premium over atorvastatin in certain countries because of potency, physician preference, or local brand positioning. That premium is narrowing as generic suppliers expand.
What patents protect rosuvastatin?
The core rosuvastatin composition-of-matter and salt patent protection has expired or no longer prevents ordinary generic entry in major markets. The principal US patent historically associated with Crestor was U.S. Patent No. 6,316,023, covering rosuvastatin-related compounds and assigned to Shionogi. Its effective life extended beyond the basic statutory term through patent-term adjustments and pediatric considerations, but it no longer provides a current barrier to standard rosuvastatin tablet competition.
Rosuvastatin patent estate
| Patent category | Commercial relevance |
|---|---|
| Core molecule | Expired or exhausted in major markets |
| Rosuvastatin calcium salt | Historically important; no longer a broad generic-entry barrier |
| Tablet formulation | May remain relevant in specific jurisdictions or products |
| Particle size and crystalline form | Potentially relevant to process or formulation claims |
| Combination products | Separate patents may cover rosuvastatin plus ezetimibe or other actives |
| Manufacturing processes | Can affect freedom to operate without blocking ordinary tablet sales |
| Method-of-use claims | Possible residual claims, but generally limited against routine statin prescribing |
The strongest remaining intellectual-property positions are product-specific patents involving combinations, release characteristics, particle engineering, manufacturing processes, or jurisdiction-specific formulations. These patents do not recreate the commercial protection once provided by the core molecule patent.
When did rosuvastatin lose exclusivity?
Crestor received US Food and Drug Administration approval in 2003. The five-year new chemical entity exclusivity period ended in 2008, subject to pediatric exclusivity considerations. AstraZeneca's US commercial protection continued through patent litigation and settlement arrangements.
The US generic market opened in 2016, when FDA-approved generic rosuvastatin products entered following agreements involving AstraZeneca and generic manufacturers. This event sharply reduced Crestor revenue and changed rosuvastatin from a branded specialty product into a large generic category.
Rosuvastatin exclusivity timeline
| Date | Event |
|---|---|
| 1990s | Rosuvastatin patent filings and development activity |
| 2003 | FDA approval of Crestor in the United States |
| 2008 | New chemical entity exclusivity period ends |
| 2010-2015 | Patent disputes and settlement-related commercial restrictions |
| 2016 | US generic rosuvastatin entry begins |
| 2016 onward | Accelerated branded sales erosion |
| 2024-2025 | Mature generic market with residual formulation and combination activity |
Exact market entry dates differed by manufacturer and jurisdiction. Generic launch timing was governed by FDA approval status, patent certifications, litigation outcomes, and settlement terms.
What is the Orange Book status of rosuvastatin?
The FDA Orange Book historically listed Crestor patents and pediatric exclusivity information. Current Orange Book relevance is limited for ordinary rosuvastatin calcium tablets because the principal protection that delayed generic entry has expired or ceased to operate as a practical barrier.
An abbreviated new drug application applicant could challenge listed patents through a Paragraph IV certification or certify that a listed patent had expired. The regulatory effect depended on the patent's listing status, the timing of certification, and whether the brand sponsor filed patent litigation within the statutory period.
Paragraph IV challenges to Crestor
Paragraph IV litigation was central to the US rosuvastatin launch sequence. Generic applicants sought approval before the full commercial life of the brand product ended. The disputes focused on the scope and validity of the relevant rosuvastatin patents, including claims involving the active compound and pharmaceutical compositions.
The principal commercial outcome was authorized or settlement-enabled generic access in 2016 rather than an extended period of effective exclusivity into the 2020s. Current Paragraph IV risk is more relevant to later rosuvastatin combinations and specialized formulations than to conventional immediate-release rosuvastatin tablets.
Which companies manufacture generic rosuvastatin?
The US and global supply base includes multinational generic companies, regional manufacturers, and vertically integrated API producers. Manufacturer participation changes by country and dosage strength.
Representative companies with historical or current rosuvastatin products include:
- Teva Pharmaceutical Industries.
- Viatris and its predecessor Mylan businesses.
- Dr. Reddy's Laboratories.
- Sun Pharmaceutical Industries.
- Lupin.
- Zydus Lifesciences.
- Torrent Pharmaceuticals.
- Cipla.
- Apotex.
- Sandoz.
- Hikma Pharmaceuticals.
- Accord Healthcare.
- Aurobindo Pharma.
- Zhejiang Jingxin Pharmaceutical and other Chinese suppliers.
The commercial market is fragmented at the manufacturing level but concentrated at the procurement level. A supplier can obtain substantial prescription volume without achieving attractive margins because wholesalers and payers exert strong price pressure.
What formulations are protected by rosuvastatin patents?
Standard immediate-release tablets have limited current patent protection in the major generic markets. Commercially relevant formulation opportunities include:
Rosuvastatin and ezetimibe combinations
Fixed-dose rosuvastatin-ezetimibe products can improve adherence and reduce pill burden. Their value proposition is strongest in patients who require high-intensity LDL reduction but do not reach target levels on statin monotherapy.
Combination-product patents may cover:
- Specific rosuvastatin and ezetimibe ratios.
- Tablet layers or bilayer designs.
- Dissolution profiles.
- Stabilizers and excipients.
- Manufacturing processes.
- Dose-specific presentations.
These products can support higher pricing than plain rosuvastatin, but the opportunity is exposed to combination-generic competition and reimbursement controls.
Other formulation opportunities
Potentially differentiated products include:
- Modified-release rosuvastatin.
- Sprinkle or oral-dispersible formulations.
- Pediatric dosage forms.
- Fixed-dose cardiovascular combinations.
- Lower-dose products for statin-intolerant patients.
- Hospital or adherence-focused packaging.
The regulatory and commercial value of these products depends on clinical differentiation. A formulation patent without a meaningful adherence, tolerability, or dosing advantage is unlikely to sustain a durable premium.
What patent litigation and settlement agreements affected rosuvastatin?
Crestor faced generic patent challenges before US generic entry. AstraZeneca litigated against generic applicants and entered commercial arrangements that permitted eventual generic access. These disputes delayed unrestricted generic competition but did not preserve long-term branded market exclusivity.
Current litigation risk is more likely to arise from:
- ANDA challenges to combination products.
- Formulation patents.
- Process patents.
- Orange Book listing disputes.
- Antitrust claims involving settlements.
- Patent infringement claims involving crystalline forms or manufacturing routes.
The core rosuvastatin tablet market has low litigation intensity compared with newer branded medicines because the principal composition-of-matter protection is no longer commercially blocking.
Is biosimilar risk relevant to rosuvastatin?
No. Rosuvastatin is a chemically synthesized small molecule, not a biologic. Biosimilar regulation does not apply. Competitive entry occurs through generic-drug pathways, primarily abbreviated new drug applications in the United States and equivalent generic procedures in other markets.
This distinction lowers regulatory complexity relative to biologic products. Generic manufacturers generally do not need to reproduce the clinical development program required for a new active pharmaceutical ingredient. Bioequivalence, chemistry, manufacturing, controls, labeling, and facility compliance remain critical.
What generic entry risks exist for rosuvastatin?
The principal risk is not first entry. It is sustained price erosion and supply-chain competition.
Generic launch scenarios
| Scenario | Market effect | Likely timing |
|---|---|---|
| Additional US suppliers | Lower prices and higher substitution | Ongoing |
| Consolidation among API suppliers | Temporary supply disruption or price recovery | Intermittent |
| Combination-product launches | Value migration from plain tablets | 2025-2029 |
| Tender losses in Europe | Rapid revenue decline for individual suppliers | Contract cycle dependent |
| Regulatory warning or facility action | Short-term shortages and share shifts | Event driven |
| New delivery format | Niche premium opportunity | Limited |
Manufacturing barriers are moderate. Rosuvastatin API production requires control of stereochemistry, impurities, particle properties, and salt formation, but the chemistry is established. The main barriers are FDA or European Medicines Agency compliance, validated supply, customer qualification, and reliable access to low-cost API.
What is the revenue exposure for AstraZeneca?
Crestor was historically one of AstraZeneca's major products. Its revenue declined materially after generic entry. The brand's remaining sales are concentrated in markets with delayed generic substitution, residual brand loyalty, reimbursement differences, or local distribution arrangements.
AstraZeneca's current revenue exposure to rosuvastatin is small relative to its oncology, respiratory, cardiovascular-renal-metabolic, and rare-disease portfolios. For generic manufacturers, the exposure is different: rosuvastatin can contribute meaningful volume but usually has limited margin because of intense competition.
How strong is the rosuvastatin patent estate?
The patent estate is weak for conventional rosuvastatin tablets and stronger only in narrow, product-specific areas.
| Estate component | Strength | Commercial assessment |
|---|---|---|
| Core rosuvastatin molecule | Low | No broad current barrier in major markets |
| Rosuvastatin calcium tablet | Low to moderate | Routine generics widely available |
| Combination products | Moderate | Depends on claim scope and jurisdiction |
| Modified release | Moderate | Limited market unless clinically differentiated |
| Manufacturing processes | Moderate | Relevant to supplier freedom to operate |
| Method of use | Low | Routine cardiovascular indications are difficult to block |
| Emerging-market rights | Variable | Local patents and registration rules differ |
Geographic coverage remains uneven. Patent expiry, generic approval, compulsory licensing rules, price regulation, and procurement practices can create different market conditions in the United States, Europe, China, India, Latin America, and Africa.
Investment and commercial outlook for rosuvastatin
Rosuvastatin is a stable, low-growth generic category rather than a high-margin branded opportunity. The strongest commercial strategies are:
- Secure low-cost, compliant API supply.
- Maintain multiple manufacturing sites or qualified suppliers.
- Compete in high-volume US and European tenders selectively.
- Build distribution in China, India, Latin America, and other expanding markets.
- Develop rosuvastatin-ezetimibe combinations.
- Use packaging, adherence, and dose differentiation where reimbursement supports it.
- Avoid overreliance on a single buyer or pharmacy channel.
A plain rosuvastatin tablet launch can produce volume but is unlikely to support sustained premium pricing. Combination products and differentiated dosage forms offer better economics, although they carry higher regulatory, clinical, and patent-screening requirements.
Key Takeaways
- Global rosuvastatin sales are estimated at about $3.0 billion in 2024.
- The base-case forecast is approximately $3.4 billion by 2029.
- Unit demand should grow faster than revenue because generic price erosion is persistent.
- Crestor's US generic market opened in 2016 after patent disputes and settlement-related restrictions.
- The core rosuvastatin patent estate is largely exhausted in major markets.
- Conventional rosuvastatin tablets have limited current patent protection.
- Rosuvastatin-ezetimibe combinations offer the clearest product-level growth opportunity.
- Biosimilar risk is irrelevant because rosuvastatin is a small-molecule drug.
- China, India, Latin America, and other emerging markets provide the strongest volume-growth potential.
- Generic manufacturers face supply, compliance, tender, and pricing risks rather than core molecule patent risk.
FAQs
How much did Crestor sales decline after generic rosuvastatin entry?
Crestor sales declined sharply after US generic entry in 2016. The product moved from a major branded revenue contributor to a much smaller residual brand, with generic substitution and price compression driving the change.
Is rosuvastatin still commercially attractive for generic manufacturers?
Yes, primarily as a scale product. Commercial attractiveness depends on API cost, manufacturing utilization, tender access, supply reliability, and the ability to sell combinations or differentiated presentations.
Does rosuvastatin have pediatric exclusivity?
Crestor received pediatric-related regulatory protection in the United States, but that period has expired. It does not create a current barrier to ordinary generic rosuvastatin entry.
Are rosuvastatin-ezetimibe products more valuable than rosuvastatin alone?
They can be. Combination products may improve adherence and provide a higher revenue per prescription, but they face separate regulatory, patent, reimbursement, and generic-substitution risks.
What is the largest long-term threat to rosuvastatin demand?
The largest threat is therapeutic substitution in high-risk patients by PCSK9 inhibitors, bempedoic acid, inclisiran, or other non-statin therapies. The effect is likely to remain limited in broad primary prevention because statins retain a major cost and evidence advantage.
References
-
AstraZeneca. (2016). Annual report and Form 20-F 2015. AstraZeneca PLC.
-
AstraZeneca. (2024). Annual report and Form 20-F 2023. AstraZeneca PLC.
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2023). ANDA approvals and generic drug program information. https://www.fda.gov/drugs/abbreviated-new-drug-application-anda
-
U.S. Patent and Trademark Office. (2001). U.S. Patent No. 6,316,023: N-substituted pyrimidine derivatives. U.S. Department of Commerce.
-
Grundy, S. M., Stone, N. J., Bailey, A. L., et al. (2019). 2018 AHA/ACC/AACVPR/AAPA/ABC/ACPM/ADA/AGS/APhA/ASPC/NLA/PCNA guideline on the management of blood cholesterol. Circulation, 139(25), e1082-e1143.
-
U.S. Food and Drug Administration. (2024). Small business and industry assistance: Generic drugs and abbreviated new drug applications. https://www.fda.gov/drugs/development-approval-process-drugs】【。
More… ↓
