Share This Page
Drug Sales Trends for BYSTOLIC
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for BYSTOLIC (2016)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
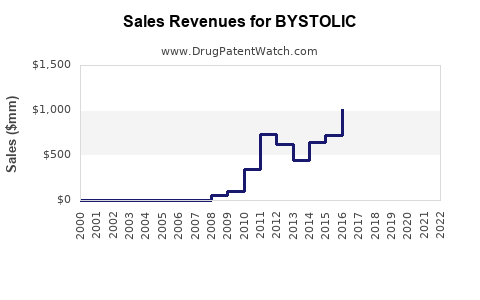
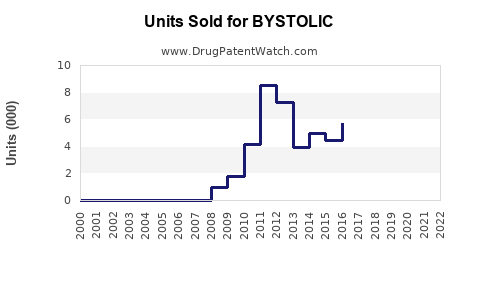
Annual Sales Revenues and Units Sold for BYSTOLIC
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| BYSTOLIC | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| BYSTOLIC | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| BYSTOLIC | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| BYSTOLIC | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Bystolic Market Analysis and Sales Projections: Nebivolol Revenue, Generic Competition, and Patent Risk
Bystolic, the branded form of nebivolol, is a mature U.S. hypertension product facing substantial generic erosion. The brand’s commercial value is concentrated in residual branded prescriptions, payer-protected patients, and non-U.S. markets where nebivolol remains differentiated. A reasonable U.S. forecast places branded Bystolic revenue in the low tens of millions of dollars annually through 2029, while total nebivolol-market revenue should remain materially higher because of generic volume.
The main investment issue is no longer loss of exclusivity. Generic entry has already occurred. The relevant questions are the pace of brand-to-generic substitution, the durability of the Bystolic brand, and whether any remaining patent or regulatory rights can delay additional competition.
What is Bystolic and how large is its addressable market?
Bystolic is an oral, once-daily beta-1 adrenergic blocker containing nebivolol hydrochloride. The U.S. Food and Drug Administration approved Bystolic in December 2007 for the treatment of hypertension in adults.[1]
| Attribute | Bystolic |
|---|---|
| Active ingredient | Nebivolol hydrochloride |
| Drug class | Beta-1 selective beta blocker |
| Dosage form | Immediate-release oral tablets |
| U.S. indication | Hypertension |
| Available strengths | 2.5 mg, 5 mg, 10 mg and 20 mg |
| Original U.S. sponsor | Forest Laboratories |
| Current commercial context | Mature brand with generic nebivolol competition |
| Primary competitors | Generic nebivolol, carvedilol, metoprolol, atenolol and bisoprolol |
| FDA pathway | NDA approval, followed by ANDA generic approvals |
Bystolic competes in a large hypertension market, but the relevant commercial segment is the beta-blocker market rather than the entire antihypertensive market. Beta blockers are used less frequently as first-line therapy for uncomplicated hypertension than ACE inhibitors, angiotensin receptor blockers, calcium-channel blockers and thiazide diuretics.
Nebivolol retains clinical and commercial differentiation through once-daily dosing, beta-1 selectivity and nitric-oxide-mediated vasodilatory activity described in its prescribing information.[1] Those characteristics support physician and patient preference but have limited ability to preserve premium pricing after generic entry.
How much revenue did Bystolic generate before generic competition?
Bystolic was a significant Forest Laboratories product before the loss of effective market exclusivity. Public company filings reported several hundred million dollars of annual product revenue during the period when Forest controlled the brand and generic competition was absent or limited.[2]
The product benefited from:
- A large diagnosed hypertension population.
- Once-daily dosing.
- Broad primary-care prescribing.
- Brand recognition among cardiologists and internists.
- Limited direct competition from branded beta blockers with a similar positioning.
Revenue peaked before generic nebivolol approvals and then declined as patent protection and commercial exclusivity weakened. The commercial trajectory was typical for a mature cardiovascular product: strong pre-generic revenue, followed by rapid prescription switching and price compression.
Historical commercial timeline
| Period | Commercial event | Revenue implication |
|---|---|---|
| 2007 | FDA approval of Bystolic | U.S. launch begins |
| 2008-2014 | Brand expansion in hypertension | Revenue grows into the hundreds of millions |
| 2015-2019 | Mature brand phase | Revenue stabilizes or declines gradually |
| 2020-2021 | Generic approvals and market entry | Rapid erosion begins |
| 2022 onward | Generic-dominated market | Brand revenue contracts sharply |
| 2025-2029 | Residual brand phase | Low, declining branded revenue |
Forest Laboratories was acquired by Actavis in 2014. Actavis later became part of Allergan, which AbbVie acquired in 2020.[3] The ownership changes did not alter the underlying issue: Bystolic had transitioned from a growth product to a mature, genericized asset.
What are the current Bystolic sales projections?
The following forecast is a market model rather than a company-reported forecast. It assumes U.S. branded Bystolic sales, excluding generic nebivolol revenue, and uses a 2024 base estimate of approximately $40 million to $70 million.
U.S. branded Bystolic forecast
| Year | Low case | Base case | High case |
|---|---|---|---|
| 2024 | $40 million | $55 million | $70 million |
| 2025 | $30 million | $42 million | $58 million |
| 2026 | $22 million | $32 million | $47 million |
| 2027 | $16 million | $24 million | $37 million |
| 2028 | $12 million | $18 million | $30 million |
| 2029 | $9 million | $14 million | $24 million |
The base case implies a compound annual decline of approximately 20% from 2024 through 2029. The decline could be faster if commercial payers remove Bystolic from preferred tiers or if generic manufacturers expand supply. It could be slower if AbbVie maintains brand loyalty among stable patients and preserves favorable formulary access.
Total nebivolol-market projection
Total nebivolol revenue should exceed Bystolic revenue because generic products serve most prescriptions at materially lower prices.
| Year | Estimated total U.S. nebivolol market |
|---|---|
| 2024 | $140 million-$210 million |
| 2025 | $135 million-$205 million |
| 2026 | $130 million-$200 million |
| 2027 | $125 million-$195 million |
| 2028 | $120 million-$190 million |
| 2029 | $115 million-$185 million |
The generic market can remain relatively stable in prescription volume while revenue declines because of annual price reductions. Total market value depends on prescription volume, generic pricing, wholesaler discounts and the number of active manufacturers.
When did Bystolic lose exclusivity?
Bystolic lost effective commercial exclusivity when generic nebivolol products entered the U.S. market. FDA-approved ANDA products are now available from multiple manufacturers, including large generic suppliers and authorized or secondary-label distributors.[4]
The practical loss-of-exclusivity date is more important than the nominal expiration date of any individual patent. Once multiple ANDA products were approved and launched, Bystolic faced:
- Generic substitution at the pharmacy.
- Lower reimbursement from commercial payers.
- Reduced physician incentive to initiate new patients on the brand.
- Contracting pressure from wholesalers and pharmacy benefit managers.
- Declining average selling price.
The remaining brand opportunity is therefore a residual-prescription business rather than a protected growth franchise.
What patents protect Bystolic?
Bystolic was protected by composition, formulation and related patent rights associated with nebivolol and its pharmaceutical use. The relevant U.S. patent landscape included patents listed in the FDA Orange Book for the Bystolic NDA, as well as patents held by originator or licensed entities outside the Orange Book system.[5]
The most commercially important protection covered the active pharmaceutical ingredient and the approved product. Secondary patents can cover:
- Tablet composition.
- Excipients and manufacturing processes.
- Specific dosage forms.
- Salt or crystalline forms.
- Treatment of hypertension.
- Patient populations or dosing regimens.
The existence of a listed patent does not guarantee a period without generic competition. ANDA applicants can file Paragraph IV certifications alleging that a listed patent is invalid, unenforceable or not infringed under the Hatch-Waxman Act.[6]
How strong is the Bystolic patent estate?
The patent estate is commercially weak after generic entry. A patent portfolio can remain legally active while losing practical market power if:
- Generic products have already launched.
- Core patents have expired or been successfully challenged.
- Remaining patents cover narrow methods of use.
- The brand has no enforceable settlement-based launch restriction.
- Generic substitution is permitted under state pharmacy laws.
The most relevant residual risks concern formulation patents, manufacturing patents and any unexpired method-of-use claims. Those rights are unlikely to restore the former branded revenue base unless they cover the commercially dominant product and can be enforced against the active generic market.
What is the Orange Book status of Bystolic?
Bystolic is listed in the FDA Orange Book under NDA 021742.[5] The Orange Book identifies patents and regulatory exclusivity information submitted for approved drug products. For Bystolic, the commercial significance of the listing is limited because generic nebivolol products have received FDA approval.
Orange Book status should be evaluated at the product and patent level:
| Issue | Commercial assessment |
|---|---|
| NDA listing | Confirms FDA-approved reference product |
| Listed patents | Relevant to ANDA certification and litigation |
| Regulatory exclusivity | No meaningful new-product exclusivity expected |
| Generic approvals | Established |
| Brand substitution risk | High |
| Remaining patent leverage | Narrow and declining |
A listed patent can still generate litigation risk, but it does not create a realistic basis for forecasting a return to pre-generic Bystolic sales.
Which companies are challenging Bystolic?
Generic nebivolol competition has come through ANDA applicants and commercial generic manufacturers. The U.S. market typically includes products from companies such as:
- Teva Pharmaceuticals.
- Mylan, now part of Viatris.
- Lupin.
- Dr. Reddy’s Laboratories.
- Zydus.
- Torrent Pharmaceuticals.
- Other approved ANDA holders and contract manufacturers.
The exact active supplier group changes because generic companies enter and exit based on price, manufacturing economics and supply contracts. The market is vulnerable to price compression when several suppliers compete, but it can experience temporary price increases if manufacturing disruptions reduce available supply.
What patent litigation and Paragraph IV risks affect Bystolic?
Bystolic’s principal litigation risk arose during the period before and around generic entry, when ANDA applicants challenged listed patents under Paragraph IV. The typical litigation questions were whether the asserted patents were valid, infringed and enforceable.
For current commercial forecasting, litigation risk is secondary to supply and reimbursement risk. A new patent case would have material value only if it could:
- Remove a generic competitor from the market.
- Restrict substitution.
- Recover meaningful damages.
- Cover the commercial formulation rather than a narrow use.
- Produce an enforceable injunction or settlement restriction.
No assumption of renewed Bystolic exclusivity should be included in a base-case forecast without a new enforceable court order or regulatory event.
Does Bystolic face biosimilar risk?
No. Bystolic is a small-molecule drug, not a biologic. It is exposed to ordinary generic competition through the ANDA pathway, not biosimilar competition under the Public Health Service Act.
This distinction matters because generic approval is generally less complex and less costly than biosimilar development. Multiple manufacturers can therefore compete on price once the core patents and regulatory barriers no longer prevent entry.
What formulations and methods of use are protected?
The commercial product is an immediate-release tablet taken once daily for hypertension. Potential secondary protection may cover tablet composition, manufacturing processes or particular therapeutic uses. Those protections have limited value if physicians and pharmacists can substitute generic nebivolol tablets with the same active ingredient and dosage strengths.
Bystolic does not have a major protected extended-release platform comparable to certain long-acting cardiovascular products. Its commercial defense is primarily brand persistence, not a differentiated delivery system.
How does Bystolic compare with competing beta blockers?
| Product | Active ingredient | Generic status | Commercial position |
|---|---|---|---|
| Bystolic | Nebivolol | Generic competition established | Residual premium brand |
| Toprol-XL | Metoprolol succinate | Generic | Large established generic market |
| Coreg CR | Carvedilol phosphate | Generic competition | Controlled-release formulation |
| Lopressor | Metoprolol tartrate | Generic | Low-cost, high-volume option |
| Tenormin | Atenolol | Generic | Mature low-price product |
| Zebeta | Bisoprolol | Generic | Niche beta-blocker market |
Nebivolol can command a higher price than older beta blockers in selected channels, but generic substitution limits the premium. The main competitive advantage is tolerability and physician familiarity rather than patent exclusivity.
What generic launch scenarios exist for Bystolic?
Base case
Generic nebivolol maintains dominant prescription share. Bystolic revenue falls approximately 15% to 25% annually, reaching about $14 million by 2029 in the central forecast.
Downside case
Payers intensify mandatory generic substitution, generic supply remains reliable, and the brand loses preferred formulary status. Revenue falls below $10 million by 2029.
Upside case
Generic shortages, brand contracting and persistent physician preference slow substitution. Revenue remains near $25 million to $30 million in 2029. This scenario does not restore Bystolic to its former peak.
What is Bystolic’s revenue exposure and investment value?
Bystolic is unlikely to be a material growth driver for its current owner. The asset may retain value through cash generation, established manufacturing, international rights and limited residual brand demand. Its risk profile is defined by erosion rather than regulatory failure.
The most important revenue variables are:
- Brand prescription retention.
- Net price after rebates.
- Generic supply reliability.
- Formulary placement.
- International patent and reimbursement status.
- Manufacturing cost and transfer-pricing structure.
Licensing value is limited unless a buyer acquires a broader cardiovascular portfolio, international rights or manufacturing capabilities. A standalone Bystolic transaction would likely be valued on declining cash flow, not on future exclusivity.
Key Takeaways
- Bystolic is the branded nebivolol product approved by the FDA in 2007 for hypertension.
- Generic nebivolol competition has already eliminated effective U.S. market exclusivity.
- Estimated U.S. branded revenue is approximately $40 million to $70 million for 2024.
- Base-case branded revenue declines to about $14 million by 2029.
- Total nebivolol-market revenue should remain substantially larger than Bystolic revenue.
- Bystolic has no biosimilar risk because it is a small-molecule drug.
- Remaining patent rights may create litigation exposure but are unlikely to restore branded pricing power.
- The principal commercial risks are generic substitution, formulary restrictions and price erosion.
FAQs
Is Bystolic still protected by patents?
Some patent rights may remain listed or otherwise associated with the product, but generic nebivolol competition means the core commercial exclusivity has already been lost.
Is nebivolol a profitable generic drug?
Nebivolol can remain commercially viable because hypertension produces recurring prescription demand. Profitability depends on manufacturing cost, supplier concentration and generic pricing.
Can Bystolic be relaunched as an extended-release product?
A new formulation would require separate development, regulatory review and potentially new patent protection. The existing immediate-release Bystolic franchise does not provide automatic protection for a new delivery system.
Who owns Bystolic?
Bystolic became part of the Allergan portfolio and subsequently AbbVie’s portfolio following AbbVie’s acquisition of Allergan in 2020.[3]
What is the largest threat to Bystolic sales?
Generic substitution is the largest threat. Payer restrictions and lower generic prices will continue to reduce branded prescriptions and net revenue.
References
- U.S. Food and Drug Administration. (2007). Bystolic (nebivolol hydrochloride) prescribing information.
- Forest Laboratories, Inc. (2014). Annual report for fiscal year ended March 31, 2014.
- AbbVie Inc. (2020). Annual report for the year ended December 31, 2020.
- U.S. Food and Drug Administration. (n.d.). Drugs@FDA: Bystolic and approved generic nebivolol products.
- U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Congress. (1984). Drug Price Competition and Patent Term Restoration Act of 1984, 21 U.S.C. § 355(j).
More… ↓
