Share This Page
Drug Sales Trends for ANASTROZOLE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ANASTROZOLE (2016)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
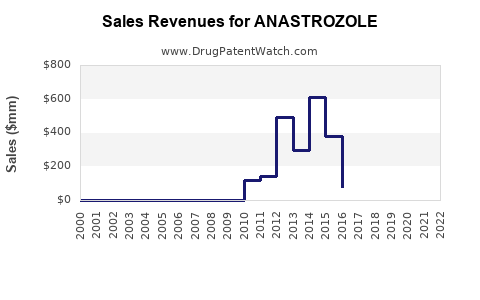
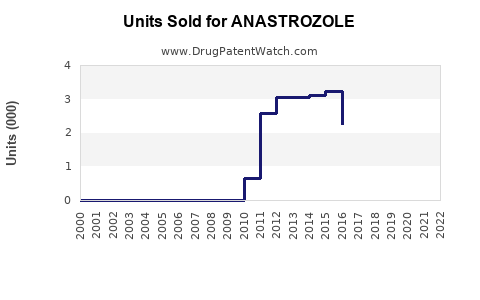
Annual Sales Revenues and Units Sold for ANASTROZOLE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ANASTROZOLE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ANASTROZOLE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ANASTROZOLE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Anastrozole Market Analysis, Sales Projections, Patent Expiration, and Generic Competition
Anastrozole is a mature, multisource aromatase inhibitor with limited branded revenue and low regulatory barriers to generic supply. AstraZeneca’s Arimidex franchise lost practical U.S. exclusivity in 2010 after the active-ingredient patent term ended and generic anastrozole entered the market. Future growth is likely to come from prescription volume, broader access in lower-income markets, and oncology guideline adoption rather than pricing power.
A reasonable base-case estimate places the global anastrozole product market in the low hundreds of millions of dollars annually, with nominal value remaining broadly flat or declining through 2030. Volume should remain more resilient than revenue because generic prices continue to fall.
What is anastrozole used for?
Anastrozole is an oral, nonsteroidal aromatase inhibitor that reduces peripheral estrogen production. It is primarily used in postmenopausal women with hormone receptor-positive breast cancer.
The FDA-approved Arimidex label covers:
- Adjuvant treatment of postmenopausal women with early breast cancer.
- First-line treatment of postmenopausal women with locally advanced or metastatic breast cancer.
- Treatment of advanced breast cancer after progression on tamoxifen.
Anastrozole is generally administered at 1 mg once daily. The drug is also used in clinical practice for extended adjuvant endocrine therapy and, in selected settings, for fertility-related indications outside its original oncology label. Those uses can expand prescription volume but do not materially improve pricing because they rely on generic tablets.
The National Cancer Institute identifies aromatase inhibitors, including anastrozole, letrozole, and exemestane, as standard endocrine-treatment options for hormone receptor-positive breast cancer in postmenopausal patients.[1]
How large is the anastrozole market?
No single public source reports a complete global market total for anastrozole across branded products, hospital procurement, retail generics, and international distributors. A bottom-up commercial model is more useful than relying on inconsistent market-research estimates.
Estimated global market, 2024-2030
| Scenario | 2024 estimated product sales | 2030 estimated product sales | 2024-2030 CAGR | Main assumptions |
|---|---|---|---|---|
| Downside | $150 million | $110 million | -5% | Continued price erosion, substitution by letrozole or exemestane, low-cost tenders |
| Base case | $250 million | $220 million | -2% | Stable patient pool, modest volume growth, continued generic price compression |
| Upside | $400 million | $430 million | 1% | Higher diagnosis rates, expanded access, stronger use in extended endocrine therapy |
These figures are analytical estimates rather than audited industry sales. They exclude hospital services, oncology administration, diagnostic testing, and the broader aromatase-inhibitor market.
The market’s economics are shaped by three factors:
- Anastrozole is an oral solid dosage product with relatively low manufacturing complexity.
- Multiple generic suppliers compete on price.
- Long treatment duration supports recurring volume but also accelerates payer pressure.
A typical adjuvant treatment course can last five years, with extended endocrine therapy used for selected patients. That duration supports recurring prescriptions even after patent expiry. The commercial value per patient, however, is low compared with newer oncology products.
What were Arimidex sales before generic entry?
Arimidex was one of AstraZeneca’s major oncology products before generic competition. Its commercial peak occurred before the 2010 generic entry period, when the product benefited from:
- A strong position in postmenopausal hormone receptor-positive breast cancer.
- Use in adjuvant and metastatic disease.
- Long treatment duration.
- Limited direct substitution from generic aromatase inhibitors during the branded period.
AstraZeneca reported Arimidex sales of approximately $1 billion annually near the end of its branded life, although reported revenue varied by year, currency, geography, and the timing of generic competition.[2]
That historical revenue is not a suitable proxy for the current anastrozole market. Branded revenue reflected patent protection and premium pricing. Current sales are distributed among generic manufacturers, wholesalers, pharmacies, hospitals, and public procurement systems.
When did anastrozole lose exclusivity?
Anastrozole lost effective U.S. market exclusivity around 2010.
| Milestone | Date or period | Commercial significance |
|---|---|---|
| Original U.S. patent filing | Late 1980s | Established protection for the anastrozole compound |
| FDA approval of Arimidex | December 27, 1995 | Arimidex entered the U.S. prescription market |
| U.S. active-ingredient patent term | Approximately 2009, subject to statutory adjustments | Core compound protection ended |
| Pediatric or regulatory term adjustments | Around 2010 | Extended the practical exclusivity period |
| Generic entry | 2010 | Multisource competition materially reduced prices |
| Current market | Generic-dominated | Limited brand-level pricing power |
The FDA approved Arimidex under NDA 020541. The principal compound patent associated with anastrozole was U.S. Patent No. 4,935,437, assigned to Zeneca-related entities. The patent’s effective commercial life ended before the current market period, and it does not create a present barrier to routine generic development.[3]
What is the Orange Book status of anastrozole?
Anastrozole has no meaningful current Orange Book barrier comparable to a protected, single-source oncology product.
The FDA Orange Book historically identified Arimidex and related regulatory information. After generic approval, the market shifted to ANDA-based products carrying the same active ingredient, strength, dosage form, and route of administration.[4]
Orange Book and regulatory implications
| Issue | Anastrozole status |
|---|---|
| Reference listed drug | Arimidex |
| NDA holder | AstraZeneca |
| Dosage form | Oral tablet |
| Common strength | 1 mg |
| Generic pathway | ANDA, generally with a Paragraph IV or Paragraph III certification depending on patent status at filing |
| Current compound patent barrier | None of practical importance |
| REMS requirement | No major product-specific REMS barrier |
| Controlled-substance restrictions | None |
| Biosimilar pathway | Not applicable |
The principal regulatory risks are routine quality, manufacturing, bioequivalence, and supply-chain issues rather than Orange Book patent disputes.
Which companies compete in anastrozole?
Competition is fragmented and primarily generic. Supplier participation varies by country, procurement contract, and product discontinuation status.
Potential or historical suppliers include:
- Teva Pharmaceuticals
- Sandoz
- Dr. Reddy’s Laboratories
- Cipla
- Accord Healthcare
- Mylan, now part of Viatris
- Sun Pharmaceutical Industries
- Zydus Pharmaceuticals
- Aurobindo Pharma
- Lupin
- Apotex
- Hikma Pharmaceuticals
The relevant competitive distinction is usually not molecule ownership. It is manufacturing reliability, regulatory history, channel access, and the ability to maintain acceptable gross margins at low prices.
Competitive comparison with letrozole and exemestane
| Product | Drug class | Generic status | Competitive position |
|---|---|---|---|
| Anastrozole | Nonsteroidal aromatase inhibitor | Mature generic | Strong access and broad familiarity |
| Letrozole | Nonsteroidal aromatase inhibitor | Mature generic | Closest therapeutic substitute |
| Exemestane | Steroidal aromatase inhibitor | Generic | Alternative after nonsteroidal AI use or intolerance |
| Tamoxifen | Selective estrogen receptor modulator | Mature generic | Alternative endocrine therapy with different risk profile |
Letrozole is the most direct competitor because it is also a once-daily nonsteroidal aromatase inhibitor used in postmenopausal hormone receptor-positive breast cancer. Treatment choice depends on guideline preference, prior therapy, tolerability, bone health, recurrence risk, formulary placement, and physician practice.
What generic entry risks exist for anastrozole?
The generic-entry risk is no longer an event risk. It is an ongoing price and share risk.
Price erosion
In a mature oral generic market, additional entrants generally reduce average selling prices. The first generic suppliers can retain stronger margins, but later entrants often compete through:
- Pharmacy benefit manager contracts.
- Wholesaler discounts.
- Government tenders.
- Hospital purchasing agreements.
- Private-label supply.
- International distributor pricing.
Substitution risk
Anastrozole may lose volume to letrozole or exemestane where formularies favor those products. Switching is constrained by physician preference and patient tolerability, but all three products compete within the same endocrine-treatment category.
Supply risk
Shortages or manufacturing interruptions can create temporary opportunities for remaining suppliers. Those gains are usually volume-driven and may reverse when supply normalizes.
Clinical-position risk
Newer adjuvant therapies, including targeted treatments for selected high-risk breast cancer populations, can change the treatment mix. These products usually supplement rather than eliminate aromatase inhibitors, because endocrine therapy remains a backbone for hormone receptor-positive disease.
Are there formulation patents protecting anastrozole?
Anastrozole does not have a commercially significant formulation-patent moat in the standard 1 mg tablet market.
The product is chemically simple and does not depend on:
- A complex controlled-release system.
- A device-based delivery platform.
- A biologic manufacturing process.
- A specialized injectable formulation.
- A proprietary tablet technology required for clinical performance.
Generic manufacturers can generally use conventional oral-tablet manufacturing, subject to FDA chemistry, manufacturing, and controls requirements and bioequivalence testing.
Potentially relevant intellectual-property areas include:
- Tablet excipient composition.
- Crystalline or polymorphic forms.
- Manufacturing processes.
- Packaging and stability.
- Combination therapies.
- Patient-selection or dosing methods.
These rights do not appear to create a broad commercial barrier to standard generic anastrozole. Any remaining country-specific formulation or process patent would need separate jurisdictional review and would not automatically prevent U.S. or European generic sales.
What method-of-use patents affect anastrozole?
Method-of-use protection was more important during the branded period than it is today.
Arimidex was marketed for adjuvant, first-line metastatic, and post-tamoxifen treatment. Those uses were supported by clinical-trial data and labeling, but the relevant exclusivity period has ended in major markets.
Current method-of-use risks are limited because:
- The principal oncology indications are established and widely genericized.
- Physicians can prescribe generics under the same approved label.
- Many clinical uses are governed by treatment guidelines rather than enforceable product exclusivity.
- A new method patent would need to claim a sufficiently distinct patient population, regimen, biomarker, or combination.
A method patent could still affect a narrow combination or high-risk patient segment, but it would not normally protect the full anastrozole market.
Has anastrozole faced Paragraph IV litigation?
Anastrozole faced the standard patent-certification issues associated with generic entry. Generic applicants seeking approval before all listed patent protections expired could file Paragraph IV certifications and challenge patent validity, enforceability, or infringement.
The commercial result was generic availability around 2010. That outcome confirms that no enforceable patent estate prevented broad generic entry.
The major litigation exposure today is therefore limited. Potential disputes could involve:
- A supplier’s manufacturing process.
- A polymorph or crystalline form.
- A narrow method of treatment.
- ANDA product quality or approval issues.
- Contract disputes between manufacturers and distributors.
A new Paragraph IV wave against the original compound patent is no longer a realistic market scenario because the foundational protection has expired.
What is the FDA regulatory status of anastrozole?
Anastrozole is an FDA-approved prescription drug sold through the NDA and ANDA systems.
The regulatory profile is favorable for generic competition:
| Regulatory factor | Assessment |
|---|---|
| FDA-approved reference product | Yes |
| Generic ANDA pathway | Established |
| Bioequivalence complexity | Low to moderate |
| Clinical endpoint requirement for standard ANDA | Generally not required |
| REMS burden | Low |
| Pediatric exclusivity relevance | Historical |
| Manufacturing complexity | Low relative to biologics and sterile injectables |
| Post-market safety monitoring | Routine pharmacovigilance |
Key safety considerations include bone mineral density loss, musculoskeletal symptoms, cardiovascular events in appropriate risk groups, and menopausal symptoms. These risks affect prescribing and adherence but do not create a significant regulatory barrier to generic supply.[5]
What are the anastrozole sales projections through 2030?
The base case assumes global product sales of approximately $250 million in 2024, declining to about $220 million by 2030.
| Year | Downside | Base case | Upside |
|---|---|---|---|
| 2024 | $150 million | $250 million | $400 million |
| 2025 | $143 million | $245 million | $404 million |
| 2026 | $136 million | $240 million | $408 million |
| 2027 | $129 million | $235 million | $412 million |
| 2028 | $123 million | $230 million | $416 million |
| 2029 | $116 million | $225 million | $420 million |
| 2030 | $110 million | $220 million | $430 million |
The model assumes product sales, not patient spending or total breast-cancer-treatment revenue.
Revenue drivers through 2030
Positive drivers include:
- Higher breast-cancer diagnosis rates.
- Longer survival and extended endocrine therapy.
- Expanded access in emerging markets.
- Increased use of low-cost oral oncology treatments.
- Intermittent shortages affecting supplier share.
Negative drivers include:
- Continued generic price erosion.
- Substitution by letrozole or exemestane.
- Treatment discontinuation caused by musculoskeletal adverse effects.
- Reduced use in lower-risk populations.
- Procurement concentration among large buyers.
- Newer targeted therapies affecting treatment mix in selected patients.
The base case assigns greater confidence to volume stability than to revenue stability. Prescription units may remain flat or rise modestly while sales decline because price reductions exceed volume growth.
How strong is the anastrozole patent estate?
The patent estate is weak for commercial defense and strong only as a historical record.
| Patent-estate dimension | Assessment |
|---|---|
| Core compound patent | Expired |
| Brand exclusivity | Expired |
| Standard tablet formulation | Low protection |
| Broad oncology indications | No meaningful remaining exclusivity |
| Manufacturing patents | Potentially narrow and supplier-specific |
| Combination or biomarker methods | Possible narrow rights |
| Biosimilar protection | Not applicable |
| Generic blocking risk | Low |
Anastrozole is therefore attractive for volume-oriented generic manufacturers with efficient production and reliable distribution. It is unattractive as a premium-priced branded product unless paired with a differentiated delivery system, combination product, or clinically meaningful new indication.
What licensing deals affect anastrozole?
No major active licensing deal is required to commercialize standard generic anastrozole in the United States. The original Arimidex rights were associated with AstraZeneca and its predecessor organizations. Current generic suppliers typically rely on their own ANDA approvals, manufacturing networks, and distribution arrangements.
Commercial agreements may still exist at the country or channel level, including:
- Contract manufacturing.
- Regional distribution.
- Government-tender supply.
- Private-label pharmacy supply.
- API procurement agreements.
These arrangements are operational rather than strategic exclusivity transactions. They do not materially change the overall competitive structure.
What geographic markets offer the strongest opportunity?
The United States and Western Europe are mature, low-price markets. Growth potential is greater in countries where breast-cancer diagnosis is increasing but access to endocrine therapy remains uneven.
| Region | Market profile | Commercial opportunity |
|---|---|---|
| United States | Mature generic market, strong payer control | Volume stability, low margins |
| Western Europe | Mature and tender-driven | Reliable demand, price pressure |
| Central and Eastern Europe | Generic access varies by country | Moderate volume opportunity |
| China | Large patient population, competitive local supply | Significant volume, pricing and registration pressure |
| India | Large generic manufacturing base | Strong supply competition, export potential |
| Latin America | Uneven reimbursement and procurement | Country-specific opportunities |
| Middle East and Africa | Access constrained in some markets | Long-term volume growth, tender dependence |
Geographic expansion is more likely to increase units than global revenue. Local registration, pharmacopoeia requirements, pricing controls, and government tenders determine profitability.
Key Takeaways
- Anastrozole is a mature generic aromatase inhibitor with limited current patent risk.
- Arimidex received FDA approval in 1995 and lost practical U.S. exclusivity around 2010.
- The foundational anastrozole patent estate does not provide a present barrier to standard generic entry.
- The current global product market is reasonably modeled in the low hundreds of millions of dollars annually.
- Base-case sales are projected to decline modestly from approximately $250 million in 2024 to $220 million in 2030.
- Volume should be more stable than revenue because generic pricing remains under pressure.
- Letrozole and exemestane are the principal therapeutic competitors.
- Biosimilar risk is irrelevant because anastrozole is a small-molecule oral drug.
- Commercial success depends on cost, manufacturing reliability, tender access, and geographic coverage.
- New value would require a differentiated formulation, combination product, or narrowly protected clinical use.
FAQs
Is anastrozole still profitable for generic manufacturers?
Yes, but profitability depends on manufacturing cost, market share, tender access, and supply reliability. It is generally a volume product rather than a high-margin product.
Can a company launch a new branded anastrozole product?
Yes, but a standard 1 mg tablet would face immediate generic substitution. A viable branded strategy would require a differentiated formulation, combination, delivery system, or protected indication.
Is anastrozole more commercially attractive than letrozole?
Anastrozole has strong clinical familiarity and broad generic availability. Letrozole may have greater demand in some markets and indications. Relative attractiveness depends on local pricing, formulary position, and supplier concentration.
Does anastrozole require a biosimilar application?
No. Anastrozole is a chemically synthesized small molecule. A conventional ANDA or equivalent national generic pathway is used, subject to jurisdiction-specific requirements.
What is the main investment risk in the anastrozole market?
The main risk is price compression. Demand is relatively durable, but additional generic suppliers, payer tenders, and substitution by other endocrine therapies can reduce revenue per prescription.
References
-
National Cancer Institute. (n.d.). Breast cancer treatment. U.S. National Institutes of Health. https://www.cancer.gov/types/breast/patient/breast-treatment-pdq
-
AstraZeneca PLC. (2010). Annual report and form 20-F 2010. AstraZeneca.
-
U.S. Patent and Trademark Office. (1989). U.S. Patent No. 4,935,437: Triazole derivatives. U.S. Department of Commerce.
-
U.S. Food and Drug Administration. (n.d.). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (2011). Arimidex (anastrozole) prescribing information. AstraZeneca Pharmaceuticals LP. https://www.accessdata.fda.gov/drugsatfda_docs/label/2011/020541s026lbl.pdf
More… ↓
