Share This Page
Drug Sales Trends for capsaicin
✉ Email this page to a colleague
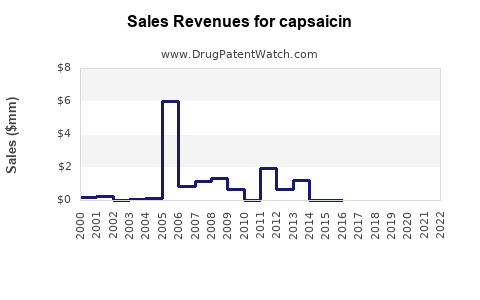
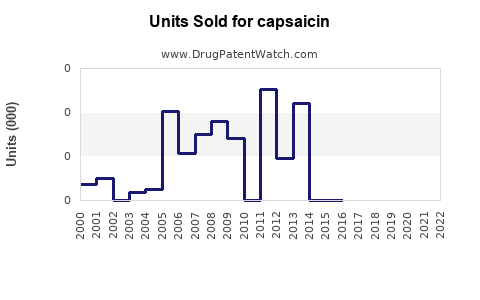
Annual Sales Revenues and Units Sold for capsaicin
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| CAPSAICIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| CAPSAICIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| CAPSAICIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Capsaicin Drug Market Analysis, Sales Projections, Patents, and Competitive Landscape
Capsaicin is a mature, fragmented topical analgesic market rather than a single branded pharmaceutical category. Most revenue comes from low-cost over-the-counter creams, gels, patches, and roll-ons. The highest-value prescription product is Qutenza, an 8% capsaicin topical system used for neuropathic pain.
The commercial outlook is positive but moderate. A base-case model places global finished-product capsaicin sales at approximately $1.0 billion in 2024, rising to $1.3 billion-$1.5 billion by 2029. Prescription high-concentration products should grow faster than traditional low-dose OTC products, but they will remain a smaller part of total category revenue.
Qutenza has the strongest pharmaceutical positioning because it combines high capsaicin concentration with clinician administration and a defined neuropathic-pain indication. Its main commercial constraints are reimbursement, clinic capacity, treatment discomfort, competing neuropathic-pain drugs, and limited differentiation from inexpensive topical products in some pain categories.
What is the current capsaicin drug market size?
Public market research generally estimates the global capsaicin market, including finished products and some ingredient applications, in the high hundreds of millions to more than $1 billion annually. The narrower market for finished topical analgesic products is best modeled at approximately $0.8 billion-$1.2 billion in 2024.
The range is wide because market reports often combine:
- OTC topical analgesics
- Prescription high-concentration capsaicin systems
- Food and flavoring applications
- Pharmaceutical-grade active pharmaceutical ingredient sales
- Veterinary and animal-health products
- Sports recovery and wellness products
A practical pharmaceutical market segmentation is shown below.
| Segment | Estimated 2024 global sales | 2024-2029 outlook | Commercial profile |
|---|---|---|---|
| OTC creams, gels and ointments | $450 million-$650 million | 3%-5% CAGR | Largest segment; price-sensitive and fragmented |
| OTC patches and roll-ons | $250 million-$400 million | 4%-7% CAGR | Strong retail and e-commerce distribution |
| Prescription high-concentration systems | $100 million-$180 million | 7%-11% CAGR | Led by Qutenza and regional equivalents |
| API and compounded products | $50 million-$100 million | 3%-6% CAGR | Supplier and pharmacy-driven |
| Total finished-product pharmaceutical market | $0.8 billion-$1.2 billion | 5%-7% CAGR | Base market used for projection |
The estimates exclude most food, flavor, and agricultural uses of capsaicin. Public market research reports use broader definitions and may report materially higher totals.[1]
What are the main capsaicin products and indications?
Capsaicin is a transient receptor potential vanilloid 1, or TRPV1, agonist. Repeated topical exposure desensitizes nociceptive nerve endings and reduces local pain signaling.
OTC capsaicin products
OTC products generally contain 0.025%, 0.075%, or 0.1% capsaicin. Common indications include temporary relief of minor aches and pains associated with:
- Arthritis
- Simple backache
- Strains and sprains
- Bruises
- Muscle soreness
- Peripheral neuropathy symptoms
The U.S. Food and Drug Administration permits topical analgesic products under the external analgesic monograph, subject to applicable concentration, labeling, and safety requirements.[2]
OTC products compete primarily on retail distribution, brand recognition, price, application format, and consumer tolerability. Major commercial brands include capsaicin products sold under the Capzasin, Zostrix, Salonpas, and private-label categories, although product ownership and availability vary by country.
Prescription high-concentration capsaicin systems
Qutenza is an 8% capsaicin topical system. In the United States, Qutenza is approved for neuropathic pain associated with postherpetic neuralgia and, following a supplemental approval, neuropathic pain associated with diabetic peripheral neuropathy of the feet.[3]
The treatment is applied by a healthcare professional. Its commercial value is higher than that of OTC capsaicin because the product is positioned as a procedure-linked prescription treatment rather than as a mass-market topical analgesic.
| Product type | Typical capsaicin concentration | Primary channel | Main use |
|---|---|---|---|
| OTC cream or gel | 0.025%-0.1% | Retail, pharmacy, online | Musculoskeletal and neuropathic pain |
| OTC patch | Usually low-dose | Retail and online | Localized muscle and joint pain |
| Qutenza | 8% | Specialty clinic and physician office | Peripheral neuropathic pain |
| Compounded topical preparations | Variable | Compounding pharmacy | Customized pain management |
How much could capsaicin sales reach by 2029?
The following projection covers global finished pharmaceutical and topical analgesic products. It excludes food and industrial applications.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $0.8 billion | $1.0 billion | $1.2 billion |
| 2025 | $0.83 billion | $1.06 billion | $1.28 billion |
| 2026 | $0.86 billion | $1.12 billion | $1.37 billion |
| 2027 | $0.89 billion | $1.19 billion | $1.47 billion |
| 2028 | $0.92 billion | $1.26 billion | $1.57 billion |
| 2029 | $0.96 billion | $1.34 billion | $1.68 billion |
| 2024-2029 CAGR | 3.7% | 6.0% | 7.0% |
The base case assumes continued growth in chronic pain prevalence, wider use of non-opioid treatments, stable OTC demand, and moderate expansion of high-concentration prescription systems. The bull case requires broader reimbursement and more routine use of clinic-administered capsaicin in diabetic peripheral neuropathy.
Prescription capsaicin sales projection
Reported Qutenza revenue is not separately disclosed in the public financial reporting of all relevant commercial entities. A model-based estimate is more defensible than presenting an unverified reported figure.
| Year | Prescription high-concentration capsaicin market |
|---|---|
| 2024 | $100 million-$180 million |
| 2025 | $108 million-$198 million |
| 2026 | $117 million-$218 million |
| 2027 | $126 million-$240 million |
| 2028 | $136 million-$264 million |
| 2029 | $147 million-$290 million |
This segment could reach $150 million-$300 million by 2029 if Qutenza or competing systems secure broader payer coverage and expand prescribing among pain specialists, neurologists, podiatrists, and diabetes-care providers.
Which companies compete in the capsaicin market?
The competitive landscape is divided between mass-market OTC manufacturers and specialty prescription companies.
OTC competitors
The OTC market includes branded and private-label products from consumer-health companies, pharmacy chains, and topical-pain specialists. Competitive factors include:
- Retail shelf access
- Formulation tolerability
- Patch adhesion
- Odor and skin feel
- Duration of effect
- E-commerce visibility
- Brand-level advertising
- Product price
The OTC segment has low barriers to entry for creams and gels. Manufacturers can generally source capsaicin API from multiple suppliers, use established topical manufacturing processes, and compete through distribution.
Prescription competitors
Qutenza competes with systemic and local treatments for neuropathic pain, including:
- Pregabalin
- Gabapentin
- Duloxetine
- Tricyclic antidepressants
- Lidocaine patches
- Compounded topical agents
- Botulinum toxin in selected pain settings
- Spinal and interventional pain procedures
Qutenza's differentiation is local administration with limited systemic exposure and a treatment interval that can extend for several months in some patients. Its disadvantages include application-site pain, the need for trained personnel, procedural time, and reimbursement complexity.[3]
What is the FDA regulatory status of capsaicin?
Capsaicin has two distinct U.S. regulatory pathways.
OTC status
Low-concentration topical capsaicin products are regulated under the FDA external analgesic framework when they meet the applicable monograph conditions. These products generally do not depend on a single innovator patent estate and are sold through multiple manufacturers.
Prescription status
Qutenza is approved under NDA 022395. FDA approved Qutenza in 2009 for postherpetic neuralgia and later expanded the indication to diabetic peripheral neuropathy of the feet.[3]
The product is an administered topical system rather than a conventional self-applied cream. Its regulatory value lies in the approved indication, standardized 8% delivery system, manufacturing controls, and clinician-use instructions.
What patents protect capsaicin products?
The capsaicin molecule itself is old and cannot support meaningful composition-of-matter exclusivity. Commercial protection therefore depends on formulation, patch construction, manufacturing processes, dosing methods, packaging, and use-specific claims.
OTC patent protection
Most low-dose capsaicin creams, gels, and patches have limited patent protection. Their defensibility generally comes from:
- Trademark and brand investment
- Retail distribution
- Formulation know-how
- Patch adhesive design
- Packaging and consumer convenience
- Regulatory compliance
- Scale manufacturing
An OTC capsaicin cream is usually vulnerable to rapid private-label and generic substitution.
Qutenza patent protection
Qutenza's potential intellectual-property protection has historically centered on the 8% capsaicin topical system, application method, delivery format, and related manufacturing or use claims. Patent status is jurisdiction-specific and changes as patents expire, are abandoned, or become unenforceable.
The practical conclusion is that the core capsaicin composition is not a durable barrier. Any remaining protection would need to arise from device, formulation, method-of-use, or process claims. A competitor may still enter with a non-infringing patch or alternative high-concentration delivery system even if selected patents remain active.
What is the Orange Book status of Qutenza?
Qutenza is associated with an FDA-approved prescription NDA, but Orange Book protection must be assessed using the current FDA Orange Book listing and the specific patent certifications submitted by an abbreviated new drug application applicant.[4]
The relevant commercial points are:
- Low-dose OTC capsaicin products generally do not rely on Orange Book-listed patents.
- Qutenza's regulatory exclusivity is separate from patent exclusivity.
- Any generic or follow-on applicant must address listed patents through the applicable certification pathway.
- A Paragraph IV certification could create litigation risk if an applicant challenges an unexpired listed patent.
- A product that uses a materially different delivery system may avoid some listed claims but still face regulatory, clinical, and manufacturing barriers.
Because capsaicin is a small molecule and not a biologic, biosimilar legislation is not relevant. The likely competitive pathway is an ANDA, a 505(b)(2) application, or a region-specific hybrid application rather than a biosimilar application.
When does capsaicin lose exclusivity?
Capsaicin has already lost molecular exclusivity. The relevant exclusivity question concerns branded delivery systems and approved prescription uses.
| Protection category | Commercial position |
|---|---|
| Capsaicin active ingredient | Public-domain molecule |
| OTC cream formulation | Generally low patent barrier |
| OTC patch formulation | Potential device and formulation claims |
| Qutenza active ingredient | No composition-of-matter exclusivity |
| Qutenza delivery system | Potential formulation, device, process, and use protection |
| FDA regulatory exclusivity | Must be assessed from the product's approval history |
| Biosimilar exclusivity | Not applicable |
The largest risk to Qutenza is likely not a classic biosimilar event. It is differentiated follow-on competition from another high-concentration capsaicin system, an authorized or generic version, or a 505(b)(2) product supported by bridging data.
How strong is the capsaicin patent estate?
The patent estate is weak for the molecule and low-dose OTC products, but potentially moderate for high-concentration prescription delivery systems.
| Asset | Patent strength | Generic-entry risk |
|---|---|---|
| Capsaicin API | Very low | Very high |
| Standard OTC cream | Low | High |
| Standard OTC patch | Low to moderate | Moderate to high |
| 8% prescription patch | Moderate, depending on live claims | Moderate |
| Application protocol and clinic workflow | Low to moderate | Moderate |
| Manufacturing process | Moderate if difficult to replicate | Moderate |
| Branded clinical evidence | Not patent protection, but commercially relevant | Can delay adoption of entrants |
Manufacturing is a more important barrier for Qutenza than for ordinary creams. An 8% system must deliver a high payload consistently, maintain patch integrity, control exposure during handling, and meet occupational and patient-safety requirements. Those barriers raise development costs but do not create permanent exclusivity.
What generic launch scenarios exist for Qutenza?
Scenario 1: No direct generic before 2029
The incumbent retains the prescription market if patent uncertainty, development cost, reimbursement friction, or limited market size discourages ANDA investment. OTC products continue to capture most capsaicin volume.
Scenario 2: One follow-on high-concentration system
A single entrant gains approval through an ANDA or 505(b)(2) route. Initial price erosion could reach 15%-30%, depending on substitution rules and payer contracting. The incumbent may retain share through clinical familiarity and provider training.
Scenario 3: Multiple entrants
Two or more entrants enter after patent barriers weaken. Net pricing could decline 30%-60% over several years, while total treated patients increase because of lower cost. Incumbent revenue would face greater pressure than unit demand.
Scenario 4: Follow-on delivery innovation
A competitor launches a self-administered or lower-burden delivery format. This would be more disruptive than a conventional generic because it could expand the treatment setting and reduce clinic labor costs.
What litigation and settlement risks affect capsaicin?
Capsaicin litigation risk is concentrated in prescription high-concentration products. The principal triggers are:
- Paragraph IV challenges to listed Qutenza patents
- Patent disputes over patch construction
- Formulation and concentration claims
- Method-of-use claims for diabetic neuropathy
- Manufacturing-process claims
- Trade-secret disputes involving high-load patch production
- Trademark or trade-dress disputes in the OTC market
No broad biosimilar litigation pathway applies. Any settlement would need to be evaluated for entry date, authorized-generic rights, supply arrangements, patent licenses, and restrictions on alternative formulations. A settlement that permits early entry may reduce price erosion but preserve a substantial portion of the incumbent's revenue.
How does capsaicin compare with lidocaine and diclofenac?
| Factor | Capsaicin | Lidocaine | Diclofenac |
|---|---|---|---|
| Main mechanism | TRPV1 desensitization | Local sodium-channel blockade | Topical NSAID |
| OTC presence | Extensive | Extensive | Extensive in many markets |
| Prescription high-value product | Qutenza | Lidoderm and other systems | Prescription gels and solutions |
| Neuropathic-pain positioning | Strong for selected conditions | Strong localized option | Limited for neuropathic pain |
| Systemic exposure | Low for topical products | Low to moderate | Higher clinical concern than capsaicin |
| Application tolerability | Burning is common | Generally favorable | Skin reactions and NSAID warnings |
| Patent barrier | Low for molecule; moderate for systems | Mature and fragmented | Mature and fragmented |
| Growth outlook | Moderate | Moderate | Moderate |
Capsaicin has a stronger mechanistic and commercial position in localized neuropathic pain than diclofenac. Lidocaine is usually easier for patients to tolerate initially. Qutenza's economic value depends on whether extended duration offsets the clinic-administered treatment burden.
What is the revenue exposure for capsaicin manufacturers?
Revenue exposure differs sharply by product type.
- OTC manufacturers face high volume but low margins and substantial private-label competition.
- Prescription manufacturers face lower unit volume but higher revenue per treatment.
- API suppliers benefit from broad demand but have limited pricing power.
- Patch manufacturers have greater technical differentiation than cream manufacturers.
- Specialty distributors and clinics capture part of the economics through administration and reimbursement.
For a company with a $100 million capsaicin franchise, a 20% decline in Qutenza-like net pricing could reduce annual product revenue by approximately $20 million before volume growth. For an OTC supplier, a 10% retail-price decline may produce a smaller percentage impact on units but a larger effect on gross margin.
Key Takeaways
- The global finished-product capsaicin market is estimated at $0.8 billion-$1.2 billion in 2024.
- Base-case sales reach approximately $1.34 billion by 2029.
- OTC creams, gels, patches, and roll-ons account for most revenue.
- Qutenza is the principal high-value prescription capsaicin product.
- Prescription high-concentration capsaicin could grow 7%-11% annually through 2029.
- Capsaicin has no meaningful composition-of-matter patent protection.
- Formulation, patch, manufacturing, and method-of-use claims determine remaining prescription IP value.
- Biosimilar risk is irrelevant because capsaicin is a small molecule.
- The principal generic risk is a follow-on 8% or other high-concentration delivery system.
- Market growth depends on neuropathic-pain diagnosis, payer coverage, clinical capacity, and patient tolerance.
FAQs About Capsaicin Drug Market and Sales
Is capsaicin a prescription drug or an over-the-counter medicine?
Both. Low-dose creams, gels, and patches are commonly sold over the counter. Qutenza, an 8% capsaicin topical system, is a prescription product administered by healthcare professionals.
Does capsaicin have biosimilar competition?
No. Capsaicin is a small-molecule active ingredient. Future competition would normally use generic, ANDA, 505(b)(2), or hybrid regulatory pathways.
Is Qutenza more valuable than OTC capsaicin cream?
Qutenza generates substantially higher revenue per treatment because it is a prescription, clinician-administered product. OTC capsaicin generates greater aggregate volume because it is widely available and inexpensive.
What is the largest commercial risk to Qutenza?
The largest risk is a follow-on high-concentration capsaicin system that achieves regulatory approval, payer coverage, and comparable clinical acceptance while reducing treatment cost or clinic burden.
Can a company patent a new capsaicin cream?
A company may obtain patents for a novel formulation, delivery system, manufacturing process, concentration range, or method of use if the claims satisfy patentability requirements. The capsaicin molecule itself is not patentable as a new composition.
References
-
Grand View Research. (2024). Capsaicin market size, share and trends analysis report. Grand View Research.
-
U.S. Food and Drug Administration. (2024). External analgesic drug products for over-the-counter human use: 21 C.F.R. Part 348. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2020). Qutenza prescribing information. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. U.S. Department of Health and Human Services.
More… ↓
