Share This Page
Drug Sales Trends for ENOXAPARIN
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ENOXAPARIN (2014)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
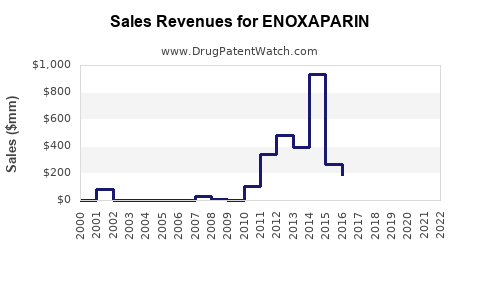
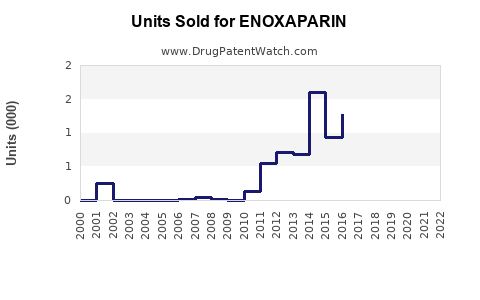
Annual Sales Revenues and Units Sold for ENOXAPARIN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ENOXAPARIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ENOXAPARIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ENOXAPARIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ENOXAPARIN | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Enoxaparin Market Analysis, Sales Projections, Patent Status and Generic Competition
Enoxaparin is a mature, globally established low-molecular-weight heparin used for venous thromboembolism prevention and treatment, acute coronary syndromes, and perioperative anticoagulation. The market is largely generic in the United States and Europe, while Sanofi’s Lovenox remains commercially important in several markets.
The global enoxaparin market is estimated at approximately $2.4 billion to $2.8 billion in 2024. A base-case model projects revenue of $2.8 billion to $3.3 billion by 2029, representing a compound annual growth rate of about 3% to 4%. Volume growth is likely to exceed revenue growth because pricing remains under pressure from generic manufacturers, hospital tenders, and regional suppliers.
What is the current market size for enoxaparin?
Enoxaparin market value is concentrated in hospital anticoagulation, postoperative prophylaxis, acute coronary syndrome treatment, and high-risk medical inpatients. The market includes branded Lovenox, authorized generics, conventional generic enoxaparin sodium, and regionally approved products.
| Market metric | 2024 estimate | 2029 base case |
|---|---|---|
| Global market revenue | $2.4 billion-$2.8 billion | $2.8 billion-$3.3 billion |
| Implied CAGR | N/A | 3%-4% |
| Generic and non-originator share by volume | 75%-85% | 82%-90% |
| Hospital and institutional share | 65%-75% | 65%-75% |
| Retail and specialty pharmacy share | 25%-35% | 25%-35% |
| Largest product segment | Prefilled syringes | Prefilled syringes |
| Highest-growth use | Thromboprophylaxis and outpatient treatment | Thromboprophylaxis and outpatient treatment |
The estimate excludes unfractionated heparin and other low-molecular-weight heparins such as dalteparin and tinzaparin. It includes sales of enoxaparin sodium across major markets and dosage forms.
Sanofi reported Lovenox sales of more than €1 billion annually in recent years, although the branded product has experienced long-term erosion from generic competition and tender pricing.[1] The originator’s reported sales should not be treated as the size of the total enoxaparin market because generic and local manufacturers account for a large proportion of volume.
What are the main drivers of enoxaparin sales growth?
The strongest demand drivers are hospital admissions, surgical procedures, cancer-associated thrombosis, cardiovascular disease, obesity, and expansion of outpatient anticoagulation.
Hospital and surgical demand
Enoxaparin is widely used after orthopedic surgery, abdominal surgery, cancer surgery, and major inpatient procedures. Prefilled syringes reduce preparation requirements and support standardized hospital administration.
Cardiovascular indications
The product is used in unstable angina, non-ST-elevation myocardial infarction, and selected ST-elevation myocardial infarction protocols. This indication supports demand even where direct oral anticoagulants have displaced some long-term thromboprophylaxis.
Cancer-associated thrombosis
Patients with active cancer have elevated venous thromboembolism risk. Enoxaparin remains an established treatment option, particularly when oral therapy is unsuitable because of drug interactions, gastrointestinal absorption issues, bleeding risk, or procedural requirements.
Outpatient treatment
The shift from inpatient to outpatient care supports prefilled syringe demand. Patients can administer subcutaneous doses at home after surgery, during pregnancy, or for selected treatment courses.
Emerging-market access
Generic manufacturing and local procurement are expanding access in Latin America, Asia-Pacific, the Middle East, and parts of Eastern Europe. These markets are more volume-driven than price-driven and tend to favor local suppliers with tender access.
What are the five-year enoxaparin sales projections?
The base-case forecast assumes modest global volume growth, continued generic price erosion, stable clinical use, and gradual expansion in emerging markets.
| Scenario | 2024 revenue | 2029 revenue | CAGR | Principal assumptions |
|---|---|---|---|---|
| Downside | $2.4 billion | $2.5 billion | 0.8% | Faster tender price erosion and substitution by oral anticoagulants |
| Base case | $2.6 billion | $3.0 billion | 3.0% | Moderate volume growth and stable hospital utilization |
| Upside | $2.8 billion | $3.5 billion | 4.6% | Strong emerging-market growth and sustained injectable use |
Regional projection
| Region | 2024 share | 2029 outlook | Commercial interpretation |
|---|---|---|---|
| Europe | 30%-35% | Low single-digit growth | Mature generic market with strong tender pressure |
| North America | 25%-30% | Flat to low growth | High generic penetration and stable hospital demand |
| Asia-Pacific | 20%-25% | 5%-7% growth | Largest expansion opportunity by volume |
| Latin America | 8%-10% | 4%-6% growth | Public procurement and local manufacturing are important |
| Middle East and Africa | 5%-8% | 4%-6% growth | Uneven access and tender-dependent demand |
North America and Europe will remain large revenue markets, but Asia-Pacific should produce the highest incremental unit growth through 2029.
Which companies compete in the enoxaparin market?
The competitive market includes the originator, multinational generic companies, specialty injectable manufacturers, and local pharmaceutical suppliers.
| Company | Product or role | Competitive position |
|---|---|---|
| Sanofi | Lovenox | Originator brand, clinical recognition, established hospital contracts |
| Sandoz | Generic enoxaparin | Early U.S. generic entrant and major international supplier |
| Momenta Pharmaceuticals | Enoxaparin development and commercialization | Key role in establishing the U.S. generic pathway; later acquired by Johnson & Johnson |
| Teva | Generic enoxaparin | Broad generic infrastructure and institutional sales |
| Amphastar | Enoxaparin and injectable products | U.S. injectable manufacturing and hospital channel presence |
| Fresenius Kabi | Generic injectable anticoagulants | Hospital-focused global portfolio |
| Hikma | Injectable generics | Institutional and regional market access |
| Local manufacturers | Regional enoxaparin products | Competitive in public tenders and emerging markets |
The main competitive variables are regulatory approval, product consistency, prefilled syringe capacity, batch release data, hospital contracts, cold-chain execution, and supply reliability.
What is the FDA regulatory status of enoxaparin?
Enoxaparin is regulated in the United States as a complex mixture of low-molecular-weight heparin chains derived from unfractionated heparin. Generic manufacturers must demonstrate pharmaceutical equivalence and a high degree of similarity to the reference product, Lovenox.
The FDA approved the first generic versions of enoxaparin in 2010. The agency requires more than a conventional small-molecule bioequivalence package because the product has complex molecular characteristics and biological activity.[2]
The FDA’s approach includes evaluation of:
- Molecular-weight distribution
- Degree and pattern of sulfation
- Chemical composition
- Anticoagulant activity
- Anti-factor Xa and anti-factor IIa activity
- Heparin-induced thrombocytopenia risk
- Source material and manufacturing controls
- Product impurity profile
- Batch-to-batch consistency
FDA guidance identifies enoxaparin as a complex drug product for which analytical characterization and pharmacodynamic evidence are central to ANDA approval.[2]
What is the Orange Book status of Lovenox?
Lovenox is associated with NDA 020164. Its original composition and formulation exclusivity have expired, and multiple generic enoxaparin products have been approved. No meaningful U.S. market exclusivity remains for the core enoxaparin product.
| Exclusivity issue | Status |
|---|---|
| Original product approval | Expired |
| Core composition protection | Expired or no longer commercially blocking |
| Pediatric exclusivity | Not a current market barrier |
| New chemical entity exclusivity | Expired |
| Generic ANDA approvals | Established |
| Current blocking patent risk | Low for the core product |
| Orange Book significance | Historical and product-specific rather than commercially protective |
Orange Book listing status can change as products, patents, and labeling records are updated. The key commercial fact is that multiple ANDA-approved products already compete with Lovenox.[3]
What patents protect enoxaparin?
The principal patent estate for enoxaparin related to the originator product, manufacturing methods, low-molecular-weight heparin characteristics, and formulation or delivery systems. Those protections have expired or have been overtaken by generic approvals in the United States.
Composition and manufacturing patents
The most important historical disputes involved patents covering enoxaparin’s molecular profile and manufacturing process. Because enoxaparin is a heterogeneous mixture, process controls can affect the final molecular-weight distribution and biological activity.
Generic companies faced regulatory and litigation barriers involving:
- Depolymerization technology
- Molecular-weight distribution
- Chemical characterization
- Biological activity
- Starting-material controls
- Process reproducibility
- Product sameness
The expiration of core rights did not eliminate technical barriers. It reduced the legal exclusivity barrier while leaving manufacturing and regulatory complexity intact.
Formulation patents
Prefilled syringes, concentration, container-closure systems, and administration formats may be protected by narrower patents or regulatory filings in particular jurisdictions. These rights generally do not prevent competition from alternative syringe formats or vial presentations unless the competitor copies the protected configuration.
Method-of-use patents
Historical method-of-use protection covered prophylaxis and treatment of thromboembolic conditions, acute coronary syndromes, and perioperative settings. Broad use patents are no longer a meaningful barrier to generic entry because the principal indications are established and generic labels cover core uses.
When did enoxaparin lose exclusivity?
Enoxaparin lost meaningful U.S. product exclusivity when the FDA approved the first generic products in 2010. The first generic approvals followed litigation and regulatory work concerning whether a complex mixture could be shown to be equivalent to Lovenox.
The commercial exclusivity timeline is:
| Event | Date |
|---|---|
| Lovenox introduced in the United States | 1990s |
| Core originator patent period | Primarily expired by the late 2000s and early 2010s |
| First U.S. generic approvals | 2010 |
| Generic competition expanded | 2010 onward |
| Current status | Mature, multi-source generic market |
Which companies challenged Lovenox patents?
The most significant U.S. challenges involved Momenta and Sandoz, which pursued generic enoxaparin approval and defended the regulatory and patent position of their products. Teva and other generic manufacturers later expanded competition.
The litigation risk centered on whether generic products infringed process and product patents and whether the products met the statutory requirements for approval. Generic entry demonstrated that the originator’s patent estate did not prevent ANDA approval or sustained competition.
No current Paragraph IV campaign is expected to create a new market opening comparable to the 2010 generic launch because enoxaparin already has established generic competition. Paragraph IV filings may still arise for specific formulations, concentrations, devices, or new delivery systems, but they would have limited effect on the overall market.
What litigation and settlement issues affect enoxaparin?
Historical litigation focused on patent validity, infringement, regulatory approval, and the technical comparability of generic enoxaparin. The most commercially important disputes were tied to the launch of the first generic products.
Current litigation risk is more likely to involve:
- Product liability
- Manufacturing deviations
- Shortages
- Contract disputes
- Hospital procurement
- Device or syringe patents
- Anticompetitive conduct allegations
- Regulatory enforcement
Settlement agreements relating to the original generic launches affected timing and commercial entry. They no longer create a broad exclusivity barrier because the market has several suppliers.
What generic entry risks exist for enoxaparin?
Generic competition is already entrenched, but manufacturers face operational and regulatory risks.
Manufacturing barriers
Enoxaparin requires specialized depolymerization and purification capability. A manufacturer must control molecular-weight distribution, sulfation patterns, impurities, biological activity, and source-material variability.
Supply-chain barriers
The product depends on pharmaceutical-grade heparin starting material. Supply disruptions can arise from animal-source controls, regional manufacturing concentration, quality events, and import restrictions.
Regulatory barriers
The FDA and other regulators scrutinize batch comparability and analytical characterization. A manufacturing change can trigger additional regulatory work even when the active ingredient remains unchanged.
Commercial barriers
Hospital systems often prioritize supply reliability over brand preference. A supplier without dependable prefilled syringe capacity may lose tenders even if its product is approved.
Is biosimilar risk relevant to enoxaparin?
Traditional biosimilar risk is limited because enoxaparin is not a monoclonal antibody or therapeutic protein regulated through the standard biosimilar pathway. The more relevant category is complex generic competition.
Enoxaparin is derived from biological material and has heterogeneous molecular characteristics, but U.S. products are approved through ANDA procedures rather than the biosimilar pathway used for biologics. Competitors therefore create generic price pressure, not conventional biosimilar substitution risk.[2]
How does enoxaparin compare with direct oral anticoagulants?
Direct oral anticoagulants have displaced some long-term injectable anticoagulation, but they do not eliminate enoxaparin demand.
| Factor | Enoxaparin | Direct oral anticoagulants |
|---|---|---|
| Administration | Subcutaneous injection | Oral |
| Hospital and perioperative use | Strong | More limited around procedures |
| Pregnancy | Established use | Restrictions and limited use |
| Cancer-associated thrombosis | Established option | Increasing use |
| Reversal and monitoring | Established protocols | Drug-specific considerations |
| Generic pricing | Highly competitive | Increasing as patents expire |
| Outpatient convenience | Lower | Higher |
| Use in acute care | Strong | Variable |
Enoxaparin retains advantages when oral absorption is unreliable, rapid interruption is needed, pregnancy limits alternatives, or clinicians prefer an established injectable regimen.
What revenue exposure does enoxaparin create for manufacturers?
For Sanofi, Lovenox is a mature but still material revenue contributor. Its risk profile is different from a patented growth product because sales depend on volume retention, tender performance, supply reliability, and brand preference rather than exclusivity.
For generic manufacturers, enoxaparin can be strategically valuable despite low unit margins because it:
- Supports hospital portfolio sales
- Uses injectable manufacturing capacity
- Creates recurring institutional demand
- Benefits from stable clinical guidelines
- Has relatively high technical barriers to entry
- Provides a differentiated alternative to simple-molecule generics
The main downside is price compression. A manufacturer with only one approved presentation may face disproportionate exposure to shortages, recalls, or tender losses.
What are the likely enoxaparin launch scenarios?
Future launches will most likely involve incremental competition rather than a single disruptive entrant.
| Launch scenario | Probability | Market effect |
|---|---|---|
| Additional generic supplier | Moderate | Lower tender prices and greater supply redundancy |
| New prefilled syringe presentation | Moderate | Limited share shift, stronger institutional contracting |
| New regional manufacturer | High in emerging markets | Higher volume and lower local prices |
| Novel oral replacement | Low near term | Gradual substitution in selected outpatient uses |
| New injectable delivery device | Low to moderate | Potential premium positioning but limited market expansion |
| Major patent-driven market reset | Very low | Core exclusivity has already expired |
How strong is the enoxaparin patent estate?
The patent estate is weak as a barrier to core-product competition but remains relevant for manufacturing processes, devices, formulations, and jurisdiction-specific rights.
| Patent estate component | Current strength |
|---|---|
| Core active ingredient | Low |
| Original Lovenox exclusivity | Expired |
| Manufacturing know-how | Moderate to high |
| Analytical and process controls | Moderate |
| Prefilled syringe configuration | Low to moderate |
| New delivery systems | Potentially moderate |
| Method-of-use protection | Low |
| Trade secrets and operational know-how | High commercial value |
The most durable competitive advantage is manufacturing know-how, not patent exclusivity.
Key Takeaways
- The global enoxaparin market is estimated at $2.4 billion to $2.8 billion in 2024.
- Base-case revenue is projected to reach approximately $3.0 billion by 2029.
- Volume growth should exceed revenue growth because generic and tender pricing will remain under pressure.
- Lovenox retains brand and hospital recognition but has no meaningful core-product exclusivity.
- The first U.S. generic approvals in 2010 established a mature multi-source market.
- The main barriers are complex manufacturing, analytical characterization, heparin sourcing, and reliable prefilled syringe supply.
- Biosimilar risk is limited; complex-generic competition is the relevant framework.
- Asia-Pacific and other emerging markets offer the strongest volume growth.
- Future competition will likely come from additional suppliers, regional manufacturers, and presentation-level differentiation.
- Enoxaparin remains commercially defensible as a hospital injectable even as direct oral anticoagulants expand.
FAQs
Is enoxaparin still a profitable drug?
Yes. Profitability is strongest for manufacturers with efficient injectable capacity, reliable heparin sourcing, and hospital tender access. Commodity pricing limits margins for undifferentiated suppliers.
Is Lovenox still protected by patents?
Core Lovenox patent protection has expired or is no longer commercially blocking in the United States. Narrow rights involving devices, formulations, or manufacturing processes may remain relevant in specific jurisdictions.
Can a new generic enoxaparin product enter the U.S. market?
Yes. A new entrant must obtain FDA approval through the applicable ANDA pathway and demonstrate the required pharmaceutical, analytical, and pharmacodynamic comparability to the reference product.
Will Eliquis and Xarelto replace enoxaparin?
They will continue to displace some outpatient and long-term anticoagulation use, but enoxaparin remains important in surgery, hospitalization, pregnancy, acute care, and situations where injectable treatment is preferred.
What is the most important commercial risk for enoxaparin?
Supply reliability is the leading commercial risk. A manufacturer can lose hospital contracts through shortages, quality events, delayed batch release, or inadequate prefilled syringe capacity even without a patent challenge.
References
- Sanofi. (2024). 2023 annual report. Sanofi.
- U.S. Food and Drug Administration. (2018). Draft guidance on enoxaparin sodium. FDA.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
More… ↓