Share This Page
Drug Sales Trends for CELEXA
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for CELEXA (2014)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
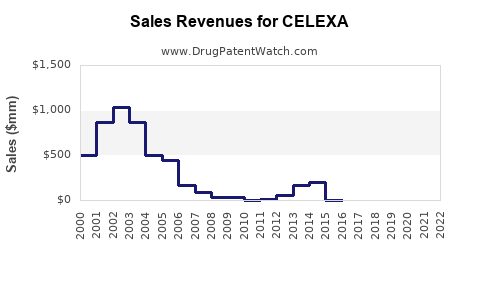
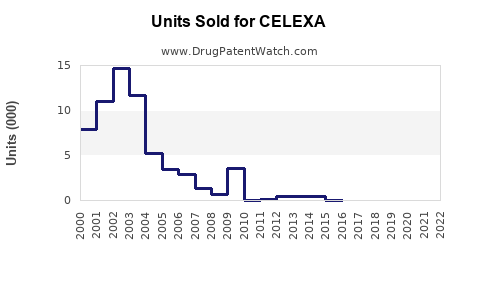
Annual Sales Revenues and Units Sold for CELEXA
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| CELEXA | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| CELEXA | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| CELEXA | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Celexa (Citalopram) Market Analysis, Sales Projections, and Patent Outlook
Celexa, the original brand of citalopram hydrobromide, is a mature selective serotonin reuptake inhibitor (SSRI) with no meaningful U.S. brand franchise remaining. The commercial market is generic, price-sensitive, and fragmented across manufacturers. Historical U.S. branded sales reached approximately $1 billion before generic entry, but current revenue is generated primarily through low-priced citalopram tablets and oral solution.
The base-case outlook is for a declining or flat global citalopram market through 2029. U.S. prescription demand should remain relatively stable because depression and anxiety treatment is chronic, but manufacturer revenue will remain under pressure from generic competition, limited product differentiation, and low reimbursement.
What is Celexa and how is citalopram used?
Celexa is the brand name for citalopram hydrobromide, an SSRI approved by the U.S. Food and Drug Administration for the treatment of depression in adults. The product is marketed in tablet and oral-solution forms. Standard tablet strengths include 10 mg, 20 mg, and 40 mg; the oral solution is typically supplied at an equivalent concentration of 10 mg per 5 mL [1].
Citalopram is used primarily for major depressive disorder. Prescribers also use it off-label for anxiety disorders, panic symptoms, obsessive-compulsive symptoms, and related conditions, although off-label use is not the basis of the FDA approval.
The product has several commercial limitations:
- It is an older SSRI with extensive generic competition.
- Citalopram has dose-related QT-interval prolongation concerns.
- The FDA recommends a maximum daily dose of 40 mg in adults and a lower maximum dose for older patients and patients with certain risk factors [1].
- Escitalopram, marketed as Lexapro, is the S-enantiomer of citalopram and competes directly in the depression market.
What is the FDA regulatory status of Celexa?
The FDA approved Celexa under New Drug Application 20-822 in 1998. The reference product is listed in the FDA’s Approved Drug Products with Therapeutic Equivalence Evaluations, commonly called the Orange Book [2].
| Regulatory item | Status |
|---|---|
| Active ingredient | Citalopram hydrobromide |
| Drug class | Selective serotonin reuptake inhibitor |
| Original brand | Celexa |
| Original U.S. approval | 1998 |
| Reference NDA | NDA 20-822 |
| Dosage forms | Tablets; oral solution |
| Current U.S. market | Generic-dominated |
| Biosimilar pathway | Not applicable |
| Current brand exclusivity | None of commercial significance |
Celexa is not a biologic and does not face biosimilar competition. Generic citalopram products are approved through the abbreviated new drug application pathway. Approved generics must demonstrate pharmaceutical equivalence and bioequivalence to the reference product.
When did Celexa lose exclusivity?
Celexa lost meaningful U.S. market exclusivity in the early 2000s. Generic citalopram entered the U.S. market after expiration of the relevant patent and regulatory exclusivity rights, causing rapid erosion of branded sales.
The historical exclusivity timeline is:
| Event | Approximate timing |
|---|---|
| U.S. Celexa approval | 1998 |
| Early branded commercial expansion | 1998-2001 |
| Peak commercial period | 2001-2002 |
| Generic entry | Early 2000s |
| Major branded price and share erosion | 2002-2004 |
| Current market structure | Predominantly generic |
Forest Laboratories, Celexa’s original commercial sponsor, reported strong pre-generic sales before the product transitioned into a mature generic category. Forest later focused on Lexapro, which extended the company’s SSRI franchise after citalopram’s loss of exclusivity [3].
What patents protected Celexa?
The original citalopram patent estate has expired. No live U.S. patent is known to provide commercially meaningful exclusivity for the original Celexa tablets.
Composition and active-ingredient patents
The original citalopram patent family covered the compound and related chemical subject matter. Those rights expired before the present generic market was established. Patent-term changes under the Hatch-Waxman framework did not preserve a long-term monopoly for the original Celexa product.
Formulation patents
Celexa’s conventional tablets and oral solution do not have a commercially significant current formulation barrier. Generic manufacturers can produce standard citalopram dosage forms without relying on a protected extended-release delivery system or proprietary device.
Method-of-use patents
The commercial value of citalopram is not protected by a current method-of-use patent estate. Depression treatment is a mature indication with extensive clinical and generic competition.
Orange Book status
The Orange Book historically provided the patent and exclusivity framework for Celexa’s reference product. Current Orange Book listings for citalopram do not create a practical barrier to ordinary generic entry. The relevant commercial question is price, supply reliability, and formulary access rather than patent validity.
How many patents cover Celexa today?
No active patent portfolio materially protects the original Celexa tablets in the U.S. Any historical patent counts depend on whether the analysis includes expired composition patents, foreign counterparts, manufacturing patents, or patents covering related compounds such as escitalopram.
For commercial due diligence, the actionable conclusion is that citalopram is an off-patent small molecule. Patent clearance is generally less important than:
- FDA approval status;
- manufacturing compliance;
- active pharmaceutical ingredient sourcing;
- drug-supply continuity;
- state and federal purchasing contracts;
- pharmacy benefit manager reimbursement;
- pricing discipline.
What is the current citalopram market size?
Public sources do not provide a single audited global revenue figure for citalopram because the market is divided among generic manufacturers, wholesalers, pharmacies, hospitals, and national health systems. The market must be estimated from prescription volume and net pricing.
The U.S. market remains clinically substantial. Citalopram continues to rank among the commonly prescribed antidepressants, although it competes with sertraline, escitalopram, fluoxetine, bupropion, venlafaxine, and duloxetine. Prescription use is supported by chronic treatment patterns and a large diagnosed and treated population [4].
A practical 2024 market estimate is:
| Market segment | Estimated annual manufacturer revenue |
|---|---|
| U.S. citalopram generics | $75 million-$150 million |
| Europe and other developed markets | $100 million-$200 million |
| Emerging markets | $50 million-$150 million |
| Estimated global total | $225 million-$500 million |
These figures represent analytical ranges for the citalopram molecule and its common dosage forms, not reported revenue for Celexa-branded products. Retail sales can be materially higher because they include wholesaler and pharmacy margins.
What are the sales projections for Celexa and citalopram?
Celexa-branded sales are expected to remain negligible in the U.S. The relevant commercial forecast is for generic citalopram.
Base-case forecast
| Year | Estimated global citalopram manufacturer revenue | Market outlook |
|---|---|---|
| 2024 | $225 million-$500 million | Mature generic market |
| 2025 | $220 million-$490 million | Stable demand; price pressure |
| 2026 | $215 million-$475 million | Continued generic erosion |
| 2027 | $210 million-$460 million | Volume offsets part of price decline |
| 2028 | $205 million-$445 million | Limited product differentiation |
| 2029 | $200 million-$430 million | Low-growth to declining market |
The base case assumes annual prescription volume is broadly stable or grows at 0% to 2%, while net pricing declines by approximately 2% to 5% annually in competitive markets.
Upside case
Revenue could approach the upper end of the range if:
- antidepressant treatment rates increase;
- supply disruptions affect competing SSRIs;
- manufacturers rationalize low-margin competitors;
- public-health programs expand access to generic depression treatment;
- emerging markets produce higher prescription growth.
The upside case is volume-driven. It does not depend on a return of meaningful branded pricing.
Downside case
Revenue could fall below the base range if:
- additional manufacturers enter high-volume markets;
- large pharmacy benefit managers accelerate generic price reductions;
- wholesalers reduce inventory;
- manufacturers exit because of low margins;
- competing SSRIs gain prescribing share;
- regulatory or manufacturing findings interrupt supply.
The downside risk is greater for manufacturers with high exposure to U.S. retail generics and limited portfolio diversification.
Which companies manufacture generic citalopram?
Generic citalopram has been supplied by a broad group of manufacturers and marketers. The competitive field has included Teva, Viatris and Mylan, Sandoz, Aurobindo, Zydus, Hikma, Solco, Rising Pharmaceuticals, Torrent, and other ANDA holders or contract suppliers.
Supplier participation varies by dosage strength, formulation, national market, and year. A manufacturer may hold an approved ANDA without maintaining active commercial distribution. The relevant competitive metric is therefore active supply, not the total number of historical approvals.
Competitive structure
The market has the characteristics of a low-barrier generic category:
- Multiple approved suppliers;
- Limited product differentiation;
- High substitution rates at the pharmacy level;
- Strong payer bargaining power;
- Low tolerance for manufacturing interruptions;
- Limited ability to raise prices without losing contracts.
Manufacturer profitability depends more on cost position and supply reliability than on brand equity.
What generic entry risks exist for Celexa?
Generic entry risk is no longer a future event for Celexa. It is the defining market condition. The principal risks are commercial rather than patent-related.
| Risk | Impact |
|---|---|
| Price erosion | High |
| New generic entrant | Moderate where supply is concentrated |
| Patent challenge | Low |
| FDA manufacturing action | Moderate |
| API shortage | Moderate |
| Brand substitution | Already realized |
| Reformulation competition | Low |
| Reimbursement pressure | High |
A new ANDA entrant could reduce prices further, but the effect would depend on the number of active suppliers and available manufacturing capacity. In a market with many suppliers, additional entry often has a smaller incremental effect than a major payer contract loss or manufacturing shutdown.
Which companies are challenging Celexa exclusivity?
No current Paragraph IV litigation is central to the U.S. Celexa market. The key Paragraph IV period occurred around the original generic-entry cycle in the early 2000s, when generic applicants challenged or sought to navigate the relevant citalopram patent rights.
Because those patents have expired and generic products are already established, a new Paragraph IV challenge would have little strategic value against the original Celexa reference product. Current commercial competition occurs through ANDA approval, pricing, procurement, and supply contracts.
What patent litigation affects Celexa?
No active patent litigation is known to create a material barrier to generic citalopram sales. Historical disputes associated with citalopram and related products were overtaken by patent expiry and market entry.
The more relevant legal issues today are likely to involve:
- Product liability;
- Manufacturing quality;
- False or misleading promotion;
- Drug-supply contracts;
- Antitrust claims involving generic pricing;
- Regulatory compliance.
These issues affect individual manufacturers but do not restore exclusivity to Celexa.
How does Celexa compare with Lexapro and other SSRIs?
Celexa’s closest branded and clinical comparator is Lexapro, the brand name for escitalopram oxalate. Escitalopram was developed as the S-enantiomer of citalopram and achieved a later commercial lifecycle.
| Product | Active ingredient | Market status | Commercial position |
|---|---|---|---|
| Celexa | Citalopram | Generic-dominated | Mature, low-price |
| Lexapro | Escitalopram | Generic-dominated | Larger historical franchise |
| Zoloft | Sertraline | Generic-dominated | High-volume SSRI |
| Prozac | Fluoxetine | Generic-dominated | Mature, broad historical use |
| Paxil | Paroxetine | Generic-dominated | Mature, declining share |
Escitalopram generally has stronger commercial recognition and a more favorable historical brand profile than citalopram. Sertraline is a major competing generic because of broad use and prescribing familiarity. Citalopram retains a stable role but has limited pricing power.
What is the revenue exposure for pharmaceutical companies?
For most current suppliers, citalopram is a portfolio product rather than a strategic growth asset. Revenue exposure is usually modest unless a company has:
- A large share of a national tender;
- A low-cost manufacturing platform;
- Concentrated supply in a market with few active suppliers;
- A differentiated oral-solution product;
- A temporary supply advantage.
The product can contribute predictable volume but is unlikely to support substantial research-and-development investment. A manufacturer evaluating acquisition or licensing value should focus on gross margin, active customers, manufacturing cost, and regulatory compliance rather than headline prescription volume.
What is the geographic coverage of citalopram?
Citalopram is sold in the United States, Europe, Canada, Australia, parts of Latin America, and numerous emerging markets. Regulatory status and commercial naming vary by jurisdiction.
The United States has high prescription volume but intense price competition. European markets also have mature generic substitution, often with national tendering. Emerging markets can offer higher volume growth, but pricing, registration, local manufacturing requirements, and distribution infrastructure reduce margin visibility.
The strongest commercial opportunity is generally supply efficiency in established markets, not patent-protected geographic expansion.
What manufacturing and intellectual-property barriers remain?
Manufacturing barriers are more important than patent barriers. A supplier must maintain validated production, comply with current good manufacturing practice requirements, secure API supply, and meet dissolution and stability specifications.
Key operational barriers include:
- Reliable citalopram hydrobromide API sourcing;
- Control of impurities and degradation products;
- Consistent tablet dissolution;
- Oral-solution stability;
- Packaging and serialization compliance;
- FDA inspection readiness;
- Capacity economics at low selling prices.
There is no major current intellectual-property barrier for standard citalopram tablets. Manufacturing scale and regulatory execution determine competitiveness.
Key Takeaways
- Celexa is an off-patent, generic-dominated SSRI.
- The original U.S. brand franchise lost meaningful exclusivity in the early 2000s.
- No current patent, formulation, or method-of-use right materially protects standard citalopram products.
- Estimated global manufacturer revenue is approximately $225 million to $500 million annually.
- Base-case global revenue is expected to decline gradually through 2029.
- U.S. demand should remain stable, but net pricing will remain under pressure.
- Generic manufacturers compete through cost, supply reliability, and payer access.
- No active Paragraph IV or patent litigation is expected to alter the market structure.
- The principal risks are price erosion, manufacturing disruption, API supply, and formulary pressure.
- Celexa has limited standalone investment value but can remain a predictable portfolio product.
FAQs about Celexa market size, patents, and sales
Is Celexa still sold as a branded drug?
Celexa has little to no meaningful branded commercial presence in the U.S. Citalopram is primarily dispensed as a generic product.
Does Celexa have any unexpired U.S. patents?
No unexpired U.S. patent is known to provide commercially meaningful exclusivity for standard Celexa tablets or oral solution.
Is citalopram a high-growth pharmaceutical market?
No. Citalopram is a mature generic market with stable clinical demand but declining or flat manufacturer revenue.
Could Celexa sales increase if antidepressant use rises?
Higher antidepressant utilization could increase citalopram prescription volume, but generic price competition would capture much of the benefit. Volume growth would not necessarily produce equivalent revenue growth.
Is citalopram exposed to biosimilar competition?
No. Citalopram is a small-molecule drug, so its competitive pathway is generic substitution through ANDAs rather than biosimilar approval.
References
- U.S. Food and Drug Administration. (2023). Celexa (citalopram hydrobromide) prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations.
- Forest Laboratories, Inc. (2003). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934.
- Centers for Disease Control and Prevention. (2024). Products - Data briefs - Number 470: Antidepressant use among adults.
More… ↓
