Share This Page
Drug Sales Trends for ASPIRIN
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ASPIRIN (2014)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
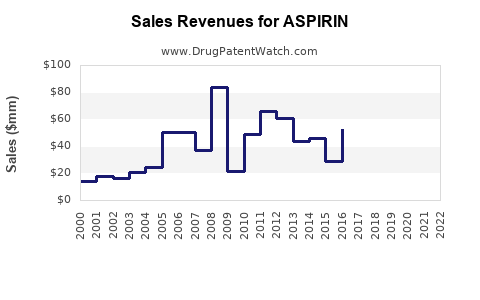
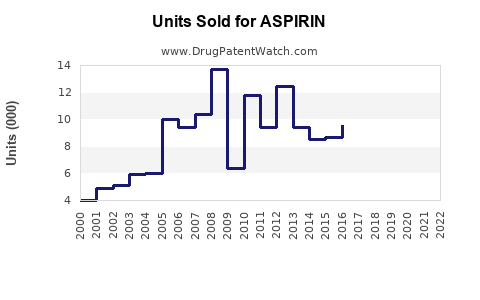
Annual Sales Revenues and Units Sold for ASPIRIN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ASPIRIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ASPIRIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ASPIRIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Aspirin Market Analysis, Patent Status, Competitive Landscape, and Sales Projections
Aspirin is a mature, off-patent medicine with broad global distribution and limited pricing power. Its commercial base is concentrated in low-cost generic and private-label products, while Bayer retains the strongest consumer brand in major markets. Global aspirin sales are estimated at approximately $2.0 billion to $3.0 billion in 2024, depending on whether the market definition includes hospital use, combination products, cardiovascular-dose products, and regional OTC sales. A base-case model indicates low-single-digit annual growth through 2030, driven by population aging and cardiovascular prevention demand, offset by generic pricing, clinical restrictions on primary prevention, and competition from acetaminophen and ibuprofen.
| Metric | Estimate or status |
|---|---|
| Active ingredient | Acetylsalicylic acid |
| Main uses | Analgesia, fever reduction, inflammation, antiplatelet therapy |
| 2024 global market estimate | $2.0 billion-$3.0 billion |
| Base-case 2030 market estimate | Approximately $2.5 billion-$3.5 billion |
| Forecast growth | Approximately 2%-4% CAGR |
| U.S. patent status | Core compound and historical manufacturing patents expired |
| U.S. regulatory status | OTC monograph product; prescription and hospital products also exist |
| Orange Book position | No meaningful active composition-of-matter protection |
| Biosimilar exposure | None |
| Generic entry risk | Structural and permanent |
| Leading branded company | Bayer |
| Main competitors | Private-label manufacturers, Perrigo, CVS, Walmart, Walgreens, Rite Aid, hospital suppliers |
What is the current aspirin market size?
The global aspirin market is mature and fragmented. Public market research estimates vary because some reports count only finished aspirin tablets, while others include low-dose cardiovascular products, combination analgesics, effervescent products, powders, hospital supply, and contract-manufactured private labels.
A practical 2024 market range is $2.0 billion to $3.0 billion at manufacturer and retail value combined. The midpoint of approximately $2.4 billion is suitable for scenario analysis, but it should not be treated as audited industry revenue.
How is aspirin revenue divided by therapeutic use?
| Segment | Estimated share of global value | Market characteristics |
|---|---|---|
| Low-dose cardiovascular prevention | 35%-45% | High volume, low price, recurring use |
| Analgesic and antipyretic use | 45%-55% | OTC-driven, heavily exposed to generic substitution |
| Anti-inflammatory and other uses | 5%-10% | Smaller share because alternatives are widely available |
| Combination and specialized delivery products | 3%-8% | Higher unit economics but limited scale |
Low-dose aspirin accounts for a large share of volume because patients may use it chronically. Its value contribution is lower than its unit share because 75 mg and 81 mg tablets are inexpensive and widely available.
The cardiovascular segment faces a mixed outlook. Aspirin remains important for secondary prevention in patients with established cardiovascular disease, but routine primary prevention is more restricted. The U.S. Preventive Services Task Force recommends against initiating low-dose aspirin for primary prevention in adults aged 60 years or older and recommends individualized decisions for some adults aged 40 to 59 with elevated cardiovascular risk (U.S. Preventive Services Task Force, 2022).
What are the aspirin sales projections through 2030?
A base-case forecast assumes a 2024 global market of $2.4 billion, annual growth of 3%, stable use in secondary prevention, modest growth in older populations, and continued erosion in branded pricing.
| Year | Bear case, 1% CAGR | Base case, 3% CAGR | Bull case, 5% CAGR |
|---|---|---|---|
| 2024 | $2.4B | $2.4B | $2.4B |
| 2025 | $2.42B | $2.47B | $2.52B |
| 2026 | $2.45B | $2.54B | $2.65B |
| 2027 | $2.47B | $2.62B | $2.78B |
| 2028 | $2.50B | $2.70B | $2.92B |
| 2029 | $2.52B | $2.78B | $3.07B |
| 2030 | $2.55B | $2.87B | $3.22B |
The base case produces approximately $2.9 billion in 2030 revenue. This represents market expansion in nominal value rather than strong branded growth. Unit demand can increase while average selling prices decline.
What will drive aspirin sales growth?
The main positive factors are:
- Aging populations and higher prevalence of established cardiovascular disease.
- Continued use in secondary prevention.
- Expansion of OTC distribution in emerging markets.
- Demand for enteric-coated, chewable, effervescent, and combination products.
- Growth in e-commerce and private-label pharmacy distribution.
- Hospital and institutional demand for standardized low-dose products.
The main negative factors are:
- Generic price competition.
- Reduced use for primary prevention.
- Substitution by acetaminophen and ibuprofen in pain markets.
- Bleeding-risk concerns and patient adherence limitations.
- Retail consolidation and retailer bargaining power.
- Product recalls or manufacturing interruptions affecting low-margin suppliers.
What patents protect aspirin?
No commercially important U.S. composition-of-matter patent protects aspirin. Acetylsalicylic acid was discovered and commercialized more than a century ago, and the relevant historical patent rights expired long ago.
Current protection is generally limited to:
- Trademarks, including the Aspirin brand.
- Packaging and trade dress.
- Formulation patents for specific release profiles, combinations, or delivery systems.
- Method-of-use claims covering narrowly defined therapeutic applications.
- Manufacturing know-how and quality-control processes.
- Regulatory exclusivity, where available for a specific new product rather than for aspirin itself.
These rights do not prevent ordinary generic aspirin tablets from entering the market.
Are aspirin formulation patents still relevant?
Formulation patents can protect differentiated products, but they do not create broad protection for the active ingredient. Potentially protectable attributes include:
- Enteric coating and delayed release.
- Extended-release low-dose formulations.
- Chewable or rapidly disintegrating tablets.
- Effervescent products.
- Fixed-dose combinations.
- Gastrointestinal-tolerability systems.
- Specialized pediatric or hospital presentations.
The commercial value of such patents depends on whether the product has FDA approval, meaningful clinical differentiation, physician adoption, and reimbursement or retail pricing support. A formulation patent without distribution or clinical differentiation is unlikely to support premium pricing in the core aspirin market.
When does aspirin lose exclusivity?
Aspirin lost meaningful compound exclusivity decades ago. The practical exclusivity position is therefore:
| Exclusivity category | Status |
|---|---|
| Composition-of-matter patent | Expired |
| Core manufacturing patent | Expired |
| Basic tablet formulation | Unprotected or expired |
| Trademark protection | Continues for registered marks |
| OTC monograph access | Available to compliant manufacturers |
| Product-specific formulation rights | May exist, depending on product |
| New-drug exclusivity | Not applicable to ordinary aspirin |
| Biosimilar exclusivity | Not applicable |
The commercial issue is no longer loss of exclusivity. It is the ability to retain brand recognition, secure shelf placement, maintain manufacturing reliability, and create a differentiated product.
What is the FDA regulatory status of aspirin?
Aspirin is available in the United States through OTC and prescription pathways. Standard analgesic and antipyretic products are governed by the FDA OTC monograph framework, including the internal analgesic, antipyretic, and antirheumatic monograph at 21 C.F.R. Part 343 (U.S. Food and Drug Administration, 2024a).
FDA-regulated products include:
- Adult analgesic and antipyretic tablets.
- Low-dose cardiovascular tablets.
- Chewable tablets.
- Enteric-coated tablets.
- Combination products.
- Prescription extended-release or specialized products.
- Hospital and institutional presentations.
Aspirin labeling must address gastrointestinal bleeding, hemorrhagic stroke risk, pediatric viral illness concerns, hypersensitivity, and interactions with anticoagulants and other antiplatelet agents. FDA has warned against routine use in children and teenagers with viral infections because of the association with Reye's syndrome (U.S. Food and Drug Administration, 2024b).
What is the Orange Book status of aspirin?
The FDA Orange Book is relevant to prescription aspirin products and listed combination products, but it does not provide market exclusivity for the ordinary OTC aspirin category. A prescription aspirin product may have product-specific patents or regulatory listings, but those rights do not block generic aspirin tablets sold under the OTC monograph.
The practical Orange Book conclusion is that standard aspirin has no meaningful active patent barrier comparable to a protected branded prescription drug.
Which companies sell aspirin?
Bayer is the leading global branded aspirin supplier. The Bayer Aspirin brand has strong recognition, particularly in the United States and Europe, but Bayer does not disclose aspirin revenue as a standalone reporting segment. Aspirin revenue is included within Bayer's Consumer Health business, which also contains allergy, dermatology, nutritional, and other OTC products (Bayer AG, 2024).
The competitive field includes:
| Company or channel | Competitive role |
|---|---|
| Bayer | Global branded aspirin and low-dose products |
| Perrigo | Private-label and store-brand OTC manufacturing |
| CVS, Walgreens, Walmart | Retailer-owned and private-label distribution |
| Rite Aid and regional pharmacies | Store-brand and generic distribution |
| Teva, Viatris, and other generic suppliers | Prescription and institutional products in selected markets |
| Contract manufacturers | High-volume supply for retailers and distributors |
| Hospital suppliers | Institutional low-dose and acute-care products |
Retailer-owned brands can compete directly with Bayer on the same shelf while offering materially lower prices. Brand loyalty is strongest among older consumers and patients who associate Bayer Aspirin with cardiovascular use.
What generic entry risks exist for aspirin?
Generic entry risk is effectively permanent because the core product is already genericized. The relevant risk is not a future Paragraph IV launch against Bayer's core brand. It is ongoing substitution at the point of sale.
How do Paragraph IV challenges apply to aspirin?
Paragraph IV litigation is generally relevant only to a patent-listed prescription formulation or combination product. A generic applicant may certify that a listed patent is invalid, unenforceable, or not infringed. For ordinary OTC aspirin tablets, the key market route is compliance with the FDA monograph rather than a Paragraph IV challenge to an active compound patent.
A Paragraph IV event could matter for:
- Extended-release aspirin products.
- Prescription aspirin combinations.
- Newly developed cardiovascular delivery systems.
- Products with a novel gastrointestinal-protection mechanism.
- Fixed-dose combinations involving a separately patented active ingredient.
No such challenge is needed to market standard aspirin.
What patent litigation affects aspirin?
There is no central patent dispute that controls the ordinary aspirin market. Litigation risk is product-specific and typically concerns:
- Combination products.
- Delivery technologies.
- Labeling or method-of-use claims.
- Manufacturing processes.
- Trade dress and trademark disputes.
- Product liability and warning claims.
The most material legal exposure is often product liability rather than patent litigation. Aspirin products carry known bleeding risks, and litigation can affect labeling, insurance cost, manufacturing controls, and brand reputation.
Is there biosimilar risk for aspirin?
Aspirin has no biosimilar risk because it is a small-molecule chemical drug, not a biologic. Competition arises through generic, OTC monograph, private-label, and authorized-generic channels.
This distinction matters commercially:
- No biologic reference-product exclusivity applies.
- No biosimilar interchangeability pathway applies.
- No biologic manufacturing complexity limits entry.
- Active-ingredient supply and quality controls remain important.
- Price competition is usually more severe than in biologic markets.
How strong is the aspirin patent estate?
The aspirin patent estate is weak for the core molecule and potentially moderate for narrow product innovations.
| Patent layer | Strength | Commercial effect |
|---|---|---|
| Core active ingredient | None | Does not restrict entry |
| Basic tablet | None or low | Easily substituted |
| Enteric coating | Low to moderate | Protects a defined product only |
| Extended release | Moderate if clinically differentiated | Can support limited premium |
| Combination products | Variable | Depends on partner ingredients and claim scope |
| Manufacturing process | Low to moderate | May reduce copying but rarely blocks supply |
| Trademark and packaging | Moderate for brand protection | Supports pricing and shelf recognition |
Aspirin is therefore a brand and distribution asset rather than a patent asset. The strongest defensibility lies in consumer awareness, pharmacy relationships, quality consistency, and global regulatory infrastructure.
What manufacturing and intellectual-property barriers affect aspirin?
The chemical synthesis of aspirin is established and relatively accessible. Manufacturing barriers are operational rather than inventive.
Key requirements include:
- Consistent acetylsalicylic acid purity.
- Control of hydrolysis and degradation.
- Stability through packaging and storage.
- Validated tablet compression and coating.
- Compliance with current good manufacturing practices.
- Reliable supply of active pharmaceutical ingredient.
- Testing for impurities and dissolution performance.
- Packaging that protects against moisture.
A supplier interruption can affect retail availability even when no patent barrier exists. Low product margins also make manufacturing scale, procurement efficiency, and retailer contracts decisive.
How does aspirin compare with acetaminophen and ibuprofen?
| Factor | Aspirin | Acetaminophen | Ibuprofen |
|---|---|---|---|
| Main use | Pain, fever, inflammation, antiplatelet therapy | Pain and fever | Pain, fever, inflammation |
| Cardiovascular role | Established antiplatelet use | None | No equivalent antiplatelet role |
| Bleeding risk | Meaningful | Lower gastrointestinal bleeding risk, but liver toxicity concern | Gastrointestinal, renal, and cardiovascular risks |
| Patent position | Fully mature generic | Fully mature generic | Fully mature generic |
| Brand strength | Strong, especially Bayer | Strong across multiple brands | Strong across multiple brands |
| Primary growth driver | Cardiovascular and OTC use | Broad analgesic demand | Broad analgesic demand |
| Key substitution risk | High in analgesia | High | High |
Aspirin has a unique cardiovascular use case, but its analgesic position is weaker than it was historically. Consumers and clinicians often favor acetaminophen or ibuprofen when antiplatelet activity is not desired.
What licensing deals affect aspirin?
There is no major current licensing transaction that controls access to standard aspirin. Licensing may occur around:
- Regional Bayer brand rights.
- Contract manufacturing.
- Retailer private-label supply.
- Fixed-dose cardiovascular combinations.
- Novel delivery systems.
- Hospital distribution agreements.
The lack of a core patent reduces the need for technology licensing. Commercial arrangements are more likely to involve trademarks, supply contracts, distribution rights, or co-branded products.
What are the likely generic launch scenarios?
Base scenario
Generic and private-label aspirin retain approximately 85%-95% of global unit volume, while branded products preserve a larger share of value. Bayer maintains premium pricing in mature markets, but annual price erosion remains in the low single digits.
Downside scenario
Retailers increase private-label penetration, cardiovascular primary-prevention use declines further, and consumers shift toward acetaminophen and ibuprofen. Branded revenue falls despite stable or rising unit demand.
Upside scenario
Aging populations expand secondary-prevention use, emerging-market access improves, and differentiated low-dose or combination products support modest value growth. The upside remains limited because basic aspirin remains widely substitutable.
What is the revenue exposure for Bayer and generic manufacturers?
Bayer has meaningful brand exposure but limited disclosure of aspirin-specific sales. Its risk is concentrated in consumer-health pricing, retailer bargaining power, product liability, and brand erosion rather than patent expiry.
Generic manufacturers have the opposite profile. They can gain volume but face:
- Low margins.
- High retailer concentration.
- API and packaging cost volatility.
- Recall exposure.
- Limited product differentiation.
- Contract-renewal risk.
The market is attractive for efficient high-volume suppliers but weak for companies relying on patent-protected premium pricing.
Key Takeaways
- Aspirin is a mature, off-patent small-molecule medicine.
- Global 2024 market value is reasonably estimated at $2.0 billion to $3.0 billion.
- A base-case model projects approximately $2.9 billion by 2030.
- Growth is likely to remain in the 2%-4% annual range.
- Cardiovascular secondary prevention supports demand, while primary-prevention restrictions limit expansion.
- Bayer has the leading consumer brand, but generic and private-label products dominate unit volume.
- No biosimilar risk exists.
- Paragraph IV litigation is relevant only to specialized prescription, combination, or formulation products.
- The strongest commercial protections are trademarks, distribution, manufacturing quality, and consumer recognition.
- Aspirin is a poor candidate for patent-driven premium pricing but remains a durable high-volume OTC and cardiovascular product.
FAQs
Does Bayer still have a patent on aspirin?
No commercially important U.S. patent protects the aspirin molecule. Bayer's principal advantage is its trademark, brand recognition, distribution, and product quality.
Will aspirin sales grow faster than the overall OTC analgesic market?
Probably not. Aspirin has a durable cardiovascular use but faces stronger substitution in pain relief. Its likely growth rate is lower than that of selected OTC categories with broader consumer adoption.
Can a company launch generic aspirin without a Paragraph IV certification?
Yes, standard OTC aspirin can generally be marketed under the applicable FDA OTC monograph if the product complies with the monograph and other regulatory requirements. Paragraph IV certification is mainly relevant to patent-listed prescription products.
Does low-dose aspirin require a prescription in the United States?
No. Low-dose aspirin is widely available over the counter. Some specialized or combination products may use prescription pathways.
Is aspirin a good target for a new pharmaceutical investment?
A basic aspirin product offers limited patent value and weak pricing power. Investment potential is stronger in differentiated delivery systems, clinically supported combinations, hospital supply, or high-efficiency private-label manufacturing than in ordinary tablets.
References
Bayer AG. (2024). Annual report 2023. https://www.bayer.com/en/investors/annual-reports
U.S. Food and Drug Administration. (2024a). 21 CFR Part 343: Internal analgesic, antipyretic, and antirheumatic drug products for over-the-counter human use. https://www.ecfr.gov/current/title-21/chapter-I/subchapter-D/part-343
U.S. Food and Drug Administration. (2024b). Aspirin: Questions and answers. https://www.fda.gov/
U.S. Preventive Services Task Force. (2022). Aspirin use to prevent cardiovascular disease: Preventive medication. JAMA, 327(16), 1577-1584. https://doi.org/10.1001/jama.2022.4983
More… ↓
