Share This Page
Drug Sales Trends for azathioprine
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for azathioprine (2013)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
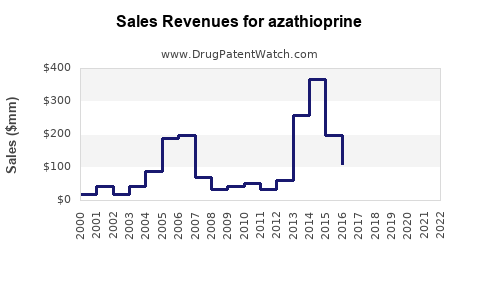
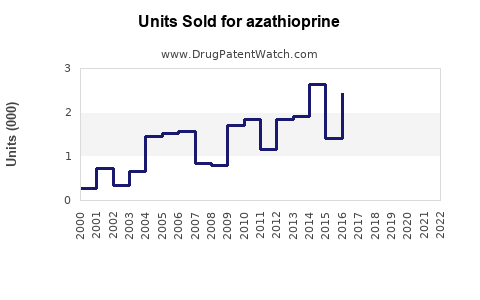
Annual Sales Revenues and Units Sold for azathioprine
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| AZATHIOPRINE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| AZATHIOPRINE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| AZATHIOPRINE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| AZATHIOPRINE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| AZATHIOPRINE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Azathioprine Market Analysis and Sales Projections, Patent Status, and Competitive Outlook
Azathioprine is a mature, low-cost immunosuppressant with no meaningful remaining originator exclusivity. Demand is supported by organ transplantation, autoimmune disease, inflammatory bowel disease, and steroid-sparing treatment. The market is genericized, fragmented, and price-sensitive. Global azathioprine sales are likely concentrated in tablets, with limited commercial upside unless a company obtains differentiated positioning through supply reliability, specialty distribution, combination therapy, or a new formulation.
A reasonable base-case forecast places worldwide azathioprine product revenue at approximately $180 million to $230 million in 2025, rising to $190 million to $260 million by 2030. Growth is driven mainly by patient volume and transplant activity, while generic price erosion limits revenue expansion.
What is azathioprine used for?
Azathioprine is a purine antimetabolite immunosuppressant. It is converted to active thiopurine metabolites that inhibit lymphocyte proliferation. The drug is administered orally and, in some markets, is available in injectable form.
| Therapeutic area | Commercial role | Demand characteristics |
|---|---|---|
| Organ transplantation | Maintenance immunosuppression | Stable, recurring demand; competition from tacrolimus and mycophenolate |
| Rheumatoid arthritis | Steroid-sparing and disease-modifying therapy | Declining relative use because of biologics and targeted therapies |
| Inflammatory bowel disease | Maintenance therapy, often after steroid induction | Persistent use, particularly where biologics are unaffordable |
| Autoimmune diseases | Lupus, autoimmune hepatitis, vasculitis, myasthenia gravis and related conditions | Specialist-driven, fragmented demand |
| Dermatology and other immune disorders | Off-label or guideline-supported use in selected conditions | Small but durable niche demand |
The U.S. prescribing information identifies azathioprine for rejection prevention in kidney transplantation and for management of active rheumatoid arthritis in selected patients. Other uses are based on clinical practice, guidelines, and local regulatory labeling rather than a single global indication set (U.S. Food and Drug Administration [FDA], 2024).
How large is the azathioprine market?
The market is difficult to measure because azathioprine is sold by multiple generic manufacturers, wholesalers, hospital pharmacies, and national procurement systems. Public companies generally do not report azathioprine revenue separately.
Estimated global market, 2025
| Segment | Estimated 2025 revenue | Market characteristics |
|---|---|---|
| Oral tablets | $150 million-$195 million | Core market; 25 mg and 50 mg strengths dominate |
| Hospital and injectable products | $10 million-$25 million | Concentrated in transplant and hospital settings |
| Specialty and institutional supply | $20 million-$35 million | Includes government tenders and controlled distribution |
| Total estimated market | $180 million-$230 million | Modeled market, not a consolidated audited figure |
The largest commercial markets are expected to be the United States, Europe, Japan, China, India, Australia, and selected Latin American countries. Revenue concentration does not necessarily track patient volume. Low-income and middle-income markets may have substantial unit demand but lower average selling prices.
Main market drivers
- Growth in the global transplant population and longer post-transplant survival.
- Continued use in autoimmune disease where biologics are unavailable, unaffordable, or clinically unsuitable.
- Demand for low-cost steroid-sparing therapy.
- Procurement requirements for multiple generic suppliers to reduce shortage exposure.
- Use in markets with limited reimbursement for biologic and targeted immunomodulator products.
Main market restraints
- Generic price competition.
- Substitution by tacrolimus, mycophenolate mofetil, mycophenolic acid, methotrexate, biologics, and targeted small molecules.
- Safety monitoring requirements.
- TPMT and NUDT15 pharmacogenetic considerations.
- Declining use in rheumatoid arthritis and some inflammatory diseases.
- Limited ability to differentiate a conventional tablet.
When does azathioprine lose exclusivity?
Azathioprine lost meaningful U.S. small-molecule exclusivity decades ago. The compound was commercialized under the Imuran brand, historically associated with GlaxoSmithKline and predecessor companies. Current U.S. products are predominantly generic.
| Exclusivity category | Current status |
|---|---|
| New chemical entity exclusivity | Expired |
| U.S. patent exclusivity | Expired or commercially irrelevant |
| Pediatric exclusivity | No material current protection identified |
| Orphan exclusivity | No broad orphan exclusivity controlling the product |
| Regulatory exclusivity | No current exclusivity blocking ordinary generic competition |
| Biosimilar exclusivity | Not applicable; azathioprine is a small molecule |
There is no credible path to restoring broad market exclusivity for the existing azathioprine molecule. Commercial protection would require a new product, such as a novel formulation, delivery system, combination, or independently patentable manufacturing process.
What patents protect azathioprine?
The original compound and core product patents are expired. Current patent risk is therefore more likely to arise from formulation, manufacturing, packaging, or use-specific claims than from the active ingredient itself.
Patent estate assessment
| Patent category | Current commercial relevance | Risk level |
|---|---|---|
| Azathioprine compound patents | Expired | None |
| Conventional immediate-release tablets | Generally unprotected | None to low |
| Dosage-strength claims | Usually not defensible against ordinary generics | Low |
| Treatment-method patents | Limited practical impact because of mature clinical use | Low |
| Extended-release or targeted delivery | Potentially relevant if separately patented | Product-specific |
| Combination products | Potentially relevant | Product-specific |
| Manufacturing and impurity-control processes | Possible process advantage | Low to moderate |
| Device or specialty packaging | Limited | Low |
The U.S. Orange Book should be reviewed for the specific NDA and listed patents associated with any current branded or specialty azathioprine product. Generic manufacturers should not assume that a listed patent for a modified product blocks approval of a conventional immediate-release tablet. Patent scope depends on the claims, dosage form, formulation, and regulatory filing route (FDA, 2024a).
What is the Orange Book status of azathioprine?
Azathioprine is marketed in the United States through legacy branded and generic approvals. The Orange Book remains relevant for identifying approved products, reference-listed-drug relationships, and any listed patents or exclusivities. In practice, the commercial market is dominated by abbreviated new drug applications for standard tablet products.
A generic applicant seeking approval for a conventional azathioprine tablet would generally use the reference product and demonstrate bioequivalence through the applicable abbreviated pathway. Paragraph IV certification is unlikely to create a major strategic event for ordinary azathioprine tablets because the foundational patent estate has expired.
Are there Paragraph IV challenges for azathioprine?
Paragraph IV litigation does not appear to be a central current market issue for conventional azathioprine. Any remaining challenge would likely concern a branded reformulation, new dosage form, or narrow method-of-use patent rather than the original molecule.
| Challenge type | Expected relevance |
|---|---|
| Challenge to original azathioprine compound patent | None; expired |
| Challenge to standard tablet patent | Low |
| Challenge to extended-release product | Possible |
| Challenge to combination product | Possible |
| Challenge to method-of-use patent | Limited and indication-specific |
| ANDA approval dispute | More likely to involve labeling, bioequivalence, or manufacturing than core composition |
No major active U.S. patent litigation materially controlling the standard azathioprine tablet market is evident from the mature generic profile of the product. A buyer or licensee should still conduct a current PACER, Orange Book, FDA Paragraph IV, and WIPO search before closing a transaction.
What is the competitive landscape for azathioprine?
Azathioprine competes with both low-cost immunosuppressants and higher-value specialty therapies.
Direct pharmacologic competitors
- Mycophenolate mofetil
- Mycophenolic acid
- Methotrexate
- Leflunomide
- Cyclophosphamide in selected severe autoimmune conditions
- Tacrolimus and cyclosporine in transplantation
Higher-value substitutes
- Adalimumab and other TNF inhibitors
- Ustekinumab
- Vedolizumab
- Risankizumab
- JAK inhibitors
- B-cell-directed therapies
- Calcineurin inhibitors and mTOR inhibitors in transplantation
Azathioprine retains a cost advantage. It is most exposed where treatment guidelines favor newer therapies, insurance coverage is strong, and physicians prioritize rapid or targeted immunologic control.
Azathioprine versus mycophenolate mofetil
| Attribute | Azathioprine | Mycophenolate mofetil |
|---|---|---|
| Price | Generally lower | Low-cost generic but often higher than azathioprine |
| Transplant use | Established maintenance option | Often preferred in modern protocols |
| Monitoring | CBC, liver function, pharmacogenetic considerations | CBC and infection monitoring |
| Pregnancy considerations | Used selectively with specialist oversight | More restrictive reproductive safety profile |
| Commercial outlook | Stable niche | Larger transplant franchise |
| Differentiation potential | Limited | Also highly genericized |
Azathioprine can remain competitive when cost, pregnancy planning, historical patient stability, or local protocol favors it. Mycophenolate is the stronger reference competitor in many transplant markets.
What formulations are protected by azathioprine patents?
The commercial baseline is the immediate-release oral tablet. Conventional 25 mg and 50 mg tablets have limited differentiation potential.
Potentially protectable products include:
- Extended-release tablets.
- Enteric-coated products intended to modify gastrointestinal exposure.
- Fixed-dose combinations with corticosteroids or other immunosuppressants.
- Pharmacogenomic dosing systems.
- Hospital-ready injectable presentations.
- Stability-enhanced products for hot or humid climates.
- Abuse-resistant or adherence-oriented packaging.
- Formulations designed to reduce gastrointestinal intolerance.
A formulation must provide a clinically or regulatory meaningful benefit to justify development. A minor excipient change without improved bioavailability, stability, tolerability, adherence, or manufacturing performance is unlikely to support durable pricing power.
How strong is the azathioprine patent estate?
The patent estate for the existing molecule is weak. The commercial strength of a new azathioprine product would depend on the product-specific claims, regulatory designation, clinical differentiation, and freedom to operate.
| Evaluation factor | Assessment |
|---|---|
| Core molecule protection | Very weak; expired |
| Generic entry barrier | Very low |
| Brand pricing power | Minimal for standard tablets |
| Manufacturing know-how | Potentially useful but rarely exclusionary |
| New formulation opportunity | Moderate but technically and commercially uncertain |
| Method-of-use protection | Narrow and difficult to enforce in mature indications |
| Litigation leverage | Low for standard products |
| Licensing value | Limited unless linked to a differentiated formulation or regional supply position |
What are azathioprine sales projections for 2025-2030?
The following projections use a bottom-up market model based on stable-to-low single-digit unit growth, continued generic price pressure, and modest expansion in transplant and autoimmune treatment volume. They represent estimated global product revenue rather than revenue for one manufacturer.
| Year | Bear case | Base case | Upside case |
|---|---|---|---|
| 2025 | $160 million | $205 million | $240 million |
| 2026 | $158 million | $208 million | $247 million |
| 2027 | $157 million | $212 million | $255 million |
| 2028 | $156 million | $216 million | $264 million |
| 2029 | $155 million | $221 million | $274 million |
| 2030 | $154 million | $226 million | $284 million |
Projection assumptions
The bear case assumes continuing price erosion, substitution by mycophenolate and biologics, and no significant new product differentiation. The base case assumes approximately 1% to 2% annual unit growth offset by low single-digit price declines. The upside case assumes stronger transplant demand, supply disruptions affecting competitors, and successful commercialization of a differentiated formulation.
The base-case compound annual growth rate is approximately 2%. This reflects a mature market where patient growth is partially offset by lower prices.
What is the revenue exposure for manufacturers?
A standard generic azathioprine portfolio is unlikely to generate high standalone revenue unless the manufacturer has scale, institutional contracts, or a broad immunosuppressant portfolio.
| Manufacturer profile | Revenue opportunity | Strategic rationale |
|---|---|---|
| Large generic company | Moderate volume, low margin | Portfolio completeness and hospital contracting |
| Specialty generic company | Moderate | Potential formulation or supply differentiation |
| Contract manufacturer | Low direct value | Stable but price-sensitive production demand |
| Branded specialty company | Limited | Requires a differentiated product |
| Regional supplier | Attractive in selected markets | Government tenders and shortage substitution |
| Biotech company | Low strategic fit | No biologic platform advantage |
Gross margins are likely to be higher for injectable, shortage-constrained, or institutionally contracted products than for standard tablets. Tablets remain vulnerable to tender pricing and pharmacy substitution.
What generic launch risks exist?
A new generic launch faces low legal barriers but significant commercial barriers.
Regulatory risks
- Failure to demonstrate bioequivalence.
- Product-specific dissolution variability.
- Manufacturing observations or warning letters.
- Inadequate control of impurities and degradation products.
- Labeling differences that affect substitution.
- Pharmacovigilance obligations for immunosuppression-related adverse events.
Commercial risks
- Incumbent suppliers with lower manufacturing costs.
- Small market size relative to development and registration expenses.
- Wholesaler concentration.
- Hospital formulary inertia.
- Limited ability to raise price after shortages resolve.
- Inventory write-downs from tender losses.
Clinical and safety risks
Azathioprine carries clinically important warnings involving myelosuppression, hepatotoxicity, serious infections, malignancy risk, and hypersensitivity. TPMT and NUDT15 status can influence toxicity risk. These issues do not usually prevent generic substitution, but they increase the importance of accurate labeling, patient monitoring, and pharmacovigilance (FDA, 2024; Clinical Pharmacogenetics Implementation Consortium, 2018).
Which companies are challenging azathioprine?
The market is challenged less by named patent litigants than by generic substitution and therapeutic alternatives. Generic manufacturers vary by jurisdiction and product presentation. In the United States, standard azathioprine products have historically been supplied by multiple generic companies, while branded availability has been limited relative to the original Imuran franchise.
Competitive pressure comes from:
- Generic azathioprine tablet manufacturers.
- Generic mycophenolate suppliers.
- Tacrolimus manufacturers.
- Specialty transplant-drug distributors.
- Biologic and targeted-therapy companies in autoimmune indications.
The main competitive question is not whether a company can enter the azathioprine market. It is whether it can secure sufficient volume and supply reliability to earn an acceptable return.
What is the FDA regulatory status of azathioprine?
Azathioprine is an FDA-approved small-molecule immunosuppressant. U.S. regulatory pathways include the original NDA framework and generic ANDA approvals. The drug is not a biologic, so biosimilar legislation and the Purple Book do not apply.
FDA-related commercial priorities include:
- Compliance with current good manufacturing practice requirements.
- Bioequivalence for generic products.
- Accurate warnings and contraindications.
- Pharmacovigilance for serious adverse events.
- Consistent supply for transplant patients.
- Appropriate handling of formulation or strength changes.
Does azathioprine have licensing or partnership value?
Licensing value is limited for standard azathioprine. More attractive opportunities may involve:
- Regional rights in markets with transplant growth.
- Supply agreements with hospitals or government buyers.
- A differentiated injectable product.
- A modified-release formulation.
- A pharmacogenomic dosing service linked to prescribing.
- Combination products with a defensible clinical or regulatory profile.
- Manufacturing technology that reduces cost or impurity burden.
A conventional tablet license without territorial access, guaranteed volume, or supply differentiation is unlikely to command significant upfront consideration.
What patent litigation affects azathioprine?
No major current litigation appears to control the ordinary generic azathioprine market. Litigation exposure is more likely to arise from:
- A new formulation patent.
- A combination-product patent.
- A manufacturing-process dispute.
- A contract or supply disagreement.
- Product liability or pharmacovigilance claims.
For transaction diligence, the relevant legal review should include Orange Book listings, ANDA Paragraph IV notices, federal district court filings, Federal Circuit decisions, FDA enforcement records, and patent assignments.
Key Takeaways
- Azathioprine is a mature generic immunosuppressant with no meaningful remaining core exclusivity.
- The estimated global market is approximately $180 million to $230 million in 2025.
- Base-case global revenue is projected to reach about $226 million by 2030.
- Transplantation is the most durable demand segment.
- Autoimmune and inflammatory disease use remains important but faces substitution from biologics and targeted therapies.
- Conventional tablets have weak patent protection and low entry barriers.
- A new commercial opportunity would require formulation, supply, geographic, or service differentiation.
- Paragraph IV litigation and biosimilar competition are not major current risks for standard azathioprine.
- Generic price pressure, procurement concentration, and therapeutic substitution are the main commercial threats.
- The strongest value proposition is reliable, low-cost supply in transplant and institutional markets.
FAQs
Is azathioprine still profitable for generic manufacturers?
It can be profitable at scale, particularly with efficient manufacturing, institutional contracts, or reliable supply during competitor shortages. Standard tablet pricing limits standalone profitability.
Is azathioprine included in Medicare coverage?
Coverage depends on the product, Part D formulary, pharmacy benefit design, and indication. Generic azathioprine is generally positioned as a low-cost formulary product.
Can a company patent a new azathioprine formulation?
Yes. A new formulation may be patentable if it provides a novel and non-obvious technical or clinical benefit. The patent would not restore protection for the original molecule.
Is azathioprine a biologic or biosimilar product?
No. Azathioprine is a conventional small-molecule drug. Generic approval generally proceeds through an ANDA or a comparable national pathway, not a biosimilar application.
What is the most attractive azathioprine market?
The most attractive opportunities are likely to be transplant-heavy markets, government procurement channels, and regions where biologic access is restricted and reliable low-cost immunosuppression is valued.
References
-
Clinical Pharmacogenetics Implementation Consortium. (2018). Clinical Pharmacogenetics Implementation Consortium guidelines for thiopurine dosing based on TPMT and NUDT15 genotypes. Clinical Pharmacology & Therapeutics, 103(2), 242-252. https://cpicpgx.org/guidelines/guideline-for-thiopurines-based-on-tpmt-and-nudt15-genotypes/
-
U.S. Food and Drug Administration. (2024). Azathioprine prescribing information. https://www.accessdata.fda.gov/
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
-
U.S. National Library of Medicine. (2024). Azathioprine drug information. DailyMed. https://dailymed.nlm.nih.gov/dailymed/
-
World Health Organization Collaborating Centre for Drug Statistics Methodology. (2024). ATC/DDD index: Azathioprine. https://www.whocc.no/atc_ddd_index/
More… ↓
