Share This Page
Drug Sales Trends for AGGRENOX
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for AGGRENOX (2013)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
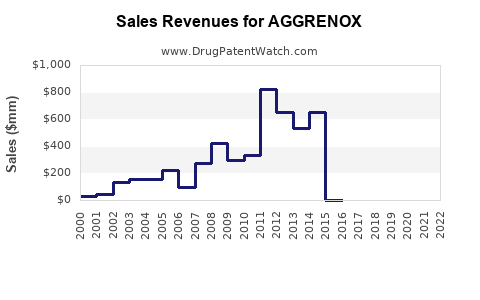
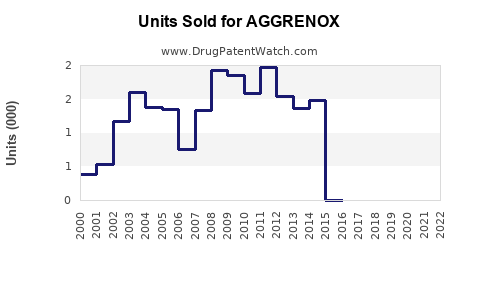
Annual Sales Revenues and Units Sold for AGGRENOX
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| AGGRENOX | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| AGGRENOX | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| AGGRENOX | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| AGGRENOX | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| AGGRENOX | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| AGGRENOX | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
AGGRENOX is a mature, genericized antiplatelet product with limited remaining brand value. The extended-release combination of aspirin 25 mg and dipyridamole 200 mg twice daily retains clinical relevance for secondary prevention of stroke, but generic competition, low-cost alternatives, and the availability of clopidogrel have sharply reduced pricing power. A reasonable U.S. market outlook is flat to declining volume, with total branded and generic sales concentrated in low-cost prescriptions and institutional channels.
AGGRENOX Market Analysis, Sales Projections, Patent Status, and Generic Competition
What is AGGRENOX and which patients use it?
AGGRENOX is an extended-release capsule containing aspirin 25 mg and dipyridamole 200 mg. The labeled indication is secondary prevention of stroke in patients who have experienced a prior ischemic stroke or transient ischemic attack [1].
The product is taken twice daily. Its pharmacologic profile combines irreversible platelet inhibition from aspirin with vasodilatory and antiplatelet effects from dipyridamole.
AGGRENOX competes primarily with:
- Clopidogrel, marketed as Plavix and available generically.
- Aspirin monotherapy.
- Aspirin plus extended-release dipyridamole administered as separate products.
- Other antithrombotic regimens used in selected cerebrovascular patients.
The key commercial limitation is price. Generic clopidogrel and aspirin are substantially cheaper and are familiar to prescribers. AGGRENOX therefore has a narrower role when physicians prefer the fixed-dose combination or when a patient has previously used the regimen successfully.
AGGRENOX product profile
| Attribute | Detail |
|---|---|
| Active ingredients | Aspirin 25 mg and extended-release dipyridamole 200 mg |
| Dosage form | Extended-release capsule |
| Dosing | One capsule twice daily |
| Therapeutic area | Secondary prevention of ischemic stroke |
| Original sponsor | Boehringer Ingelheim |
| U.S. regulatory pathway | New Drug Application |
| FDA approval | 1999 |
| Current competitive status | Genericized prescription product |
| Biosimilar exposure | None |
| Main substitutes | Clopidogrel, aspirin, separate aspirin/dipyridamole products |
How large is the AGGRENOX market?
The AGGRENOX market is a mature specialty-pharmacy and primary-care market rather than a high-growth pharmaceutical category. U.S. demand is linked to the number of patients with prior ischemic stroke or TIA, but prescription growth is constrained by generic substitution and treatment switching.
The market has three economic segments:
- Branded AGGRENOX prescriptions.
- Generic aspirin and dipyridamole extended-release capsules.
- Off-label or therapeutic substitutions involving clopidogrel and aspirin.
Public company disclosures have not consistently reported AGGRENOX as a standalone revenue line. Historical brand sales were materially higher before generic entry, but post-generic revenue is driven more by prescription retention and net price than by market expansion.
Demand drivers
The main positive demand factors are:
- Growth in the U.S. stroke survivor population.
- Increased diagnosis and follow-up of transient ischemic attack.
- Continued use of antiplatelet therapy for secondary prevention.
- Preference for a fixed-dose combination in patients requiring both agents.
- Refill persistence among patients stabilized on AGGRENOX.
The main negative factors are:
- Generic clopidogrel pricing.
- Aspirin monotherapy for lower-cost treatment.
- Physician concerns about headache, dyspepsia, bleeding, and twice-daily dosing.
- Substitution with separate generic components.
- Lack of meaningful brand differentiation after loss of market exclusivity.
What are AGGRENOX sales and revenue projections?
AGGRENOX revenue should be modeled as a declining or stable genericized market, not as a branded growth asset. The following projections are scenario estimates for the U.S. combined branded and generic market. They are not reported company guidance.
U.S. AGGRENOX market projection
| Year | Low case | Base case | High case | Principal assumption |
|---|---|---|---|---|
| 2024 | $45 million | $65 million | $85 million | Mature generic market |
| 2025 | $41 million | $62 million | $84 million | Continued price erosion |
| 2026 | $37 million | $59 million | $83 million | Stable patient pool, lower net price |
| 2027 | $34 million | $56 million | $81 million | Generic consolidation |
| 2028 | $31 million | $53 million | $79 million | Continued substitution |
| 2029 | $29 million | $50 million | $77 million | Low single-digit volume pressure |
The base case assumes approximately 1% annual prescription-volume growth from the stroke-survivor population, offset by 5% to 6% annual net-price erosion and continued conversion from branded to generic supply.
The high case assumes sustained product retention among established users, less aggressive generic discounting, and modest growth in treated secondary-prevention patients. The low case assumes accelerated substitution into clopidogrel and separate components.
Brand revenue outlook
Branded AGGRENOX revenue is likely to decline faster than total category revenue. A reasonable base case is:
| Year | Estimated branded revenue trend |
|---|---|
| 2024 | Index 100 |
| 2025 | 90-95 |
| 2026 | 81-90 |
| 2027 | 73-86 |
| 2028 | 66-82 |
| 2029 | 60-78 |
The range reflects uncertainty regarding brand availability, authorized-generic arrangements, payer coverage, and manufacturer participation. Generic revenue can remain relatively stable even as the branded product loses share because the active ingredients retain clinical demand.
When did AGGRENOX lose exclusivity?
AGGRENOX lost practical commercial exclusivity after expiration of its principal U.S. patent protection and subsequent approval of generic versions. The product was approved by the FDA in 1999, and the principal composition patent associated with the product had an expiration date in the late 2010s [2][3].
AGGRENOX exclusivity timeline
| Event | Approximate timing | Commercial effect |
|---|---|---|
| FDA approval of AGGRENOX | 1999 | Launch of fixed-dose combination |
| Initial branded market period | Early 2000s | Full branded pricing |
| Patent litigation and generic challenges | 2010s | Delayed or contested generic entry |
| Principal patent expiration | 2017 | Removal of key patent barrier |
| Generic approvals and launches | Mid-to-late 2010s | Rapid price and share erosion |
| Mature generic market | 2020s | Low growth and low pricing power |
The exact commercial loss-of-exclusivity date depends on the patent, pediatric exclusivity, litigation settlements, and the timing of individual ANDA launches. The principal economic event was generic entry after the expiration or neutralization of core patent protection.
What patents protect AGGRENOX?
AGGRENOX protection relied on patents covering the combination of aspirin and extended-release dipyridamole, the dosage form, and related pharmaceutical compositions. The principal patent commonly associated with the product is U.S. Patent No. 5,616,492, assigned to or associated with Boehringer Ingelheim-related interests [3].
The patent estate was more important before generic entry than it is today. The relevant U.S. patents have expired, and they no longer create a meaningful barrier to ANDA competition.
Patent protection by category
| Patent category | AGGRENOX relevance | Current commercial value |
|---|---|---|
| Fixed-dose combination | Covered aspirin plus dipyridamole in a combined product | Expired or no longer blocking |
| Extended-release formulation | Supported twice-daily dosage form | Limited after generic approval |
| Method of use | Secondary stroke prevention | Narrow and vulnerable to generic use |
| Manufacturing process | May protect production methods | Potentially relevant to suppliers, not market exclusivity |
| Device or packaging | Limited relevance for capsules | Low |
What is the Orange Book status of AGGRENOX?
AGGRENOX was listed in the FDA Orange Book through its NDA. Orange Book-listed patents can delay ANDA approval if a generic applicant files a Paragraph IV certification and the NDA holder sues within the statutory period [2].
Because the key AGGRENOX patent barriers have expired, Orange Book listings no longer provide the product with effective market exclusivity. Generic applicants can rely on ANDA procedures, subject to any remaining listed patent or regulatory requirements.
The regulatory distinction is important:
- Orange Book patents apply to small-molecule products such as AGGRENOX.
- Biosimilar procedures do not apply because AGGRENOX is not a biologic.
- Generic applicants file ANDAs rather than abbreviated biologics license applications.
- Therapeutic equivalence and substitutability depend on FDA approval and state pharmacy law.
Which companies challenged AGGRENOX patents?
AGGRENOX faced generic challenges from ANDA applicants during the period when patent protection still had commercial value. Publicly available litigation records and FDA patent-certification procedures indicate that generic manufacturers pursued approval through Paragraph IV or other patent-certification pathways.
The relevant competitor group included large generic manufacturers and vertically integrated pharmaceutical companies active in cardiovascular products. Generic competition ultimately emerged from manufacturers able to supply aspirin/dipyridamole extended-release capsules at substantially lower prices.
The commercial outcome was more important than the identity of each challenger: generic entry eliminated the product's ability to sustain historical branded pricing.
What patent litigation and settlements affected AGGRENOX?
AGGRENOX patent disputes centered on the validity, infringement, and enforceability of patents covering the extended-release combination. The typical litigation structure involved:
- An ANDA applicant filing a Paragraph IV certification.
- The NDA holder filing an infringement action.
- A potential 30-month stay of FDA approval under the Hatch-Waxman Act.
- Settlement, dismissal, or litigation judgment.
- Generic launch after patent expiry or an agreed entry date.
The main business consequence was timing. A settlement could create a commercial launch date before nominal patent expiry, while a successful patent defense could delay generic competition. Once the principal patents expired, settlement value declined sharply.
There is no significant present-day litigation thesis attached to AGGRENOX. The material legal issue is historical generic entry, not a current patent blockade.
How strong is the AGGRENOX patent estate?
The current patent estate is weak from an investment perspective because the commercially important U.S. patents have expired. The product may retain formulation know-how and manufacturing complexity, but these factors do not restore exclusivity.
Patent-strength assessment
| Factor | Assessment |
|---|---|
| Core composition protection | Expired |
| Extended-release formulation protection | Expired or nonblocking |
| Method-of-use protection | Limited practical value |
| New formulation opportunities | Possible but commercially difficult |
| Manufacturing barriers | Moderate technical barrier, low legal barrier |
| Generic substitution risk | High |
| Ability to raise price | Very low |
| Litigation leverage | Minimal |
The extended-release formulation may be more difficult to manufacture than immediate-release aspirin or dipyridamole. That can reduce the number of capable suppliers, but it does not create durable market exclusivity once multiple FDA-approved manufacturers are present.
What formulation and manufacturing barriers affect AGGRENOX?
The key technical challenge is maintaining the desired release profile for dipyridamole while combining it with low-dose aspirin in a capsule that remains stable and bioequivalent.
Manufacturers must manage:
- Extended-release performance.
- Dissolution specifications.
- Stability of aspirin, which can hydrolyze under unsuitable conditions.
- Uniformity of the two active ingredients.
- Bioequivalence against the reference product.
- Capsule filling and component segregation.
- Packaging conditions that protect product quality.
These requirements can create temporary supply constraints or limit the number of generic suppliers. They do not materially change the long-term pricing outlook.
Separate-component therapy is an important substitute because it may provide clinical flexibility and lower acquisition cost. The fixed-dose combination remains commercially useful where adherence and regimen simplicity outweigh the price premium.
How does AGGRENOX compare with clopidogrel?
Clopidogrel is the principal commercial comparator. It is available as a low-cost generic and is widely used in secondary prevention of cardiovascular and cerebrovascular events.
| Factor | AGGRENOX | Clopidogrel |
|---|---|---|
| Active therapy | Aspirin plus dipyridamole | P2Y12 platelet inhibitor |
| Dosing | Twice daily | Usually once daily |
| Fixed combination | Yes | No |
| Generic availability | Yes | Yes |
| Pricing power | Low | Very low |
| Adherence advantage | Combination in one capsule | Once-daily dosing |
| Common tolerability issue | Headache and gastrointestinal effects | Bleeding and drug-interaction considerations |
| Prescribing position | Selected secondary-prevention patients | Broad antiplatelet use |
| Competitive risk | High | Established generic standard |
AGGRENOX may retain use in patients for whom clinicians prefer aspirin/dipyridamole or who have an established treatment history. Clopidogrel has stronger commercial positioning because of once-daily dosing, broad familiarity, and lower cost.
What generic entry risks exist for AGGRENOX?
The generic entry risk is already realized rather than prospective. The remaining risks are price compression, payer-driven substitution, supply competition, and declining brand prescriptions.
Generic launch scenarios
| Scenario | Probability assessment | Market effect |
|---|---|---|
| Stable generic supply | Most likely | Gradual price erosion |
| Additional supplier entry | Plausible | Faster price compression |
| Supplier consolidation | Plausible | Temporary price stabilization |
| Product shortage | Periodic possibility | Short-term price or share disruption |
| Brand withdrawal | Possible | Generic volume migration |
| New branded formulation | Unlikely | Limited commercial upside |
A generic manufacturer can improve economics through manufacturing efficiency, limited competition, authorized-generic arrangements, or supply contracts. The product is unlikely to support premium pricing without a new clinical, adherence, or delivery-system advantage.
What is the FDA regulatory status of AGGRENOX?
AGGRENOX is an FDA-approved prescription drug for secondary prevention of stroke in patients with prior ischemic stroke or TIA [1]. Its regulatory status is that of a mature small-molecule combination product.
The key regulatory considerations are:
- FDA-approved reference product status under the original NDA.
- ANDA-based generic competition.
- Orange Book patent and therapeutic-equivalence listings.
- No biosimilar pathway.
- Continued pharmacovigilance for bleeding, headache, gastrointestinal effects, and hypersensitivity.
- Label compliance for patients with aspirin sensitivity or bleeding risk.
There is no regulatory exclusivity mechanism comparable to orphan-drug exclusivity or biologic reference-product exclusivity attached to the current product.
What licensing deals affect AGGRENOX?
AGGRENOX has been associated primarily with Boehringer Ingelheim's commercial development and marketing activities. Public disclosures do not establish a major current licensing transaction that would materially change the product's market outlook.
Any authorized-generic or distribution arrangement would affect the allocation of revenue between the brand owner, generic supplier, distributor, and pharmacy benefit channel. Such arrangements generally do not expand the total market. They change net price, market share, and margin distribution.
What revenue exposure does AGGRENOX create for manufacturers?
AGGRENOX is a low-growth, low-margin opportunity for generic manufacturers. Revenue exposure is concentrated in supply reliability and procurement contracts rather than scientific differentiation.
A generic supplier's economics depend on:
- API and excipient costs.
- Manufacturing yield.
- FDA compliance.
- Number of competing suppliers.
- Wholesaler and pharmacy benefit rebates.
- Reimbursement under Medicare Part D and commercial plans.
- Ability to maintain consistent extended-release specifications.
For the former brand owner, AGGRENOX represents declining legacy revenue and limited strategic growth. For generic manufacturers, the product can provide durable but modest revenue if competition remains rational.
What is the investment outlook for AGGRENOX?
AGGRENOX is best viewed as a mature cash-flow product with declining brand economics and limited patent optionality. The base-case market remains commercially viable because the treated patient population is large and chronic therapy supports recurring refills. The market does not offer meaningful exclusivity-driven upside.
Investment conclusions
- Brand revenue should continue to decline faster than total category volume.
- Generic sales can remain stable in nominal volume but face price erosion.
- Clopidogrel is the principal competitive constraint.
- Patent litigation has little current strategic value.
- Formulation complexity may support a limited supplier base but does not prevent substitution.
- A new formulation, adherence product, or differentiated delivery system would be required to create material growth.
- The most likely long-term outcome is a low-price, mature generic market.
Key Takeaways
- AGGRENOX is a fixed-dose aspirin and extended-release dipyridamole product for secondary stroke prevention.
- The product lost meaningful U.S. exclusivity after expiration of its core patent protection and generic entry.
- Its principal patent estate, including U.S. Patent No. 5,616,492, no longer provides a commercial barrier.
- The base-case U.S. market is estimated at about $65 million in 2024, declining to approximately $50 million by 2029.
- Branded revenue is likely to contract faster than total market revenue.
- Clopidogrel, aspirin monotherapy, and separate-component therapy are the main substitutes.
- No biosimilar risk exists because AGGRENOX is a small-molecule product.
- Manufacturing complexity can affect supplier participation but is unlikely to restore pricing power.
- The product has limited licensing, litigation, or patent-driven upside.
FAQs
Is AGGRENOX still available in the United States?
Yes. The product and generic equivalents may remain available through prescription channels, although manufacturer participation and supply can change over time.
Is aspirin dipyridamole the same as AGGRENOX?
Aspirin/dipyridamole is the same active-ingredient combination. AGGRENOX is the branded extended-release formulation. Generic products must meet FDA requirements for pharmaceutical equivalence and bioequivalence.
Can AGGRENOX be replaced by clopidogrel?
Physicians may consider clopidogrel as an alternative antiplatelet therapy, but substitution depends on the patient's clinical history, bleeding risk, prior treatment response, and prescribing judgment.
Does AGGRENOX have orphan-drug exclusivity?
No. AGGRENOX is used for a common secondary-prevention indication and does not have orphan-drug market exclusivity.
What would increase AGGRENOX sales?
Sales could improve through supply disruptions affecting competitors, stronger adherence to fixed-dose therapy, favorable formulary coverage, or a differentiated reformulation. None represents a high-probability structural growth driver for the current product.
References
- U.S. Food and Drug Administration. (2015). Aggrenox prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- United States Patent and Trademark Office. (1997). U.S. Patent No. 5,616,492: Pharmaceutical composition containing acetylsalicylic acid and dipyridamole.
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database.
- U.S. Food and Drug Administration. (1984). Drug Price Competition and Patent Term Restoration Act of 1984.
More… ↓
