Share This Page
Drug Sales Trends for RAPAFLO
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for RAPAFLO (2012)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
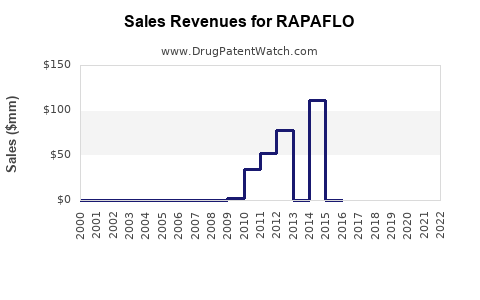
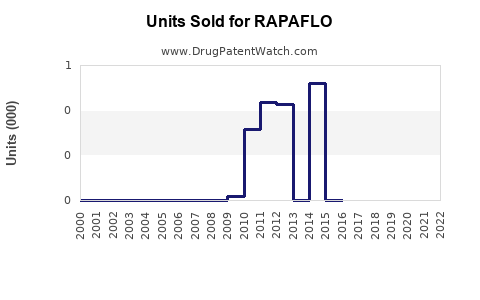
Annual Sales Revenues and Units Sold for RAPAFLO
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| RAPAFLO | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| RAPAFLO | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| RAPAFLO | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| RAPAFLO | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| RAPAFLO | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| RAPAFLO | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| RAPAFLO | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Rapaflo Market Analysis, Sales Forecast, Patent Position, and Generic Risk
Rapaflo, the U.S. brand for silodosin, is a mature alpha-1A adrenergic receptor antagonist used to treat urinary symptoms associated with benign prostatic hyperplasia, or BPH. Its commercial value has shifted from branded sales to low-cost generic silodosin. The U.S. brand has limited growth potential, while the broader silodosin molecule market remains supported by an aging male population and continued BPH diagnosis.
A reasonable base-case estimate places global silodosin sales across branded and generic products at approximately $140 million to $190 million in 2025, rising to $160 million to $230 million by 2029. Rapaflo-branded U.S. sales are likely below $10 million annually and may approach de minimis levels as generic substitution expands.
What is Rapaflo and how large is its target market?
Rapaflo contains silodosin, a selective alpha-1A adrenergic receptor antagonist. The FDA approved Rapaflo in October 2008 for the signs and symptoms of BPH in adult men.[1]
Silodosin relaxes smooth muscle in the prostate and bladder neck, improving urinary flow and reducing lower urinary tract symptoms. The principal commercial market includes men with:
- Urinary frequency and urgency
- Weak urinary stream
- Nocturia
- Incomplete bladder emptying
- Benign prostatic enlargement
The addressable population is large, but silodosin competes in a commoditized drug class. Tamsulosin remains the volume leader because of low generic pricing, extensive physician familiarity, and broad formulary coverage. Silodosin has differentiated positioning through higher alpha-1A selectivity, although ejaculatory dysfunction and other tolerability concerns limit use in some patients.
How does Rapaflo compare with competing BPH drugs?
| Drug | Active ingredient | Class | Commercial position | Key competitive issue |
|---|---|---|---|---|
| Rapaflo | Silodosin | Selective alpha-1A blocker | Mature branded and generic product | Generic price pressure |
| Flomax | Tamsulosin | Alpha-1 blocker | High-volume generic leader | Very low cost |
| Uroxatral | Alfuzosin | Alpha-1 blocker | Mature generic product | Limited differentiation |
| Cardura | Doxazosin | Alpha-1 blocker | Older generic product | More cardiovascular effects |
| Avodart | Dutasteride | 5-alpha-reductase inhibitor | Generic product | Slower symptom improvement |
| Proscar | Finasteride | 5-alpha-reductase inhibitor | Generic product | Best suited to prostate enlargement |
| Cialis | Tadalafil | PDE-5 inhibitor | Branded and generic | Supports erectile dysfunction and BPH |
| Myrbetriq | Mirabegron | Beta-3 agonist | Separate urinary symptom segment | Different mechanism and safety profile |
Silodosin competes primarily with tamsulosin and alfuzosin for first-line or early-line BPH treatment. Combination therapy with a 5-alpha-reductase inhibitor is relevant for men with enlarged prostates and more advanced disease.
What are Rapaflo’s sales and commercial trends?
Public company filings do not consistently report Rapaflo revenue as a separate current line item. Historical reporting placed Rapaflo within broader branded pharmaceutical revenue, limiting precise product-level tracking.[2]
The brand’s commercial trajectory has four phases:
- Launch and uptake, 2008-2012: Rapaflo established a niche among selective alpha-1A therapies.
- Peak branded period, approximately 2012-2015: Sales benefited from brand prescriptions before broad generic entry.
- Generic erosion, from 2016 onward: FDA-approved generic silodosin products materially reduced branded volume and price.
- Mature generic market, 2020 onward: The molecule remains commercially relevant, but Rapaflo is no longer a high-growth branded asset.
Estimated U.S. market structure
| Segment | Estimated 2025 annual sales | Five-year outlook |
|---|---|---|
| Rapaflo brand | $2 million-$8 million | Flat to declining |
| Generic silodosin | $35 million-$70 million | Low-single-digit growth |
| Other U.S. alpha blockers for BPH | $500 million-$900 million | Stable to modest decline |
| Global silodosin, all brands | $140 million-$190 million | Low- to mid-single-digit growth |
These figures are analyst estimates based on product maturity, generic availability, relative pricing, and the size of the BPH treatment population. They are not company-reported Rapaflo revenue figures.
What are the Rapaflo sales projections through 2029?
Base-case projection
| Year | Rapaflo U.S. brand | U.S. generic silodosin | Global silodosin market |
|---|---|---|---|
| 2025 | $2m-$8m | $35m-$70m | $140m-$190m |
| 2026 | $2m-$7m | $37m-$74m | $145m-$200m |
| 2027 | $1m-$6m | $39m-$78m | $150m-$210m |
| 2028 | $1m-$5m | $41m-$82m | $155m-$220m |
| 2029 | Below $5m | $43m-$86m | $160m-$230m |
Scenario analysis
| Scenario | Market assumptions | 2029 global silodosin sales |
|---|---|---|
| Downside | Continued price deflation, weak brand retention, limited international growth | $110m-$150m |
| Base case | Stable prescription demand and modest growth in aging markets | $160m-$230m |
| Upside | Higher adoption in Asia and Latin America, stable generic pricing | $240m-$320m |
The main driver is not premium pricing. It is prescription volume. BPH prevalence rises with age, but silodosin must capture prescriptions from tamsulosin and other low-cost alternatives.
When does Rapaflo lose exclusivity?
Rapaflo has already lost practical U.S. exclusivity. FDA-approved generic silodosin products entered the market after the expiration or resolution of the principal regulatory and patent barriers associated with the product.[3]
The relevant commercial conclusion is straightforward:
- Rapaflo is no longer protected by a meaningful market-exclusivity period.
- Generic silodosin is available in the United States.
- Any remaining listed patents do not prevent ordinary generic substitution where the FDA has approved competing products.
- Brand pricing cannot be sustained through patent protection alone.
The original product was developed by Kissei Pharmaceutical and commercialized in the United States through Watson Pharmaceuticals, which later became part of Actavis and then Allergan.[4] Current commercial rights and distribution arrangements should be distinguished from historical development ownership.
What patents protect Rapaflo?
Rapaflo’s original patent estate centered on Kissei’s silodosin chemical and pharmaceutical technology. Historical U.S. Orange Book listings included patents associated with the silodosin compound and its use in treating BPH.[3]
Principal patent categories
| Patent category | Commercial purpose | Current effect |
|---|---|---|
| Silodosin compound patents | Protect the active pharmaceutical ingredient | Expired or no longer commercially blocking |
| Pharmaceutical composition patents | Protect capsules and drug compositions | Limited value after generic approval |
| Method-of-use patents | Protect treatment of BPH symptoms | Narrow scope and difficult enforcement |
| Manufacturing patents | Protect synthesis or intermediates | May affect specific processes but generally do not block approved formulations |
| Pediatric exclusivity | Temporarily extends regulatory protection | Historical, not a current barrier |
The strength of the estate is low for present-day U.S. market protection. A generic manufacturer can avoid an expired compound patent and may use a non-infringing manufacturing route. Formulation or process claims can create litigation exposure, but they generally do not restore brand-level exclusivity after broad generic entry.
What is the Orange Book status of Rapaflo?
The FDA Orange Book identifies approved drug products, therapeutic equivalents, and relevant patent or exclusivity information.[3] Rapaflo is a small-molecule prescription product, not a biologic. Its competitive analysis therefore depends on ANDA approvals, therapeutic-equivalence ratings, listed patents, and substitution rules rather than biosimilar interchangeability.
The market implications are:
- Generic silodosin can compete through the ANDA pathway.
- Orange Book listing history is more important than biologic patent dance procedures.
- No biosimilar pathway applies.
- Formulation differences may affect individual generic products but do not materially protect the Rapaflo brand.
Which companies are challenging Rapaflo?
Generic competition has come from ANDA applicants and manufacturers of silodosin capsules. The relevant competitors include large generic companies, specialty generics manufacturers, and contract-manufactured products distributed under multiple labels.
The competitive set can change as suppliers enter or exit based on reimbursement, FDA inspections, active pharmaceutical ingredient costs, and wholesaler contracts. Because silodosin is a mature generic product, competition is driven primarily by:
- Wholesale acquisition cost
- Medicaid and commercial-plan reimbursement
- Supply reliability
- FDA manufacturing compliance
- Distributor access
- Ability to maintain 4 mg and 8 mg capsule supply
No biosimilar companies are relevant because silodosin is a chemically synthesized small molecule.
What Paragraph IV challenges and litigation affected Rapaflo?
Generic silodosin entry was associated with the standard ANDA patent-certification framework, including potential Paragraph IV challenges to listed patents. Paragraph IV certifications assert that a listed patent is invalid, unenforceable, or not infringed.
The principal commercial outcome is that generic entry occurred and the brand lost its former exclusivity. Any historical patent litigation or settlement agreements therefore have limited present value unless they contain continuing restrictions, supply arrangements, or damages provisions.
A review of current Rapaflo economics should focus on active injunctions, pending cases, and settlement terms rather than historical filings. Based on the mature generic market and established availability of generic silodosin, there is no apparent active U.S. patent barrier capable of restoring Rapaflo’s former market position.
What formulation patents protect Rapaflo?
Rapaflo is marketed as oral capsules in 8 mg and 4 mg strengths. The 4 mg strength is relevant for patients with renal impairment because the FDA label recommends dose adjustment in moderate renal impairment and contraindicates use in severe renal impairment.[1]
Formulation protection is commercially narrow. Generic manufacturers may obtain approval for equivalent dosage forms while using different excipients, capsule suppliers, manufacturing sites, or process conditions. A formulation patent would have greater value if it covered:
- A clinically necessary release profile
- A distinctive bioavailability advantage
- A difficult-to-replicate excipient system
- A combination product
- A method linked to a specific patient population
Rapaflo does not have the market profile of an extended-release platform or specialty delivery system. Its conventional oral capsule format limits formulation-based differentiation.
What FDA regulatory status does Rapaflo have?
The FDA approved Rapaflo through the new drug application pathway for BPH. Generic silodosin products are approved through ANDAs that demonstrate pharmaceutical equivalence and bioequivalence to the reference listed drug.[1][3]
Regulatory considerations include:
- 8 mg and 4 mg capsule strengths
- Renal-dose restrictions
- Contraindication with strong CYP3A4 inhibitors
- Risk of orthostatic hypotension
- Intraoperative floppy iris syndrome in cataract surgery
- Abnormal ejaculation and anejaculation
- Standard BPH labeling and postmarketing surveillance
These safety and labeling requirements apply to the generic market as well as the brand. They do not create a meaningful barrier to substitution.
What licensing deals shaped Rapaflo’s market?
Kissei Pharmaceutical developed silodosin and entered into U.S. commercialization arrangements with Watson Pharmaceuticals. Watson later became part of Actavis, which was acquired by Allergan in 2015. The transaction history placed Rapaflo within Allergan’s broader branded pharmaceutical portfolio.[4][5]
The licensing structure matters for historical ownership and revenue attribution, but it does not create a current competitive advantage. The asset is now commercially constrained by generic substitution, mature clinical positioning, and limited brand investment.
How strong is the Rapaflo patent estate?
Patent strength assessment
| Factor | Assessment | Commercial impact |
|---|---|---|
| Core compound protection | Weak or expired | Does not block generics |
| Formulation protection | Limited | Low protection for conventional capsules |
| Method-of-use protection | Narrow | Difficult to use against routine BPH prescribing |
| Manufacturing protection | Potentially relevant to specific processes | Usually avoidable |
| Regulatory exclusivity | Expired | No current barrier |
| Litigation leverage | Low | Limited settlement leverage |
| Biosimilar defense | Not applicable | Small-molecule ANDA market |
Rapaflo’s patent estate should be valued as a historical asset, not as a platform for renewed U.S. exclusivity. Any residual value would come from established physician awareness, international brand rights, supply contracts, or a differentiated commercial channel.
What generic launch risks exist for Rapaflo?
Generic launch risk is already realized rather than prospective. The remaining risk is continued erosion of brand prescriptions and reimbursement.
Key risks
- Pharmacy substitution away from Rapaflo
- Lower generic pricing
- Payer exclusion or unfavorable tier placement
- Product shortages that redirect demand between suppliers
- Reduced sales-force support
- Generic manufacturers entering during periods of favorable pricing
- Physician preference for tamsulosin or newer BPH therapies
- Safety-related switching in patients with cataract surgery or hypotension concerns
The principal opportunity for a generic manufacturer is reliable supply at competitive cost. The principal risk is low gross margin caused by several approved suppliers competing for limited prescription volume.
How does Rapaflo compare with tamsulosin commercially?
Tamsulosin is the stronger commercial product because it has greater prescribing familiarity, broader historical use, lower cost, and extensive generic availability. Rapaflo’s clinical differentiation is based mainly on alpha-1A selectivity and its positioning for men who require an alternative to other alpha blockers.
| Metric | Rapaflo/silodosin | Tamsulosin |
|---|---|---|
| Brand status | Mature, heavily eroded | Mature, heavily genericized |
| Generic competition | Established | Extensive |
| Price power | Low | Very low |
| Clinical differentiation | Alpha-1A selectivity | Familiarity and broad use |
| Volume potential | Niche | Much larger |
| Growth outlook | Low-single-digit molecule growth | Stable or declining unit growth |
| Patent value | Minimal current blocking power | Minimal current blocking power |
Rapaflo can retain a niche among patients who respond well to silodosin or who are switched by physicians seeking a selective alpha-1A agent. That niche is insufficient to support significant branded growth.
What is Rapaflo’s revenue exposure for investors and licensees?
Rapaflo should be treated as a low-growth, low-patent-life-cycle asset. Revenue exposure is concentrated in:
- Residual branded prescriptions
- International markets with slower generic penetration
- Contract sales and distribution arrangements
- Generic silodosin manufacturing economics
- Portfolio-level bundling with other urology products
A buyer valuing Rapaflo should use a declining-brand model rather than a traditional protected-brand forecast. A generic manufacturer should use a volume-and-margin model, with sensitivity to API cost, FDA compliance, and the number of active suppliers.
Key Takeaways
- Rapaflo is silodosin, an oral alpha-1A blocker approved for BPH.
- U.S. branded exclusivity has ended, and generic silodosin is established.
- Estimated global silodosin sales are approximately $140 million to $190 million in 2025.
- Base-case global molecule sales could reach $160 million to $230 million by 2029.
- Rapaflo-branded U.S. sales are likely below $10 million annually.
- Tamsulosin is the primary commercial competitor and has a substantially larger prescription base.
- The Rapaflo patent estate has low present-day blocking value.
- No biosimilar risk applies because silodosin is a small-molecule drug.
- Future value depends on generic supply, international penetration, and residual brand demand rather than patent exclusivity.
FAQs
Is Rapaflo still sold in the United States?
Yes. Rapaflo may remain available through branded and authorized distribution channels, but generic silodosin has materially reduced its commercial importance.
Is silodosin the same drug as Rapaflo?
Yes. Rapaflo is the branded product, while silodosin is the active ingredient used in generic versions.
Can Rapaflo be substituted with generic silodosin?
Where an FDA-approved generic has an appropriate therapeutic-equivalence rating, pharmacy substitution may occur under applicable state law and payer rules.
Does silodosin have growth potential outside the United States?
Yes. Growth is more plausible in markets with expanding BPH diagnosis, rising healthcare access, and slower generic erosion. Asia and Latin America offer more unit-growth potential than the mature U.S. market.
What would increase Rapaflo’s commercial value?
A new indication, a clinically differentiated formulation, an improved tolerability profile, or strong rights in markets without extensive generic penetration could increase value. The existing U.S. capsule product has limited standalone growth potential.
References
-
U.S. Food and Drug Administration. (2018). Rapaflo (silodosin) prescribing information. FDA.
-
Allergan plc. (2015). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934. U.S. Securities and Exchange Commission.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: The Orange Book. FDA.
-
Watson Pharmaceuticals, Inc. (2007). Watson and Kissei enter agreement for silodosin in the United States. Company announcement.
-
Actavis plc. (2015). Actavis completes acquisition of Allergan. Company announcement.
More… ↓
