Share This Page
Drug Sales Trends for CIALIS
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for CIALIS (2012)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
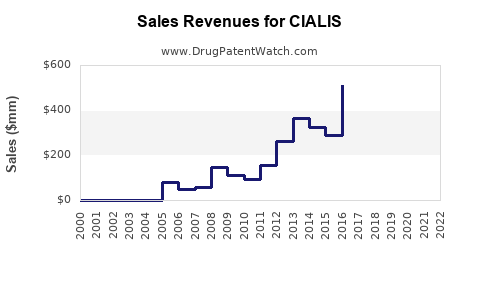
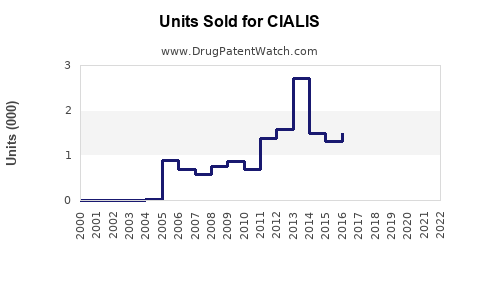
Annual Sales Revenues and Units Sold for CIALIS
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| CIALIS | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| CIALIS | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| CIALIS | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| CIALIS | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| CIALIS | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Cialis Market Analysis, Patent Expiry, Competitive Landscape, and Sales Projections
Cialis, Eli Lilly’s tadalafil brand, has moved from blockbuster status to a mature, largely generic market. U.S. patent protection ended in 2017, and generic tadalafil entered the U.S. market in 2018 under patent-settlement arrangements. Brand Cialis retains value through physician familiarity, consumer trust, daily dosing, and international markets, but generic substitution has sharply reduced revenue potential.
The global erectile dysfunction drug market remains attractive because of population aging, diabetes, cardiovascular disease, telehealth prescribing, and improved treatment access. Cialis is positioned against Viagra and sildenafil, Stendra and avanafil, Levitra and vardenafil, and nonprescription or unregulated alternatives. Tadalafil’s 36-hour duration and once-daily formulation support its continuing commercial relevance.
What is the current market position of Cialis?
Cialis is a prescription tadalafil product approved for erectile dysfunction, benign prostatic hyperplasia, and the combined treatment of both conditions. The FDA approved Cialis for erectile dysfunction in 2003 and later approved once-daily dosing and benign prostatic hyperplasia indications. Eli Lilly commercializes Cialis, while generic tadalafil is supplied by multiple manufacturers.
The product’s strongest commercial differentiators are:
- Duration of action of up to 36 hours.
- Daily low-dose use for erectile dysfunction and benign prostatic hyperplasia.
- Availability in 2.5 mg, 5 mg, 10 mg, and 20 mg strengths.
- Strong brand recognition built before generic competition.
- Dual erectile dysfunction and benign prostatic hyperplasia utility.
Tadalafil competes mainly with sildenafil, the active ingredient in Viagra, but its commercial position is different. Sildenafil generally has a lower cash price and a shorter duration, while tadalafil is often selected for treatment flexibility and daily use.
Cialis commercial performance before generic entry
Cialis generated approximately $1.9 billion in global revenue for Eli Lilly in 2017, according to the company’s annual reporting. That figure reflected the final period before broad generic erosion and included substantial international sales.
The brand’s revenue decline after generic entry followed the standard loss-of-exclusivity pattern:
| Period | Commercial event | Expected revenue effect |
|---|---|---|
| 2017 | U.S. key patent protection ended | Initial price and share pressure |
| 2018 | Generic tadalafil entered the U.S. market | Rapid decline in branded volume |
| 2019-2021 | Generic substitution expanded | Continued brand erosion |
| 2022 onward | Mature generic market | Brand sales concentrated in selected patients and markets |
Lilly no longer treats Cialis as a principal growth driver. The company’s current revenue base is concentrated in diabetes, obesity, oncology, immunology, and other strategic franchises.
How large is the erectile dysfunction drug market?
Third-party estimates differ because they use different definitions. Some reports include only prescription drugs. Others include devices, supplements, clinics, telemedicine services, and over-the-counter products.
Public market-research estimates generally place the global erectile dysfunction treatment market in the range of approximately $4 billion to $7 billion in the early 2020s, with projected annual growth commonly estimated between 6% and 9% through 2030. Prescription oral drugs represent the largest established treatment segment, but their growth is constrained by generic competition.
Key growth drivers include:
- Aging male populations in North America, Europe, Japan, China, and other developed markets.
- Higher prevalence of diabetes, obesity, hypertension, and cardiovascular disease.
- Greater willingness to seek treatment through telehealth platforms.
- Increased diagnosis and treatment of erectile dysfunction in primary care.
- Expansion of pharmacy and digital-prescribing channels.
- Increased acceptance of sexual-health treatment among older patients.
The main constraint is price erosion. Sildenafil and tadalafil are widely available as low-cost generics, limiting the ability of branded products to capture market growth.
What are the Cialis sales projections through 2030?
No current public Lilly guidance identifies Cialis as a separately forecast growth product. The following scenario is an analyst estimate for branded Cialis revenue, not company guidance. It assumes continued generic substitution, stable international availability, limited brand investment, and no major new indication.
| Fiscal year | Estimated global Cialis brand sales | Year-over-year trend |
|---|---|---|
| 2024A estimate | $450 million-$650 million | Mature post-generic market |
| 2025E | $400 million-$575 million | Down 10%-15% |
| 2026E | $360 million-$520 million | Down 8%-12% |
| 2027E | $325 million-$475 million | Down 7%-10% |
| 2028E | $300 million-$450 million | Down 5%-8% |
| 2029E | $275 million-$425 million | Down 5%-8% |
| 2030E | $250 million-$400 million | Down 4%-7% |
Under this base case, branded Cialis revenue declines at an estimated compound annual rate of approximately 6% to 9% from 2024 through 2030.
Bull case
The bull case assumes:
- Continued consumer preference for the Cialis brand.
- Premium pricing in private-pay and telehealth channels.
- Stable or expanding international branded sales.
- Limited switching among long-term daily-use patients.
- Greater diagnosis of erectile dysfunction and benign prostatic hyperplasia.
Under that scenario, Cialis could hold annual global brand sales near $600 million in the medium term and remain above $400 million through 2030.
Bear case
The bear case assumes:
- Accelerated substitution by low-cost tadalafil.
- Aggressive online pharmacy discounting.
- Increased availability of compounded or alternative tadalafil products.
- Reduced brand promotion.
- Further reimbursement pressure in Europe and other regulated markets.
Under that scenario, global brand sales could fall below $300 million before 2030.
The generic tadalafil market will be materially larger than the branded Cialis market. Generic volume may expand while total branded revenue declines because lower prices increase access and prescription frequency.
When did Cialis lose exclusivity in the United States?
The principal U.S. Cialis patent was U.S. Patent No. 5,859,006, assigned to ICOS Corporation and later associated with Eli Lilly. The patent covered tadalafil and related therapeutic use. Its listed expiration date was September 15, 2017, after applicable patent-term adjustments and pediatric exclusivity considerations.
Eli Lilly and Teva Pharmaceuticals settled patent litigation concerning generic tadalafil. The settlement permitted Teva to launch a generic version before the full practical end of all potential exclusivity barriers. Generic tadalafil entered the U.S. market in 2018.
The commercial result was a staged erosion rather than an immediate disappearance of the brand. Cialis maintained residual prescriptions through brand loyalty, physician preference, insurance structures, and patients who valued the original product.
What patents protect Cialis?
The core patent estate is substantially expired in the United States. The most important historical U.S. patent was:
| Patent | Subject matter | Assignee or holder | U.S. status |
|---|---|---|---|
| U.S. Patent No. 5,859,006 | Tadalafil compounds and therapeutic use | ICOS Corporation, later associated with Eli Lilly | Expired in 2017 |
Patent protection varied by country. International expiration dates depended on national patent prosecution, patent-term adjustments, supplementary protection certificates, and local litigation outcomes.
Cialis no longer has a commercially meaningful U.S. composition-of-matter barrier. Remaining patents, where applicable, have limited ability to prevent generic tadalafil competition because generic products can rely on expired active-ingredient protection and avoid narrow formulation or use claims.
What formulations are protected by Cialis patents?
Cialis has been sold as immediate-release oral tablets. The main commercial formulations are:
- 2.5 mg tablet.
- 5 mg tablet.
- 10 mg tablet.
- 20 mg tablet.
The important technical protection historically centered on tadalafil itself and its therapeutic use. Formulation patents generally have weaker commercial leverage than composition-of-matter patents because a generic manufacturer can develop a non-infringing tablet using the same active ingredient.
Daily-use Cialis for erectile dysfunction and benign prostatic hyperplasia created a meaningful commercial distinction. It did not preserve broad exclusivity after generic tadalafil became available because generic manufacturers could market equivalent strengths and indications subject to FDA labeling requirements.
What is the Orange Book status of Cialis?
Cialis was listed in the FDA Orange Book with patent information for tadalafil products. The principal listed patent protection expired before or around the beginning of broad U.S. generic competition. Generic applicants used the abbreviated new drug application pathway and filed patent certifications connected to the listed patents.
The practical Orange Book position is now that Cialis is an off-patent reference-listed drug with multiple generic tadalafil equivalents. The Orange Book does not prevent generic competition based on the expired core patent.
FDA approval of generic tadalafil does not establish brand equivalence in marketing, patient preference, or commercial pricing. It does establish pharmaceutical equivalence and therapeutic equivalence when the generic is approved with an “AB” rating.
Which companies challenged Cialis patents?
Teva was the most commercially significant challenger because its settlement led to U.S. generic tadalafil entry. Other generic manufacturers entered the market after patent barriers were reduced or expired.
The competitive field has included major generic companies such as:
- Teva Pharmaceuticals.
- Mylan, now part of Viatris.
- Dr. Reddy’s Laboratories.
- Cipla.
- Aurobindo Pharma.
- Zydus Pharmaceuticals.
- Torrent Pharmaceuticals.
- Hikma and other regional suppliers.
The commercial effect of multiple approved suppliers is usually rapid price compression, particularly in cash-pay and mail-order channels.
What patent litigation and settlement agreements affected Cialis?
The key litigation involved Eli Lilly and Teva over tadalafil patent rights. The settlement provided a controlled generic-launch pathway rather than an immediate full market opening. Such settlements can preserve a portion of branded revenue during the remaining patent period while giving the challenger a defined entry date.
The litigation did not create a durable barrier after the principal patent expired. No current U.S. litigation is known to provide Cialis with a material ability to block ordinary generic tadalafil competition.
Patent settlements remain relevant to market analysis because the timing of first generic entry affects:
- The length of the brand’s final high-revenue period.
- The value of authorized-generic arrangements.
- Generic first-filer economics.
- Pharmacy substitution rates.
- Net price erosion in the first two years after entry.
How does Cialis compare with Viagra and generic sildenafil?
| Attribute | Cialis | Viagra | Generic market |
|---|---|---|---|
| Active ingredient | Tadalafil | Sildenafil | Tadalafil, sildenafil, vardenafil, avanafil |
| Duration | Up to 36 hours | Approximately 4-5 hours | Depends on active ingredient |
| Daily dosing | Available | Not the primary branded use | Available for tadalafil |
| BPH indication | Yes | No | Tadalafil available |
| U.S. patent position | Expired | Expired | Broad generic competition |
| Brand strength | High | High | Price-driven |
| Main commercial advantage | Long duration and daily use | Familiarity and low-cost generic availability | Affordability |
Cialis has a stronger technical and clinical differentiation than Viagra because tadalafil supports daily treatment and benign prostatic hyperplasia therapy. That differentiation supports brand retention but does not support prior blockbuster pricing after generic entry.
What generic entry risks exist for Cialis?
Generic entry risk is no longer a future event. It is the central commercial condition for Cialis.
The principal risks are:
- Continued unit substitution from brand to generic tadalafil.
- Pharmacy benefit managers favoring low-cost products.
- Telehealth providers prescribing generic tadalafil by default.
- Brand-price increases creating wider patient cost differences.
- International reimbursement agencies shifting toward generic procurement.
- New entrants competing on distribution, convenience, and subscription pricing.
A smaller risk comes from compounded tadalafil and unregulated online products. These products may increase price pressure but carry quality, regulatory, and supply-chain risks.
What is the biosimilar risk for Cialis?
Cialis has no biosimilar risk because it is a chemically synthesized small-molecule drug, not a biologic. The relevant competitive pathway is the FDA abbreviated new drug application for generic tadalafil.
This distinction matters commercially. Generic applicants can generally rely on pharmaceutical equivalence and bioequivalence studies rather than the more complex comparative clinical and manufacturing package required for biosimilars.
How strong is the Cialis patent estate?
The current patent estate is weak for blocking purposes and strong only as a historical record of protection. The principal compound patent has expired, and generic tadalafil is widely available.
| Patent-strength factor | Assessment |
|---|---|
| Core compound protection | Expired |
| U.S. generic blocking power | None of practical significance |
| Formulation protection | Limited |
| Method-of-use protection | Limited after generic labeling pathways |
| International residual value | Country-specific and declining |
| Manufacturing barriers | Low to moderate |
| Brand recognition | Still commercially meaningful |
| Litigation leverage | Low |
Manufacturing is not a major barrier. Tadalafil is a small molecule with established synthesis and multiple qualified suppliers. Regulatory approval, quality systems, distribution, and pricing are more important than patent exclusivity.
What is the FDA regulatory status of Cialis?
Cialis is FDA-approved for:
- Erectile dysfunction.
- Benign prostatic hyperplasia.
- Erectile dysfunction and benign prostatic hyperplasia together.
Tadalafil is also marketed under other brands for pulmonary arterial hypertension, including Adcirca, subject to separate labeling and commercial positioning. The Cialis and Adcirca franchises should not be combined when estimating erectile dysfunction revenue.
The FDA-approved Cialis label contains important contraindications involving nitrates because tadalafil can cause a clinically significant reduction in blood pressure when combined with nitrate medicines. Alpha blockers, antihypertensive drugs, alcohol, and certain enzyme inhibitors also affect prescribing decisions. These factors influence market segmentation but do not materially restore brand exclusivity.
What is the commercial outlook for Cialis and tadalafil?
Cialis will remain a recognized brand, but tadalafil will be the larger commercial category. The market’s economic value has shifted from branded price and patent protection to prescription volume, distribution, patient acquisition, and adherence.
The most attractive growth channels are:
- Telehealth platforms.
- Subscription-based pharmacies.
- Private-pay erectile dysfunction clinics.
- Daily tadalafil for patients with both erectile dysfunction and benign prostatic hyperplasia.
- International markets with slower generic penetration.
- Primary-care screening linked to diabetes and cardiovascular disease.
The least attractive segment is conventional U.S. branded reimbursement, where generic substitution is entrenched.
For investors and licensing teams, Cialis is primarily a mature cash-flow and brand-equity asset rather than a pipeline-like growth asset. Any value uplift would likely require a new delivery system, differentiated combination product, novel indication, or digital adherence model. Existing tadalafil tablets alone do not provide a credible path back to blockbuster economics.
Key Takeaways
- Cialis generated about $1.9 billion in global sales in 2017 before broad U.S. generic competition.
- The principal U.S. tadalafil patent, U.S. Patent No. 5,859,006, expired in 2017.
- Generic tadalafil entered the U.S. market in 2018 after Eli Lilly-Teva patent litigation and settlement.
- Cialis brand revenue is expected to decline gradually from an estimated $450 million-$650 million in 2024 to $250 million-$400 million by 2030.
- Tadalafil volume can grow even while branded Cialis revenue declines.
- Cialis retains advantages in duration, daily dosing, and benign prostatic hyperplasia treatment.
- No material biosimilar risk exists because tadalafil is a small-molecule drug.
- Current value resides in brand recognition, distribution, international markets, and patient preference rather than patent exclusivity.
- Generic tadalafil is the dominant commercial product and will continue to set market pricing.
FAQs About Cialis Market Size, Patents, and Sales
Will Cialis become an over-the-counter drug?
There is no FDA approval converting Cialis or tadalafil to over-the-counter status. The product remains prescription-only in the United States.
Does tadalafil have more commercial value than Cialis?
Yes. Tadalafil includes generic products and multiple branded products, while Cialis refers to Eli Lilly’s brand. The total tadalafil market is substantially larger than Cialis brand revenue.
Can a new company obtain patents on tadalafil products?
A company may obtain patents on novel formulations, combinations, delivery systems, manufacturing processes, or new uses. Such patents would not restore broad exclusivity over tadalafil itself.
Is daily Cialis more defensible than as-needed Cialis?
Daily Cialis has stronger clinical differentiation because of continuous treatment and benign prostatic hyperplasia utility. It is not broadly defensible against generic tadalafil because generic products can be approved in the same strengths and indications.
What would increase Cialis sales after 2030?
The most credible growth drivers would be a new FDA-approved indication, a patented delivery system, a differentiated combination product, or a branded service model that improves adherence and prescription retention.
References
-
Eli Lilly and Company. (2018). 2017 annual report. Eli Lilly and Company.
-
Eli Lilly and Company. (2024). 2023 annual report. Eli Lilly and Company.
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Cialis prescribing information. U.S. Department of Health and Human Services.
-
U.S. Patent No. 5,859,006. (1999). Pyrazolopyrimidinones for the treatment of impotence. United States Patent and Trademark Office.
-
U.S. Food and Drug Administration. (2018). FDA approves first generic versions of Cialis. U.S. Department of Health and Human Services.
-
Grand View Research. (2024). Erectile dysfunction drugs market size, share and trends analysis report. Grand View Research.
-
Fortune Business Insights. (2024). Erectile dysfunction drugs market size, share and industry analysis. Fortune Business Insights.
More… ↓