Share This Page
Drug Sales Trends for SUCRALFATE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for SUCRALFATE (2011)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
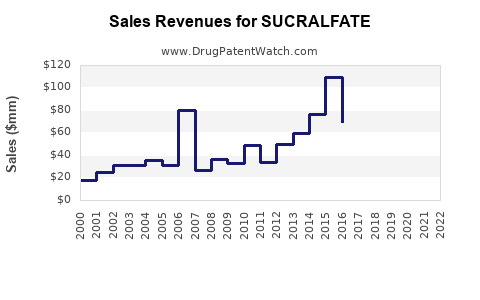
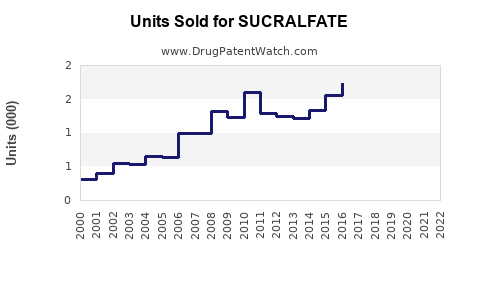
Annual Sales Revenues and Units Sold for SUCRALFATE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| SUCRALFATE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| SUCRALFATE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| SUCRALFATE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Sucralfate Market Analysis and Sales Projections: Drug Demand, Competition, Patents, and Generic Outlook
Sucralfate is a mature, off-patent gastrointestinal drug used primarily for short-term treatment of active duodenal ulcers and, in some markets, gastric ulcers, reflux-related disease, and mucosal injury. Its commercial market is generic, fragmented, and price-sensitive. U.S. revenue is concentrated in prescription tablets and oral suspension, with limited branded pricing power. A reasonable base-case estimate places the global sucralfate market in the low hundreds of millions of dollars annually, with low-single-digit growth driven by volume rather than price.
What is sucralfate and how is it used?
Sucralfate is a locally acting aluminum complex of sulfated sucrose. It binds to ulcerated tissue and forms a protective barrier against acid, pepsin, and bile salts. Systemic absorption is limited, although aluminum exposure remains relevant in patients with significant renal impairment.
The FDA-approved U.S. product is marketed in tablet and oral suspension forms. The reference product is Carafate, originally associated with Marion Laboratories and later distributed through various commercial arrangements. Generic sucralfate products are available from multiple manufacturers.
| Attribute | Sucralfate |
|---|---|
| Active ingredient | Sucralfate |
| Primary therapeutic class | Gastrointestinal mucosal protectant |
| Main approved U.S. use | Short-term treatment of active duodenal ulcer |
| Common dosage forms | 1-gram tablet; 1-gram-per-10-mL oral suspension |
| Administration | Usually four times daily for active ulcer treatment |
| Main competitors | Proton-pump inhibitors, H2-receptor antagonists, antacids, alginates |
| Regulatory status | FDA-approved prescription drug |
| U.S. patent position | Core composition and product protection expired |
| Biosimilar relevance | None; sucralfate is a small-molecule drug |
The FDA label recommends 1 gram four times daily for active duodenal ulcer treatment, generally for four to eight weeks. The dosing burden is materially higher than once-daily proton-pump inhibitor therapy, limiting use in chronic maintenance treatment. (FDA, 2023)
How large is the sucralfate market?
The global sucralfate market is best understood as a mature generic market rather than a branded pharmaceutical franchise. Public companies generally do not report sucralfate revenue separately, and retail prescription data do not capture all international or institutional sales.
A reasonable market framework is:
| Market segment | Estimated annual market characteristics |
|---|---|
| United States prescription market | Low tens of millions of dollars at manufacturer or pharmacy-equivalent value |
| Europe | Fragmented, with availability varying by country and reimbursement system |
| India and other price-sensitive markets | Higher unit volumes but lower prices |
| Latin America and Asia-Pacific | Meaningful generic demand, especially for ulcer and dyspepsia treatment |
| Global market | Likely low hundreds of millions of dollars, depending on inclusion of hospital, retail, suspension, and private-market sales |
These estimates reflect the age of the product, generic competition, low average selling prices, and the absence of a major branded commercial platform. Market-research reports often produce higher figures because they may include distributor revenue, multiple geographic tiers, private-label products, and adjacent mucosal-protection indications.
What drives sucralfate demand?
Demand is supported by several factors:
- Continued use in duodenal ulcer treatment and refractory mucosal injury.
- Availability in both solid and liquid dosage forms.
- Low acquisition cost compared with newer branded gastrointestinal drugs.
- Use in patients for whom clinicians want a locally acting protective agent.
- Continued prescribing in markets where proton-pump inhibitors are less accessible or more expensive.
Demand is constrained by:
- Four-times-daily dosing.
- Competition from inexpensive proton-pump inhibitors.
- Reduced incidence of uncomplicated peptic ulcer disease in some developed markets.
- Greater emphasis on Helicobacter pylori eradication and acid suppression.
- Generic price erosion.
- Medication-administration complexity in older patients and institutional settings.
What are the current sales projections for sucralfate?
The base-case forecast is for modest global revenue growth, with volume growth offset by falling prices in competitive markets.
Base-case global sales projection
| Year | Estimated global market value | Growth assumption |
|---|---|---|
| 2024 | $150 million-$225 million | Baseline |
| 2025 | $153 million-$232 million | 1%-3% |
| 2026 | $156 million-$239 million | 1%-3% |
| 2027 | $159 million-$246 million | 1%-3% |
| 2028 | $162 million-$254 million | 1%-3% |
| 2029 | $165 million-$262 million | 1%-3% |
The midpoint base case implies approximately 2% compound annual growth through 2029. This is a market-value forecast, not a forecast for any individual manufacturer.
Scenario analysis
| Scenario | 2029 market estimate | Main assumptions |
|---|---|---|
| Downside | $130 million-$175 million | Faster substitution by proton-pump inhibitors, further generic price compression |
| Base case | $165 million-$262 million | Stable prescription volume and modest emerging-market growth |
| Upside | $270 million-$350 million | Increased liquid-form demand, broader mucosal-protection use, stronger developing-market volume |
The upside case requires volume expansion rather than premium pricing. Sucralfate has limited ability to sustain price increases because multiple generic suppliers can manufacture tablets and suspension.
How does sucralfate compare with proton-pump inhibitors?
Proton-pump inhibitors are the principal commercial substitute for sucralfate in acid-related gastrointestinal disease. Omeprazole, pantoprazole, lansoprazole, esomeprazole, and rabeprazole have broader use across gastroesophageal reflux disease, erosive esophagitis, peptic ulcer disease, and Helicobacter pylori treatment.
| Factor | Sucralfate | Proton-pump inhibitors |
|---|---|---|
| Primary action | Physical mucosal barrier | Suppression of gastric acid secretion |
| Typical dosing burden | Often four times daily | Often once daily |
| Dosage forms | Tablets and suspension | Capsules, tablets, granules, injectable forms |
| Chronic GERD use | Limited | Established |
| Generic price | Low | Low |
| Adherence profile | Weaker because of frequency and administration timing | Stronger |
| Key safety issue | Aluminum exposure and drug-binding interactions | Long-term acid-suppression concerns |
| Commercial outlook | Stable niche | Larger and broader market |
Sucralfate retains a role where clinicians want mucosal coating, where suspension is preferred, or where a patient has a specific intolerance or treatment history involving acid-suppressive agents. It is unlikely to regain broad share from proton-pump inhibitors without a new clinical indication or formulation advantage.
What patents protect sucralfate?
The original sucralfate composition, Carafate product protection, and early use patents expired decades ago. No meaningful composition-of-matter exclusivity remains in the United States.
Patent position
| Patent category | Current position |
|---|---|
| Sucralfate composition patent | Expired |
| Original Carafate product patents | Expired |
| Tablet formulation protection | Expired or commercially immaterial |
| Oral suspension protection | No broad blocking patent estate identified |
| Method-of-use patents | Historical rights expired or have limited commercial relevance |
| Manufacturing patents | Potentially relevant to process economics, but unlikely to block routine generic supply |
| Orange Book exclusivity | No meaningful remaining new-drug exclusivity |
The commercial risk is therefore not loss of patent exclusivity. It is price competition, supply reliability, regulatory compliance, and the ability to secure stable raw-material and manufacturing capacity.
What is the FDA and Orange Book status of sucralfate?
Sucralfate is an FDA-approved prescription drug. Generic products are approved through abbreviated new drug applications under section 505(j) of the Federal Food, Drug, and Cosmetic Act.
The Orange Book identifies approved reference and generic products, therapeutic-equivalence ratings, and patent or exclusivity information where applicable. For a mature product such as sucralfate, the relevant commercial issue is generally product availability and therapeutic-equivalence status rather than an active patent challenge. (FDA, 2024a)
FDA regulatory considerations
Manufacturers must demonstrate that their products meet applicable quality, identity, strength, purity, and performance requirements. The principal regulatory risks include:
- Suspension uniformity and redispersibility.
- Particle-size control.
- Assay and impurity specifications.
- Tablet dissolution and content uniformity.
- Container-closure compatibility.
- Stability of liquid formulations.
- Microbial control in oral suspension products.
Liquid sucralfate has greater manufacturing and logistics complexity than tablets. It requires more extensive control of physical stability, packaging, shipping, and dosing accuracy.
Are there Paragraph IV challenges to sucralfate?
Paragraph IV litigation is not a significant current feature of the sucralfate market. The relevant patent estate is too old to support a conventional branded-generic patent dispute involving the core active ingredient.
Generic entrants historically could rely on ANDA pathways once applicable patents and exclusivities expired. Current market entry decisions are more likely to involve:
- FDA approval timing.
- Manufacturing-site readiness.
- Product-specific bioequivalence or quality requirements.
- Commercial supply contracts.
- Drug-shortage or discontinuation risk.
- State substitution and payer access.
A new entrant would face a low legal barrier but a potentially difficult commercial environment because established suppliers can compete aggressively on price.
What formulations are protected or commercially differentiated?
Sucralfate is available mainly in 1-gram tablets and oral suspension. Formulation differentiation is limited but still commercially relevant.
Tablets
Tablets offer lower manufacturing and distribution costs, longer shelf-life advantages, and simpler pharmacy handling. They are the dominant commercial format in many markets.
Oral suspension
Suspension is important for patients with dysphagia, enteral feeding requirements, pediatric use where prescribed, and institutional care. It may command a higher price per treatment course than tablets, but its market is smaller and more exposed to supply interruptions.
Potential formulation opportunities
Potentially differentiated products could include:
- Ready-to-use suspension with improved stability.
- Unit-dose packaging.
- Dosing devices designed for administration through feeding tubes.
- Lower-volume suspension with equivalent dose delivery.
- Hospital-focused packaging.
- Combination products, subject to clinical and regulatory requirements.
These opportunities are formulation and commercial improvements, not substitutes for a strong patent estate. A company seeking exclusivity would need a genuinely novel formulation, delivery system, or clinical use supported by patentable technical features and FDA approval.
Which companies compete in the sucralfate market?
The market is supplied by generic pharmaceutical companies, regional manufacturers, contract manufacturers, and distributors. The competitive field varies by country and by dosage form.
In the United States, market participation has included generic suppliers such as Actavis, Amneal, Rising Pharmaceuticals, and other FDA-approved manufacturers over time. Product availability changes as companies discontinue products, transfer applications, or adjust production. Brand and private-label distribution also affects pharmacy-level visibility.
The market has no single dominant global company with a durable sucralfate franchise. Competitive advantage generally comes from:
- Reliable API sourcing.
- FDA-compliant manufacturing.
- Consistent suspension supply.
- Low-cost tablet production.
- Hospital and wholesaler contracts.
- Ability to maintain inventory during supply disruptions.
What licensing deals and partnerships affect sucralfate?
Sucralfate has no widely reported, high-value licensing transaction comparable to partnerships involving novel gastrointestinal drugs. Commercial arrangements are more likely to involve:
- Contract manufacturing.
- Authorized generic supply.
- Regional distribution.
- Product-rights transfers.
- Private-label supply.
- API procurement agreements.
Because the product is mature and largely off-patent, transaction value depends on manufacturing access, geographic distribution, regulatory approvals, and supply commitments rather than on exclusive intellectual property.
What patent litigation affects sucralfate?
No major active U.S. patent litigation materially changes the sucralfate market outlook. Historical disputes involving Carafate or generic approval are unlikely to create current blocking rights because the original exclusivity period has ended.
The principal legal exposures are commercial and regulatory:
- Product-liability claims.
- Manufacturing-quality enforcement.
- Labeling disputes.
- Contract disputes involving supply or distribution.
- Regulatory actions involving current good manufacturing practice compliance.
What generic launch scenarios exist for sucralfate?
Scenario 1: Additional tablet entrant
A new tablet supplier could enter with limited legal barriers. The likely effect would be lower generic prices and modest share redistribution. Incumbents with established pharmacy and wholesaler relationships would retain an advantage.
Scenario 2: Suspension-focused entrant
A manufacturer offering reliable oral suspension could capture disproportionate value because liquid supply is more operationally difficult. The opportunity is larger if existing suppliers experience shortages or discontinuations.
Scenario 3: Hospital and institutional supplier
A supplier could target hospitals, nursing facilities, and long-term-care pharmacies with unit-dose packaging, feeding-tube compatibility, and dependable contract fulfillment.
Scenario 4: Reformulated product
A novel formulation could support higher pricing if it improves adherence, stability, or administration. It would require clinical, regulatory, and patent investment that may be difficult to justify against a low-priced generic market.
How strong is the sucralfate patent estate?
The patent estate is weak for blocking purposes and strong only in the narrow sense that the product has a long history of regulatory acceptance and established manufacturing know-how.
| Patent-strength factor | Assessment |
|---|---|
| Composition-of-matter protection | None of current commercial value |
| Core product protection | Expired |
| Method-of-use protection | Limited and generally expired |
| Formulation protection | Potentially available only for genuinely novel products |
| Manufacturing know-how | Moderate operational value |
| Freedom to operate for standard generic | Generally favorable |
| Ability to sustain premium pricing | Low |
The main barrier is execution, not patent exclusion. A supplier that can produce compliant tablets or suspension at scale can compete, but it must accept low margins and variable demand.
What geographic markets offer the strongest growth?
Emerging markets offer the highest unit-volume potential because sucralfate remains familiar to physicians and is less expensive than many branded gastrointestinal therapies. India, Southeast Asia, Latin America, and parts of the Middle East may provide greater prescription volume than the United States, although average selling prices are lower.
The United States remains attractive for regulated-market credibility and stable reimbursement, but growth is constrained by generic competition and substitution by proton-pump inhibitors.
Europe is fragmented. National reimbursement decisions, product availability, and local treatment guidelines create different market conditions by country.
What is the revenue exposure for manufacturers?
Sucralfate is unlikely to be a major revenue driver for diversified pharmaceutical companies. It can still be commercially useful as:
- A low-cost portfolio product.
- A hospital-contract product.
- A suspension supply niche.
- A regional gastrointestinal franchise component.
- A manufacturing-utilization product for established facilities.
For a generic manufacturer, annual product revenue may range from subscale levels to several million dollars depending on market share, dosage form, geography, and supply continuity. Margin performance is more sensitive to production cost and competition than to medical demand.
Key Takeaways
- Sucralfate is an FDA-approved, mature generic gastrointestinal drug with no meaningful remaining core patent exclusivity.
- The global market is likely in the low hundreds of millions of dollars annually, with a base-case 2029 value of approximately $165 million to $262 million.
- Expected growth is low, generally 1% to 3% annually, and is driven mainly by volume.
- Proton-pump inhibitors remain the primary competitive threat because of once-daily dosing and broader indications.
- Oral suspension is the most commercially differentiated dosage form because it has higher manufacturing and supply complexity.
- Paragraph IV litigation and biosimilar risk are not material current issues.
- Generic entry is legally straightforward but commercially difficult because of low prices and established suppliers.
- The strongest opportunities are reliable suspension supply, institutional distribution, emerging markets, and specialized packaging.
- Sucralfate’s patent estate is weak as a blocking asset. Manufacturing capability, FDA compliance, and distribution access determine commercial performance.
Frequently Asked Questions
Is sucralfate still profitable for generic drug manufacturers?
Yes, but usually as a portfolio or supply-contract product rather than a standalone growth asset. Profitability depends on manufacturing cost, dosage form, market share, and supply reliability.
Will sucralfate sales increase through 2030?
A modest increase is more likely than a major expansion. Base-case growth should remain in the low-single-digit range unless a new formulation or indication expands use.
Does sucralfate have remaining U.S. patent protection?
The original composition and Carafate-related protections have expired. A newly developed formulation could obtain separate patents if it satisfies novelty, non-obviousness, and other legal requirements.
Is sucralfate subject to biosimilar competition?
No. Sucralfate is a small-molecule drug, so its competitive pathway is generic approval through ANDAs rather than biosimilar approval.
Which sucralfate product has the strongest commercial opportunity?
Oral suspension has the clearest niche because it addresses administration needs that tablets do not. The opportunity remains limited by total market size and the availability of generic alternatives.
References
-
U.S. Food and Drug Administration. (2023). Carafate (sucralfate) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
U.S. Food and Drug Administration. (2024b). Drugs@FDA: FDA-approved drugs database. FDA.
-
U.S. Food and Drug Administration. (2024c). Electronic Orange Book patent and exclusivity information. FDA.
-
National Library of Medicine. (2024). Sucralfate drug information. DailyMed.
More… ↓
